Here’s what happened last week and why it matters more than the headline suggests.
IBM’s CEO stood up and told investors that enterprise clients were heavily distracted by what he called rapidly evolving, industry-wide cybersecurity concerns. The stock fell about 25%. And while that was bad for IBM, it was rocket fuel for the cybersecurity sector. Palo Alto Networks jumped roughly 7% in a single session. CrowdStrike surged about 12%. The message the market read was simple: IBM’s pain is the pure-plays’ gain.
But IBM’s warning isn’t just a one-day trade. It’s a confirmation of something that has been building all year.
The Structural Shift Nobody Wants to Fully Admit
AI is not just a productivity story. It is also a threat amplification story. Attackers are using AI to launch more sophisticated phishing campaigns, identify security vulnerabilities faster, and automate attacks at a scale that would have been impossible two years ago. The defense has to keep up.
Global cybersecurity spending is on track to exceed $300 billion in 2026. Fortune Business Insights projects the market growing from approximately $248.28 billion in 2026 to about $699.39 billion by 2034, a 13.8% compound annual growth rate. That is not a cyclical number. That is a structural expansion with AI as both the problem and the accelerant.
Palo Alto Networks is positioned near the center of that expansion. And the company’s strategy – which management calls platformization – is increasingly looking like the right bet for how enterprises want to buy security.
The Numbers Behind the Stock
In Q3 fiscal 2026, Palo Alto reported revenue of $3.0 billion, up 31% year over year. Next-Generation Security ARR climbed 60% year over year to $8.1 billion. The company raised full-year guidance on that earnings call.
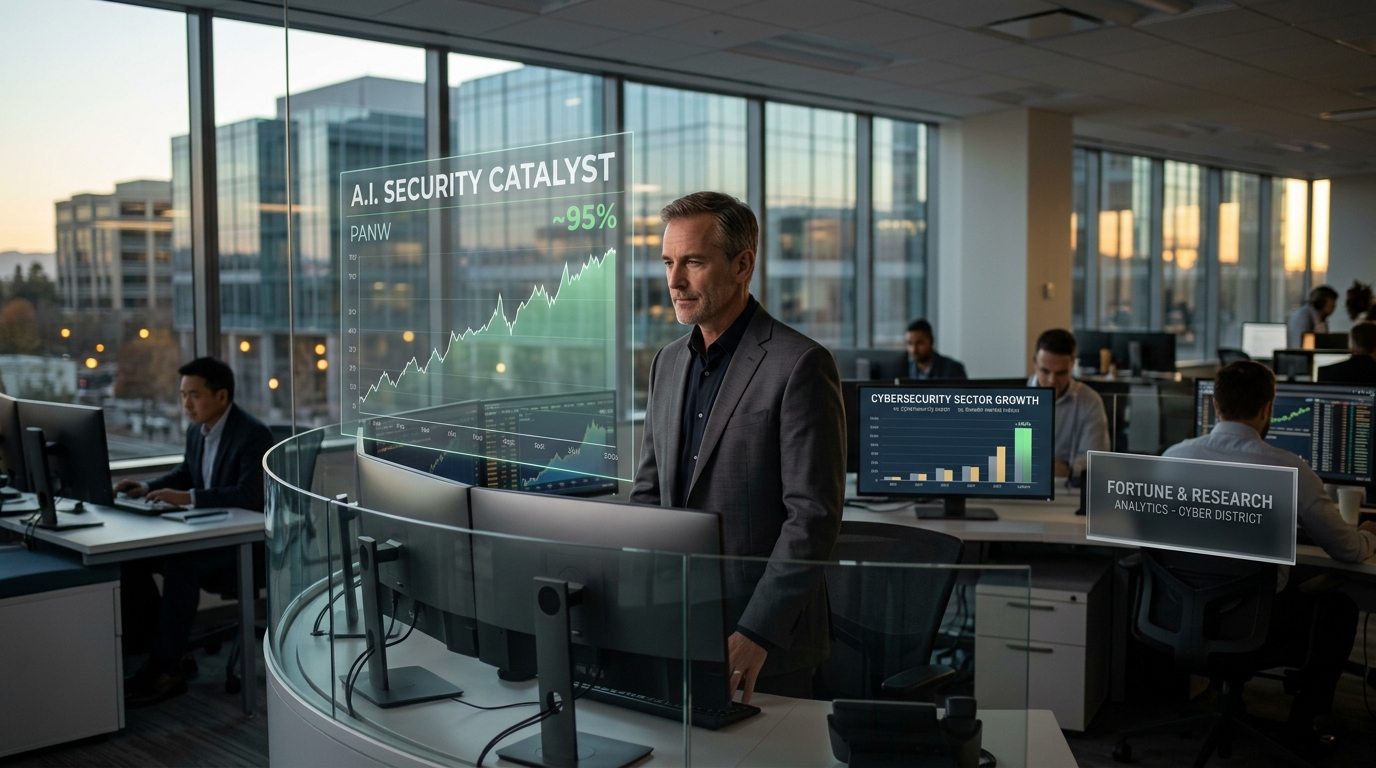
Palo Alto stock is up roughly 95% year to date. That run has not been built on hope. It has been built on execution – 31% revenue growth, a platformization strategy that is showing up in ARR numbers, and an AI-driven security expansion that is pulling customers toward consolidated spending with a single vendor.
The platformization angle is worth understanding because it changes the competitive dynamic. Rather than competing on individual point products, Palo Alto encourages enterprises to replace multiple security tools with a single integrated platform covering network, cloud, endpoint, and identity. When that works, it creates stickiness that is very hard for competitors to dislodge. CEO Nikesh Arora has been direct about this: customers are turning to Palo Alto to secure their AI deployments at scale.
The Valuation Question Is the Only Real Debate
The bear case is not complicated. Palo Alto trades at a stretched forward multiple, and a company growing this fast at this valuation requires consistent outsized surprises to justify the price. One disappointing quarter would be painful for the stock, as the sector has demonstrated with other high-multiple names through 2026.
That tension is real. It is not something to dismiss.
But the counterpoint is that the threat environment is not getting less intense. IBM’s commentary this week confirms that enterprises are not pulling back from cybersecurity spending – they are accelerating it. The AI-powered phishing and identity attacks that Palo Alto specializes in defending against are getting more frequent, not less.
And the competitive landscape may actually be thinning. OpenAI’s Trusted Access for Cyber program highlighted a small group of major ecosystem partners – Palo Alto among them – which could help reinforce platform leaders’ mindshare with enterprise buyers.
What to Watch Next
The next meaningful data point for Palo Alto is its fiscal Q4 2026 earnings report, expected in mid-August. Between now and then, the questions investors are asking are straightforward: Can the company sustain 30%-plus revenue growth? Is the platformization ARR continuing to compound at 60% year over year? And is management’s read on enterprise cybersecurity budgets improving or showing any signs of fatigue?
IBM’s CEO just answered the last question. Budgets are not the problem. Urgency is high. The enterprise IT decision-maker is more focused on cyber risk today than at any point in recent memory.
That does not mean Palo Alto is cheap. It isn’t. But it does mean the demand environment behind the stock is as strong as it has been – and the AI arms race in security may be just getting started.
The part worth watching is not the next earnings beat. It is whether Palo Alto can keep compounding its Next-Generation Security ARR at the rate it has been. That number tells you more about the durability of this business than any single quarterly result.
At ~95% year to date, the easy money is gone. What’s left is the question of whether the AI security buildout has years of runway still ahead – or whether this is a valuation story waiting to mean-revert. Both arguments are alive. The IBM data point just moved the needle toward the bulls, at least for now.
Disclaimer: This editorial is for informational purposes only and does not constitute investment advice, a recommendation, or a solicitation to buy or sell any security. The information presented reflects publicly available data as of July 18, 2026. Past performance is not indicative of future results. Investing involves risk, including the possible loss of principal. Always conduct your own research and consult a qualified financial advisor before making any investment decisions.