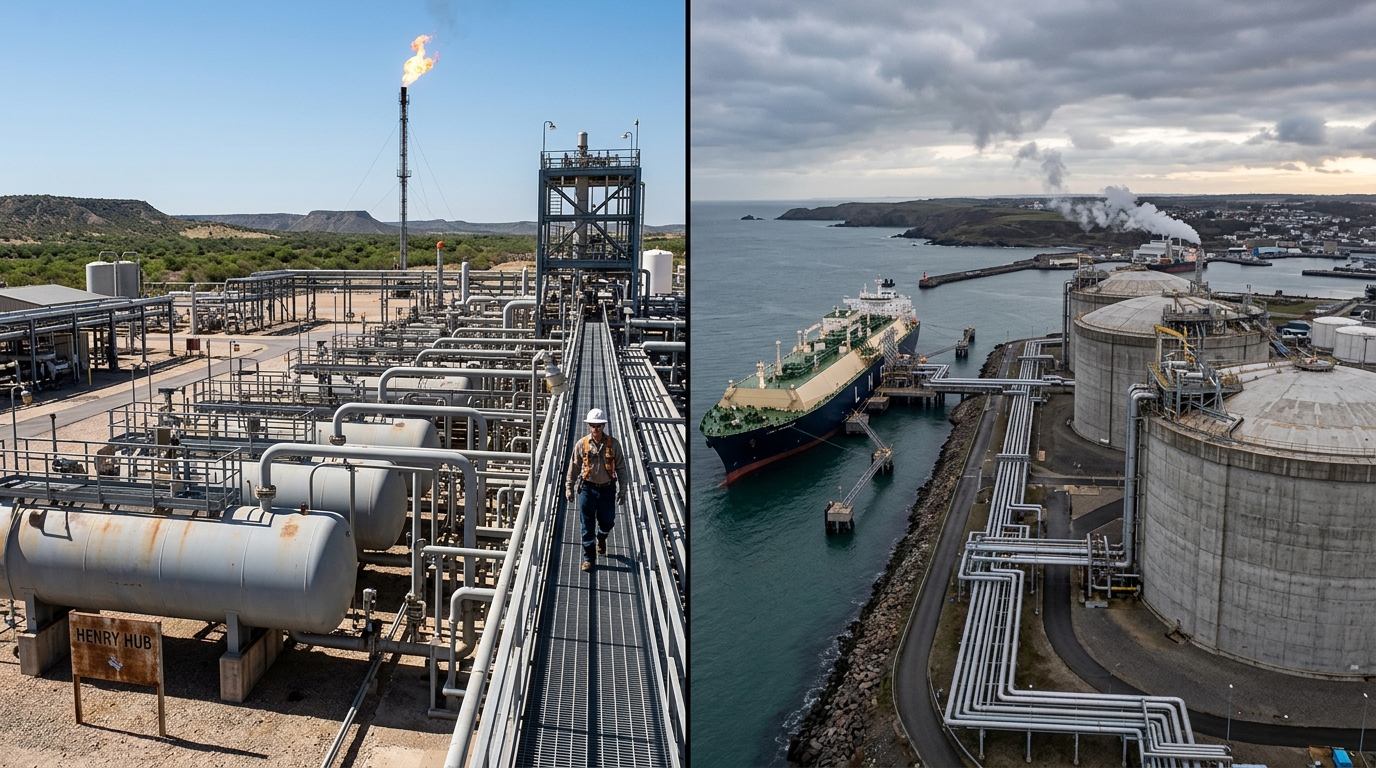
Two natural gas markets, operating on the same planet, have almost nothing to do with each other right now. The EIA’s August Short-Term Energy Outlook forecast Henry Hub averaging $2.87 per MMBtu in Q3 2026, a cut of 50 cents from the prior month, driven by reduced LNG feedgas demand and robust domestic production. Across the Atlantic, European natural gas climbed to around €74.5 per megawatt-hour, touching its highest intraday level since January 2023. That is not a temporary quirk. It is a structural dislocation with real consequences for investors in U.S. gas producers expecting a winter price rally.
Why the Gap Exists
The EIA’s lower price forecast reflects reduced LNG feedgas demand and near record-high natural gas production, which it expects will leave natural gas inventories at their highest level heading into winter since 2016. The agency expects natural gas inventories to be a record 3,985 billion cubic feet at the end of October 2026, 5% above the five-year average. That is the ceiling keeping Henry Hub pinned below $3.
Europe faces the opposite problem. Gas storage levels across the EU have fallen to their lowest level for this time of year since records began about 15 years ago, with facilities about 65% full. Some buyers delayed purchases, expecting shipping risks around the Strait of Hormuz to ease and allow more Qatari LNG to reach the market, but the disruption tied to the U.S.-Iran conflict has kept flows constrained. That bet has not paid off. Around one-fifth of global LNG trade typically passes through the strait, primarily from Qatar.
The reason these two prices can coexist is straightforward: U.S. Henry Hub prices remain insulated by abundant domestic shale production and pipeline infrastructure, while European pricing relies heavily on global spot market dynamics and weather-dependent import demand. The bridge between them is liquefaction capacity, and that bridge has a bottleneck.
The Freeport Factor and What It Means for the Rally Thesis
The EIA cut its Q3 LNG export forecast to 16.5 Bcf/d partly because of maintenance at Freeport LNG, with the result being lower feedgas demand and increased storage in the South Central region. Maintenance at Freeport began July 10 and was expected to continue into late August, affecting 2.0 Bcf/d of nominal export capacity in the short term. That is the single largest identifiable demand outage in the market and its return is the clearest near-term bullish catalyst on the calendar.
The EIA expects Henry Hub to remain below $3.00 per MMBtu until November and average $3.03 per MMBtu over the remaining five months of the year, nearly 50 cents below the prior forecast. Investors banking on a sharp winter rally at Henry Hub should weigh that against the storage picture. The EIA expects inventories at their highest level heading into winter since 2016, and anticipates Henry Hub prices to rise gradually but remain relatively low because inventories are well above the five-year average.
Where the Opportunity Actually Lives
EQT, the largest pure-play Appalachian producer, is the clearest example of how a well-run company navigates exactly this environment. EQT raised its 2026 production forecast and lowered capital spending after stronger performance, while expanding its long-term gas marketing strategy through new power supply and LNG agreements. The company increased its full-year production forecast by approximately 90 Bcfe to 2,375 to 2,450 Bcfe. Crucially, it secured a five-year LNG offtake agreement with a large Asian integrated energy company beginning in 2028, which EQT expects will increase 2028 free cash flow by approximately $45 million at recent strip prices. That is precisely the right positioning: securing future access to global prices while managing today’s domestic glut through hedges.
Every Bcf/d of LNG capacity that comes online places a firmer floor under Henry Hub, and Europe’s structural reliance on U.S. LNG as it continues to reduce its Russian pipeline gas dependence provides a long-term anchor for this demand. The wealth-building case for Appalachian gas producers is not the next heating season. It is the next five years of export capacity additions tightening the domestic market.
The Takeaway
The Atlantic spread tells investors something important: the global gas market is not one market. U.S. producers sitting on record-high expected end-of-October storage are priced like a regional commodity. European buyers trying to rebuild storage before winter are priced like a scarce global one. The companies that will benefit most are those with contracted access to the international price, not just exposure to Henry Hub. Investors holding gas producers purely for a winter domestic rally are looking at the wrong metric.