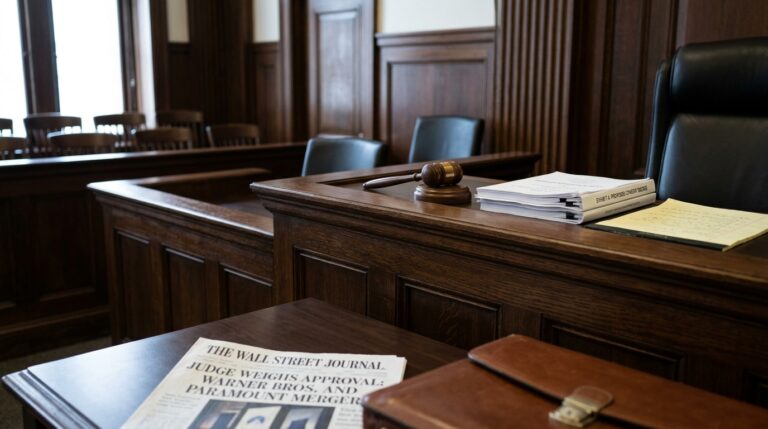
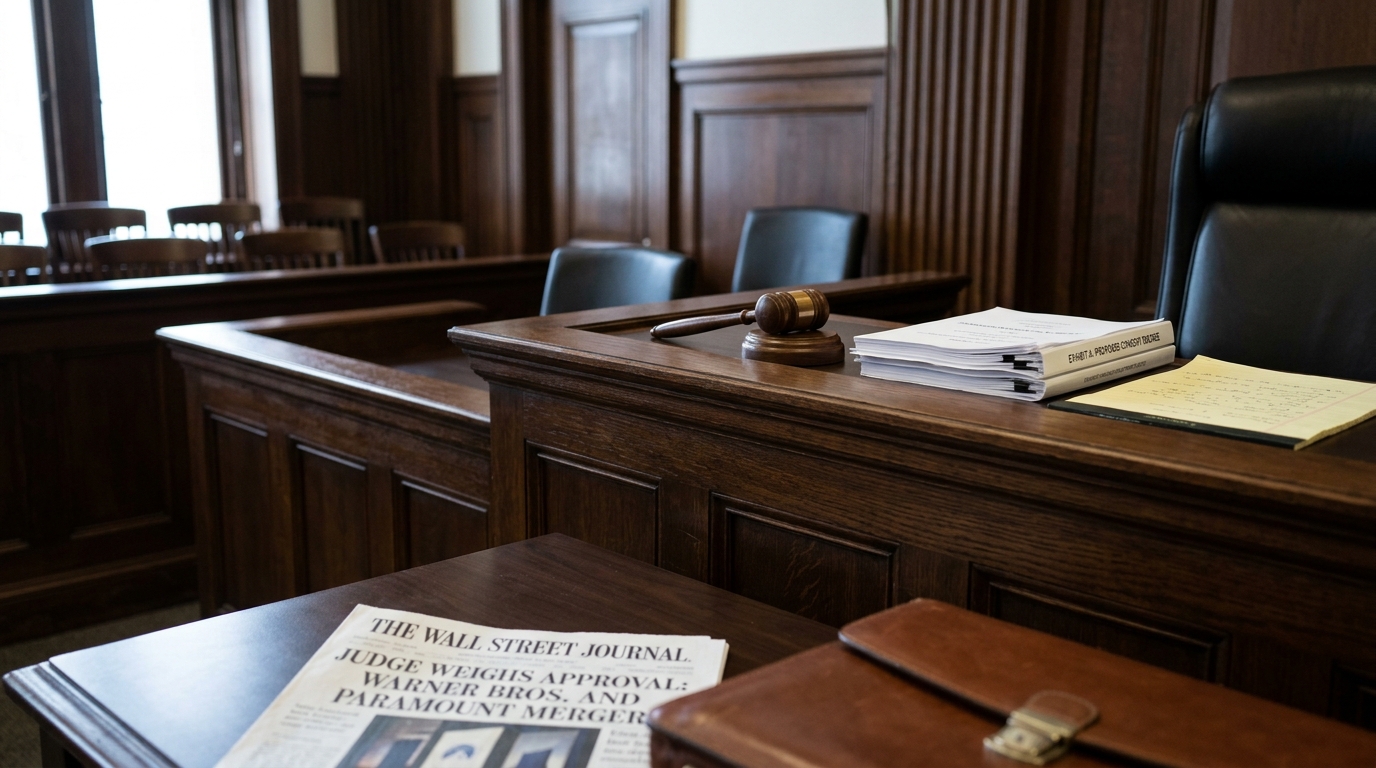
Markets spent last week treating the Paramount-Warner deal as finished. Paramount Skydance settled lawsuits with California and 11 other states, paving the way for what the companies have described as a transformational media merger. The settlement left only the judge’s approval of the proposed consent decree as the last checkbox needed. In a memo to staff, Paramount CEO David Ellison said he expected the Warner Bros. deal to close in around two weeks. That confidence lasted four days.
“The court is not a rubber stamp of your agreement,” Judge Araceli Martínez-Olguín told attorneys for Paramount Skydance and the twelve state attorneys general at the September 24 hearing, then declined to approve the consent decree, deferring a ruling to “in due course.” The judge requested the parties file a response by today, September 28, to Sen. Cory Booker’s request for an independent public-interest review of the proposed consent decree. The court set the deadline for noon Pacific. No ruling timeline has been set.
The financial clock is already running. Paramount will start accruing a ticking fee of roughly $7 million per day payable to WBD stockholders as of October 1, so any delays by the judge in resolving the case will be costly to Paramount. If the judge rejects the settlement altogether, a trial is set for March 2027. The parties have agreed not to close before a merits determination. That means the range of outcomes today spans from “settlement approved this week” to “12-day trial beginning March 2, 2027.”
The Numbers Behind the Spread
Paramount agreed to acquire WBD for $31 per share, valuing WBD at about $81 billion in equity value and about $110 billion in enterprise value. WBD opened today at $28.79 and has traded in a $28.65 to $28.99 range. That leaves a spread of roughly $2.20 against the deal price. A per-share ticking fee of $0.00277778 will be paid upon closing by Paramount to WBD stockholders for every day the merger is not closed past September 30, 2026, up to a maximum of $0.25 per WBD share per 90 calendar day period.
The spread itself is the market’s embedded probability of delay or failure. Some analysts have argued that if the deal falls through, strategic interest in pieces of Warner’s portfolio could resurface, but likely at a materially lower value than the current deal price. Standalone valuation based on DCF analysis is widely debated and can land well below where the stock trades on a deal tape. That creates an asymmetric position: upside capped near $31 plus accrued ticking fees; downside reopens sharply if the settlement is rejected and the trial calendar takes hold.
Options Market Analysis
WBD implied volatility and IV rank move intraday and vary by data vendor and expiry, so traders should treat any single snapshot as indicative rather than definitive. But the framing matters: for a merger target sitting on a known court deadline, “middle-of-the-range” volatility is structurally notable. It means the options market may not be fully pricing the binary outcome embedded in this legal calendar. Premiums can look moderate, not elevated. For traders who want exposure to the resolution event, that argues more for defined-risk debit structures than for premium selling.
The expected move in short-dated WBD contracts around a settlement approval would compress the spread. A rejection or extended delay reopens downside toward a standalone valuation zone well below $28. If implied volatility remains only mid-range into the catalyst, debit structures can be relatively inexpensive versus the event risk.
Structured Trade Framework
Bull case (deal approved within 2 weeks): For traders expecting settlement approval and a close near $31, a defined-risk long call spread in the October expiry, structured around a $29/$31 call spread, would capture the remaining arb spread with capped cost. The width of the spread matches the distance to the deal price. Entry while volatility is moderate can limit premium outlay.
Bear case (judge rejects or indefinitely delays): If the settlement is blocked and the March 2027 trial calendar activates, WBD faces months of overhang. A bear put spread in the $28/$25 range at the November expiry defines risk while expressing downside toward a lower standalone clearing price. Many pre-deal valuation frameworks put fair value meaningfully below the current quote, and that gives context to how far the stock could move if the deal anchor breaks.
Neutral case (delay without rejection): The judge accepts briefs, defers, but does not block. WBD oscillates in the $28–$30.50 range for weeks as ticking fees accumulate. A short iron condor with wings at $26 and $32 collects premium while the deal grinds. If volatility stays only mid-range, this is less compelling than directional structure, but the defined risk is appropriate given calendar uncertainty.
Risk Factors
The delay could end up costing Paramount roughly $630 million per quarter in ticking fees, which creates pressure on Ellison to resolve the situation quickly, potentially accelerating concessions. Conversely, the Block the Merger coalition’s amicus brief argues that California’s AG “publicly criticized the very behavioral remedies that the parties now ask the Court to approve,” which gives the judge substantial grounds to demand additional concessions or reject the consent decree outright. Senator Booker’s intervention introduced an independent public-interest review request the parties never agreed to. That variable is not resolved by today’s response filing.
Action Checklist
- Monitor today’s court filings by noon Pacific for the parties’ response to Booker’s concerns
- Watch for any same-day ruling from Judge Martínez-Olguín; no timeline was provided at the September 24 hearing
- Verify WBD implied volatility and IV rank at market open; a spike above 50 changes the calculus toward spread selling
- If the settlement is approved: assess residual arb spread against time-to-close estimate before entering any call spread
- If approval is deferred past October 1: ticking fee begins accruing; monitor PSKY for additional pressure as daily cost rises
- Keep position sizing defined; this is single-event binary risk, not a trend