October 14, 2026
BMBL’s options now price deal risk, not business risk, and the structure leaves little room for surprise.
The First Options Lesson Most People Skip
Everyone wants to know which options to buy.
Far fewer ask how options actually work.
That one mistake can make the difference between trading with confidence… or learning expensive lessons the hard way.
Read the free Beginner’s Guide before you place your first trade.
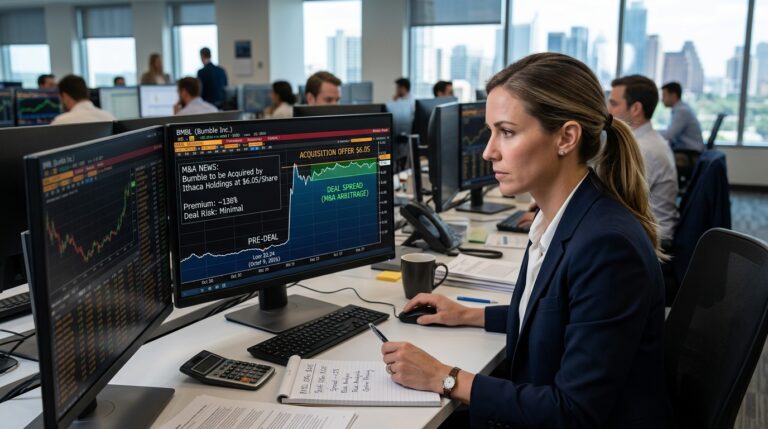
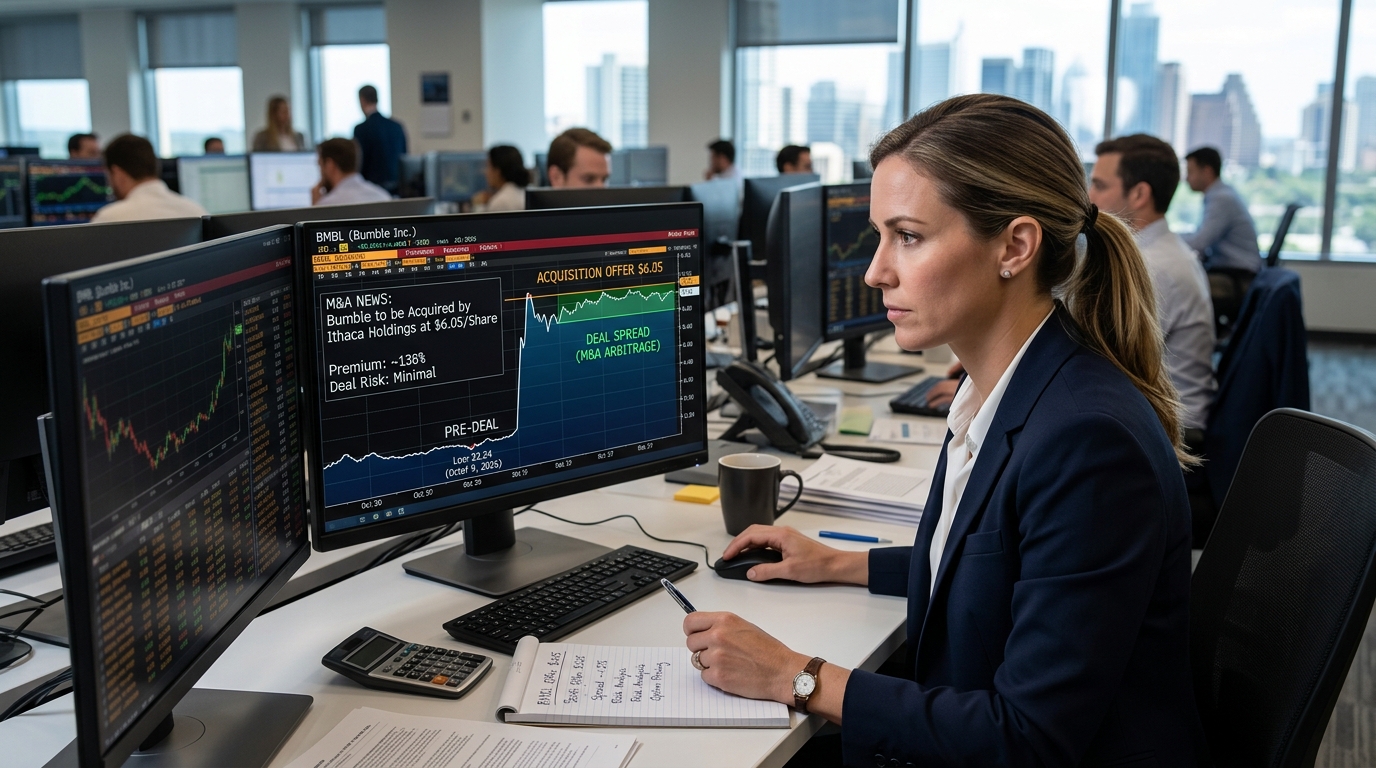
The 138% premium Ithaca Holdings paid to acquire Bumble says less about what Bumble is worth than about what the public market thought it was worth before the bid arrived. Under the terms of the agreement, Bumble common shareholders will receive $6.05 per Class A share, representing a 138% premium to the unaffected closing price on October 9, 2026, and approximately 119% over the 30-day volume-weighted average price. That math is striking not because the premium is generous, but because the baseline was so low. Reuters reported Tuesday that Bumble’s market capitalization had shrunk to about $582 million as of Monday’s close, a far cry from the roughly $14 billion valuation during its 2021 market debut.
One Rule Change Sparked a 681% Surge – Could This Be the Next?
In 1993, one rule change sent retirement money flooding into real estate – a 681% surge. When Bitcoin’s door opened, Larry Benedict traded it for 42% in a day.
Now the biggest door ever is opening – and he’s naming the one ticker in its path, free, here.
The company recently reported second-quarter 2026 revenue of $211 million, down 15.2% year over year, while its paying user base fell 16.4% to approximately 3.2 million. Adjusted EBITDA fell to $72.9 million from $94.6 million a year ago. Trailing twelve-month revenue stands at about $893 million, while trailing twelve-month net loss is roughly $518 million. Ithaca is paying for a business whose paying user base has contracted for nearly two consecutive years. That is not a growth multiple; it is a restructuring bet.
What the Market Is Pricing Now
BMBL stock closed at $5.95 on October 13, up 56.6% on the session after the dating-app operator agreed to be taken private by Ithaca Holdings. The gap between $5.95 and the $6.05 offer represents roughly $0.10, or about 1.7 cents on the dollar. That is the entire remaining return available to equity holders who buy today. This is merger arbitrage math, not trading math. The question is no longer what Bumble is worth. It is whether this deal closes on time, and on terms.
The company said the merger agreement includes no financing contingency, which reduces execution risk. It also said principal stockholders, including affiliates of Blackstone and founder Whitney Wolfe Herd, have already delivered written consent to approve the mergers, eliminating the need for further shareholder action. Closing remains subject to governmental approvals and waiting periods, and either party may terminate if the mergers are not completed by July 12, 2027.
5 Rules. Plain English. Zero Jargon.
You don’t need a psychology degree to stop revenge trading.
You need a few simple rules, set ahead of time, that you follow no matter how the day is going.
That’s what you’ll get in How To Stop Revenge Trading in 5 Steps. Plain English. Rules you can use tomorrow morning.
Options Market: Deal Risk Replaces Business Risk
Investors purchased 22,861 call options on October 13, an increase of 1,682% compared to the average daily volume of 1,283 call options. That surge reflects positioning around the deal announcement, not any re-rating of Bumble’s fundamentals. Once a stock collapses to a single cash outcome, implied volatility behaves differently. Near-term IV compresses toward the annualized cost of carry on a $0.10 spread. Longer-dated contracts price the tail risk of deal failure or delay.
The key variables for options traders are the deal timeline and the termination structure. Under the merger agreement, a $102 million parent termination fee applies in specified circumstances, and Bumble said that amount must be deposited into an escrow account by October 19, 2026. That escrow deadline, just five days out, is a hard signal from Ithaca of commitment. Bumble also disclosed it plans to file its quarterly report by November 9, 2026, but will not issue a third-quarter earnings release or hold a results call. Without an earnings event to trade, the vol surface anchors almost entirely to regulatory timeline estimates.
Structured Trade Framework
Bull case (deal closes without delay): Long stock near $5.95 captures the $0.10 spread. Annualized return depends entirely on when regulators clear the transaction. For traders expecting swift approval, a cash-secured position in the stock is cleaner than options given the compressed premium available in calls struck at or above $6.05.
Bear case (deal fails or extends): If the transaction breaks, BMBL likely reverts toward pre-deal levels. The company has no earnings catalyst until a possible November 9 10-Q filing, no conference call, and a business in structural decline. A defined-risk long put position, struck at $5.00 or below, captures that tail without unlimited downside exposure to a deal that carries a $102 million break fee as a deterrent.
Neutral case (deal closes late, spread widens temporarily): If regulatory review extends into Q1 2027, the spread could widen to $0.20 or beyond as carry costs accumulate. A defined-risk calendar spread, buying time while selling near-dated premium against it, captures spread widening without a directional view on deal survival.
Elon Musk’s Insane Projection: 7,692,207%
Where should you invest $100 right now?
Elon Musk just invented and patented this new AI technology…
And he’s predicting it will launch a NEW industry that will grow more than 7 million percent in the coming years.
Even if he’s only 10% right, that would still be enough to grow $100 into more than $700,000.
Click here to see the details on what Elon Musk called “an infinite money glitch.”
Risk Analysis and Forward Outlook
The sector backdrop matters for interpreting Ithaca’s rationale. Match Group has recently traded around a $9.5 billion market capitalization, while Grindr has recently traded around $2.7 billion. Both trade publicly at multiples far above what Ithaca is paying for Bumble, which means the buyer either sees a private-market restructuring path unavailable under quarterly earnings pressure, or acquired the brand at distressed-asset pricing. Neither conclusion is bullish for the sector’s near-term public valuations.
For risk arbitrageurs, the remaining edge in BMBL is thin. The financing is committed, the vote is done, and the break fee creates a credible deterrent against walk-away. The spread exists because deals always carry tail risk, not because this one is structurally impaired.
Action Checklist
- Confirm Ithaca’s $102 million escrow deposit by October 19, 2026. Non-deposit would be the first material deal-risk signal.
- Monitor for any antitrust second request from DOJ or FTC. The dating-app sector has limited overlap, but a review extension would widen the spread.
- Track Bumble’s November 9, 2026 Form 10-Q filing for any material adverse change language that could trigger deal conditions.
- If holding for the spread: size the position relative to the July 12, 2027 outside date, not an assumed near-term close.
- For defined-risk bearish exposure: a put spread struck well below $5.00 captures deal-failure risk without fighting the $102 million termination deterrent.