October 21, 2026
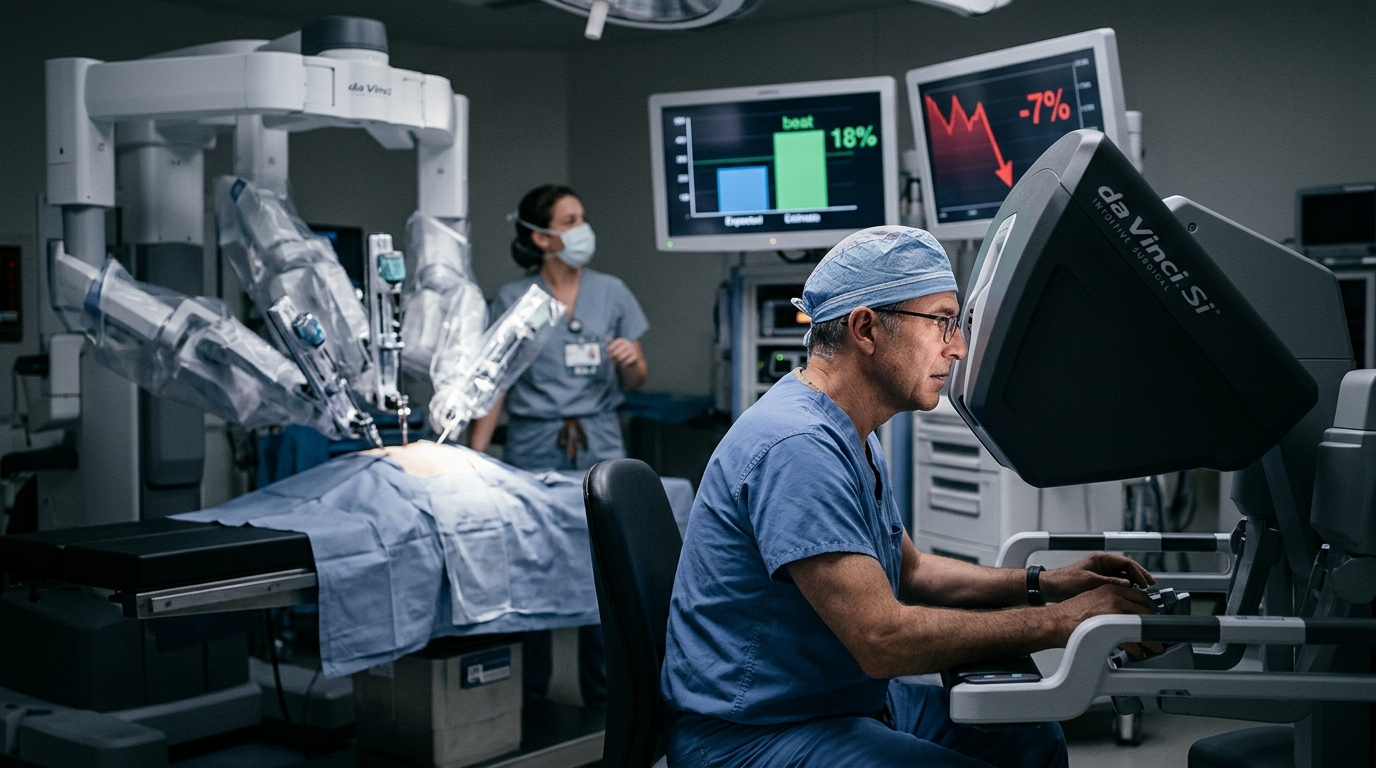
Bonus Content: Intuitive Surgical Beat by 18%. The Stock Fell Anyway.
Silver and gold are obliterating all previous profit records with next-level gains now on-deck for well-timed investors.
We’re talking early-stage, small-cap discovery stories that are only just beginning to unfold.
The early-stage opportunity is taking shape across a historic North American silver-gold district that helped build early fortunes but was never explored as a unified system.
For generations, the district produced high-grade metals at surface.
Yet, the deeper story was never told – not because the metals weren’t there but because the land package was highly fragmented and never explored as a single system.
That has now changed.
For the first time ever, this exceptionally well-run small-cap explorer has brought the entire district under one roof – enabling modern geology and drilling to finally test the system properly from surface to depth across kilometers of previously untouched mineralization.
And the timing couldn’t be better.
Phase-2 drilling is accelerating as you read this… setting up a near-term flow of potential needle-moving results as the discovery picture sharpens.
And that’s not all.
Add in a second nearby district-scale silver-gold asset… and the exploration runway expands even further for this emerging small-cap.
We’ve put together a FREE online report with all the details, including:
✓ A newly unified district-scale silver-gold system in North America
✓ What the first drill results are already confirming
✓ Which targets will see drilling next
✓ How a second district-scale asset expands the discovery upside
✓ Key 2026-27 catalysts as drilling intensifies
Inside, you’ll also find our exclusive, in-depth interview with the company’s president & CEO who brings a true firsthand look at where this discovery is headed next and why the timing is so critical.
Click here to access our FREE online report and see why this Sub-US$1 silver-gold stock is setting up to be one of the most compelling early-stage opportunities of 2026-27.
Intuitive Surgical Beat by 18%. The Stock Fell Anyway.
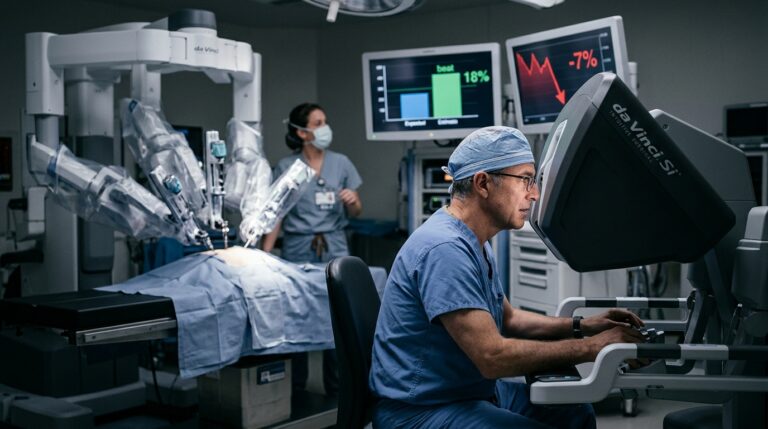
Markets don’t need a good quarter. They need confirmation that the next several quarters will be at least as good. Intuitive Surgical handed investors one of the cleanest earnings beats in the medical-device space and still watched the stock drop roughly 7% after hours. The reason is not complicated: the quarter traded fine; the guidance line did not.
Intuitive reported Q3 2026 non-GAAP EPS of $3.00. Wall Street consensus was closer to about $2.65, putting the beat around the low teens, not 18%. Revenue rose 22% to just over $3.0 billion (about $3.05 billion), driven by a 15% increase in total procedures and a 28% rise in da Vinci system placements. On almost any other day, those numbers buy the bulls a rally.
Beating consensus by a wide margin and still selling off is not unique to medical devices. SanDisk’s quarter showed how a dominant earnings beat can still trigger a sharp selloff when the forward story disappoints.
Intuitive narrowed its full-year forecast for da Vinci procedure growth to 14%-15%, compared with 13.5%-15.5% previously, with the midpoint remaining unchanged at 14.5% but the upper end moving lower. That compression in the ceiling is what the market sold. The volume outlook did not improve: the company kept its 2026 da Vinci procedure growth forecast at 14% to 15% and said results should land near the midpoint, which after a quarter of roughly 14% growth signaled no acceleration.
What the Numbers Actually Show
Da Vinci procedures rose 14%, including 10% growth in the U.S. and 20% outside the U.S., while Ion procedures increased 31%. U.S. procedure growth at 10% was the weakest domestic figure since the pandemic, a data point analysts pressed management on directly during the call. Non-GAAP operating margin reached 42% of revenue, or 41% excluding a one-time pre-tax tariff refund of $28 million.
Then came the structural concession. The company announced pricing changes that it said could reduce da Vinci instrument and accessory revenue per procedure by 3% to 5% over time. Those consumables are the core of the recurring revenue model, so lower prices cut into the highest-margin part of each procedure. Management framed the move as a long-term adoption driver. The options market and the after-hours sellers framed it as a margin overhang.
Why the Valuation Made the Guidance Bite Harder
The stock had entered the report with a trailing price-to-earnings multiple near 50, below its five-year median near 70, which left less room for a muted outlook. This is the compression problem at elevated multiples: even a relative discount requires forward growth to keep the valuation coherent. A narrowed ceiling on procedure growth, paired with a 3%-5% cut to per-procedure revenue, introduces doubt about whether the current earnings trajectory holds into 2027.
Management expects lower prices to expand adoption over time, but described a phased rollout that is country-by-country, with the full pricing impact not expected until late 2027. That timeline puts the cost of the pricing concession squarely in the next four to six quarters with no visible revenue offset from volume elasticity yet.
Options Market: What Was Priced and What Happened
Heading into the report, the options market priced an expected move of roughly plus or minus 7.94% for ISRG. The after-hours decline of roughly 7% landed inside that range, meaning options sellers who structured defined-risk credit spreads around the event collected premium without being run over. Claims about ISRG implied volatility at 38% and an IV rank of 63% could not be verified from primary company disclosures, and vary materially by vendor and methodology, so they are removed here.
Post-earnings, IV crush will compress those premiums sharply as the event uncertainty resolves. The directional question for options traders shifts from “how big will the move be?” to “does the guidance overhang keep pressure on the stock into Q4?”
That dynamic — where the implied move is priced correctly but the direction still punishes traders — is not unique to ISRG. Barrick’s earnings straddle implied a 7.5% move and the stock delivered just 2.5%, leaving premium sellers and buyers alike to recalibrate.
Structured Trade Framework
Bull case: If you believe the 14%-15% procedure growth range holds and instrument-pricing elasticity develops faster than management framed, a defined-risk call spread targeting recovery toward the pre-report range over 60-90 days captures directional upside while capping the cost of being early. Wait for IV to fully crush before initiating.
Bear case: For traders expecting U.S. procedure growth to remain at or below 10% in Q4 and the pricing concession to weigh on 2027 consensus EPS, a defined-risk put spread with a December or January expiry positions for a continued grind lower. The $450 million antitrust settlement charge adds a GAAP noise layer that complicates any near-term institutional re-rating.
Neutral case: With the expected move now resolved and IV contracting, a short iron condor in the 30-45 day window exploits the post-event volatility collapse. Size for defined risk; ISRG at this valuation can gap on any procedural data update.
Risk Analysis and Forward Outlook
China tender volumes, competitive intensity, and policy-driven price reductions remain swing factors. Freight and semiconductor-memory input costs have also been cited by management as gross-margin pressures, and the instrument-pricing rollout may create customer-ordering volatility while expected elasticity may take time to develop.
The core business is not broken. Revenue grew 22% to just over $3.0 billion (about $3.05 billion), with 84% recurring revenue, and non-GAAP EPS grew 25% to $3.00 per share. That is a compounding machine. The question the market is answering right now is whether it will pay about 50x for a machine whose growth ceiling just got trimmed and whose per-procedure revenue is about to be deliberately lowered. That question does not resolve in one quarter.
Action Checklist
- Verify IV has fully crushed before sizing any long-premium position in ISRG.
- Track Q4 U.S. procedure growth as the primary indicator: a second consecutive quarter below 12% would confirm deceleration, not a temporary lull.
- Monitor the instrument-pricing rollout country-by-country; any faster-than-expected volume elasticity is the bull catalyst that is not in consensus.
- Watch the $450 million antitrust settlement for court approval: a resolution removes a GAAP overhang that distorts net income comparisons.
- Frame all positions with defined risk. A stock at about 50x earnings with a margin concession in motion can move sharply on any procedural data miss.