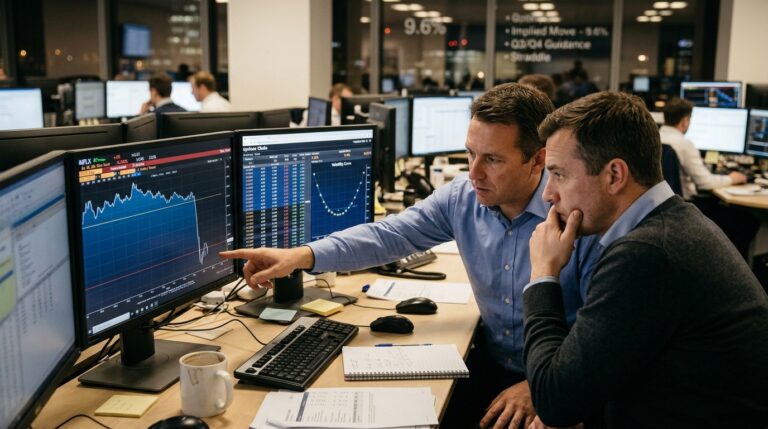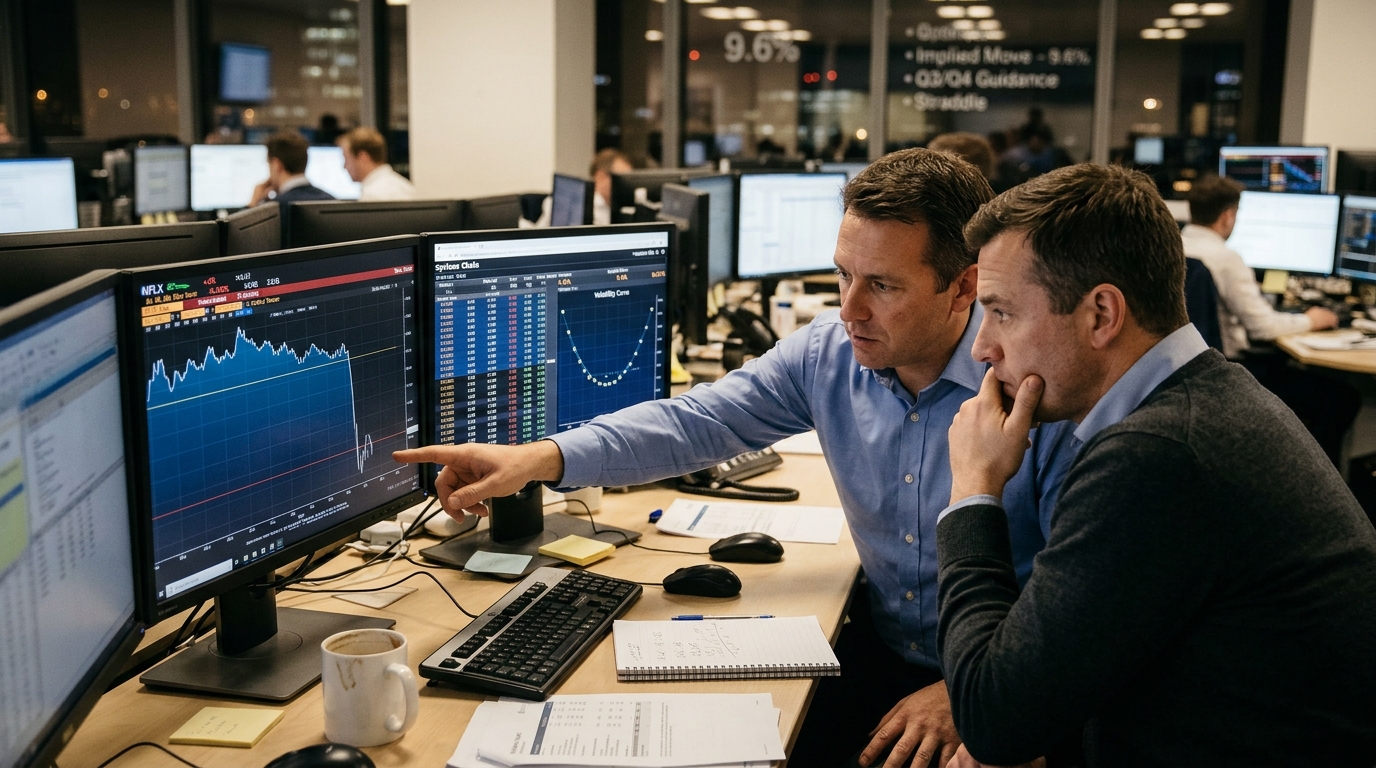
The options market priced a 9.6% swing in NFLX heading into Tuesday’s close. The at-the-money straddle implied a move of roughly plus or minus 9.9% for the October 20 earnings event. The actual after-hours drop landed closer to 6%, so you might call that a win for the sellers of premium. Except that framing misses the larger pattern entirely.
This is not about whether the move exceeded the expected range. It’s about which direction NFLX systematically breaks through its options-implied move. In Q2 2026, Netflix posted roughly a 1.3% EPS beat, and shares still fell more than 7% after hours. Tuesday’s report repeated the structure almost exactly: beat the quarter, disappoint on guidance, sell the stock. The options market saw uncertainty ahead; it did not see the asymmetry.
What the Numbers Actually Said
Netflix reported EPS of $0.87 versus the $0.82 consensus estimate, on revenue of $12.87 billion. Q3 operating income totaled about $4.46 billion, up 37% year over year, with operating margin of 34.6% versus 28.2% in Q3 2025. On the surface, strong.
The problem was everything after that line. Netflix forecast Q4 results below Wall Street expectations and lowered its 2026 advertising revenue outlook. Q4 guidance came in at revenue near $13.44 billion versus about $13.5 billion expected, Q4 EPS of $0.67 versus $0.73, and operating margin of 26.0% versus roughly the high-27% range. The company also cut its full-year free cash flow target to about $12.0 billion from $12.5 billion.
Netflix lowered its 2026 advertising revenue outlook to approximately $2.7 billion from a previous forecast of roughly $3.0 billion, citing a slower-than-expected rollout of some advertising capabilities. That reduction hit a stock already carrying structural weight: Netflix has posted monthly subscriber losses in the US throughout 2026, with no net additions reported for any month up to September, according to Antenna data reported by The Business Times.
Netflix is not the only streamer whose ad-tier economics are under scrutiny. Disney and Roku are chasing the same ad dollar, and the gap in monetization yield between them is larger than most investors assume.
Context and Strategic Interpretation
The 11.8% revenue growth rate marked the company’s slowest increase in three years. The results arrive on the heels of the company’s biggest layoffs in years, as well as the announced departure of chief content officer Bela Bajaria. Bajaria is being replaced by former Disney executive Peter Rice. In the company churn, markets don’t need a company to be perfect. They need guidance to clear the bar. This quarter, Netflix cleared none of the forward bars that matter: not Q4 revenue, not Q4 EPS, not full-year free cash flow, and not advertising.
Options Market Analysis
Pre-earnings, options implied a swing of about 9.6% into the October 20 report, based on the at-the-money straddle. By earnings day, that implied move was roughly 9.9%. Post-earnings, with the actual move settling near 6%, implied volatility should compress sharply.
The put-call structure was already skewed bearish before the report. Traders who bought downside protection ahead of the Q2 repeat pattern had logic on their side, even if the magnitude came in below the implied range.
Structured Trade Framework
Bull case: If you believe the advertising slowdown is a product-rollout delay rather than a structural ceiling, and that new content chief Peter Rice stabilizes US engagement, a defined-risk structure such as a January bull put spread at the $60/$55 strikes captures premium from elevated IV while limiting downside exposure to a known dollar amount. The post-crush IV environment makes this more expensive than it looks; size accordingly.
Bear case: For traders expecting continued US subscriber erosion and a Q4 that again misses EPS by a wider margin than guided, a bear call spread in the $72/$78 range captures the post-crush premium without requiring a directional gap lower from current levels. The IV reset makes credit spreads the preferred vehicle over outright puts.
Neutral case: With IV now meaningfully lower post-earnings, the environment can favor premium collection over directional bets. A short strangle around the $60/$75 range in November expiration captures decay while IV mean-reverts, with defined risk achieved by adding wings to convert to an iron condor.
Risk Factors
The primary risk to any bull structure is a Q4 pre-announcement or further ad-revenue revision before January expiration. Netflix guided Q4 operating margin at 26.0%, and the company noted this includes roughly 120 basis points of negative impact tied to the headcount reductions. If those costs exceed guidance, the margin miss compounds the revenue shortfall. For bear structures, the risk is execution: if Peter Rice moves fast and a major US content hit lands in Q4, sentiment can reverse sharply in a low-float, high-beta name.
Action Checklist
- Confirm IV rank post-earnings before sizing any new position; credit spreads are favored when IV rank is below 40%
- Q4 revenue guide of $13.44 billion is the line to watch; any revision lower before January expiration re-opens directional risk
- Monitor Antenna monthly US subscriber data; zero net additions through September is the baseline, and any positive month changes the bull thesis materially
- Track advertising revenue progress toward the revised $2.7 billion target; a second downward revision would likely accelerate the bear case
- Use defined-risk structures only given the binary nature of guidance risk in this name