Back in the 1860s, settlers from France, Italy, and Germany built grand Parisian boulevards…
…neoclassical facades…
… and cobblestone Bavarian villages halfway across the globe.
Then the rest of the world largely forgot about them.
Today, expats are uncovering a European standard of living…
… Lakefront rental homes for $721 a month…
… private chauffeur service…
… and elite healthcare – completely free from tourist crowds and inflated European price tags.
XIFR Hit a 52-Week Low After Earnings. The Free Cash Flow Math Is More Complicated.
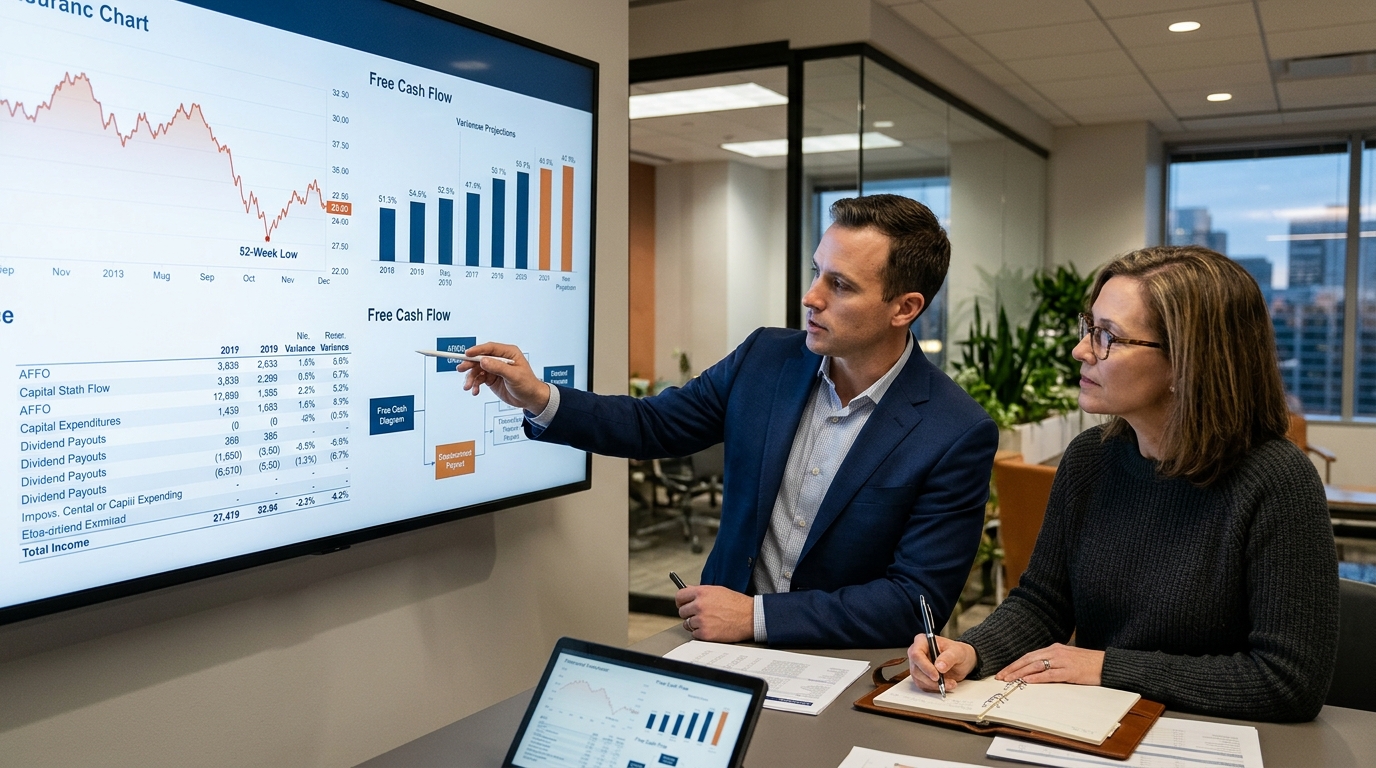
Markets don’t need a great quarter. They only need a reason to sell. XPLR Infrastructure (NYSE: XIFR), the clean-energy partnership formerly known as NextEra Energy Partners, gave them one on November 3 when it trimmed full-year guidance and slid to a fresh 52-week low of $8.03 intraday. Five trading sessions later, the stock sits near $7.77, down roughly 17% over the past 52 weeks and off more than 82% from its 2021 peak.
The selloff is not irrational. But it is not the whole story either.
What Q3 Actually Printed
Third-quarter 2026 adjusted EBITDA came in at $471 million, with free cash flow before growth (FCFBG) of $164 million. That FCFBG figure was up roughly $24 million year over year from existing projects, driven by more normalized wind resources versus a weak prior-year comparison. The problem: management softened its 2026 FCFBG outlook to come in at or near the low end of the prior $600 million to $700 million range, blaming wind underperformance in the western region and higher financing costs tied to the $1.75 billion of senior unsecured notes issued in March 2025. EPS of $0.54 beat the consensus estimate of a $0.14 loss by $0.68, a wide positive gap the market effectively ignored.
The Strategic Interpretation
Guidance revisions almost always outweigh EPS beats in utility-like infrastructure names, and that dynamic held here. The more durable concern is structural. XIFR carries convertible equity portfolio financing (CEPF) buyout obligations that the company has described as roughly $2.5 billion in the aggregate for the remaining structures, with annual intervals from 2028 through 2034. Management’s plan to service those obligations without issuing equity depends entirely on the FCFBG stream staying intact. At $656 million in cash and cash equivalents and a $1.25 billion revolving credit facility as of September 30, liquidity is not an immediate crisis. But a guidance cut in the same quarter management called the business’s cash flows “durable” tightens the margin for error.
Financing costs are not easing. The 30-year Treasury yield near its highest level since 2007 raises the cost of every refinancing XIFR must execute through 2034.
Analyst consensus sits at a “Hold” with a $12.17 average price target, implying roughly 57% upside from current levels. Five analysts cover the name; the range runs from $10 to $17. The gap between where the stock trades and where analysts think it belongs is not noise. It is the CEPF discount, written in price.
Options Market Analysis
XIFR options volume remains thin relative to peers, limiting clean IV rank reads. The beta of 0.90 understates event-driven volatility, as the November 3 earnings session demonstrated with a gap to new 52-week lows on above-average volume. For traders watching implied volatility, the near-term term structure likely embeds residual post-earnings skew, with puts holding elevated premium relative to calls given the guidance cut. Any defined-risk structure should account for a potential $7.20 floor test, the 52-week low reached on November 6.
Structured Trade Framework
Bull case: If you believe management can hold FCFBG at $600 million or better through 2026 while continuing CEPF buyouts without new equity, the stock is priced for distress that may not materialize. A defined-risk long exposure via a bull call spread targeting the $10 to $12 range captures analyst consensus without unlimited downside.
Bear case: For traders expecting FCFBG to erode further as financing costs compound, defined-risk put spreads in the $7 to $9 range express that view efficiently. The 52-week low is the natural anchor.
Neutral case: With the 52-week range now spanning $7.20 to $13.25, a short strangle around current levels collects elevated premium if the stock consolidates post-earnings, though CEPF headline risk limits the comfort of that position.
Risk Analysis
The core risks are sequential: weaker wind resources persist and further pressure FCFBG; CEPF counterparties exercise buyout options at the worst moment; refinancing costs on the 2025 senior unsecured notes continue to compound against the free cash flow line. The asset base itself, contracted wind and solar with largely investment-grade offtakers, is not in dispute. The question is always who captures the value embedded in those contracts, and right now a significant fraction flows to CEPF investors, not to common unitholders.
The contrast with regulated utilities sharpens the XIFR risk picture. Regulated peers like Duke are expanding rate base through data-center load growth, giving them a cash flow floor that unregulated clean-energy partnerships lack.
Forward Outlook
Management guided 2028 FCFBG “in line with 2027,” suggesting the market should not expect a step-change recovery until CEPF obligations thin materially. That timeline stretches to at least 2030 before the two remaining CEPF structures begin to resolve. Patient capital with a multi-year horizon can underwrite that wait. Short-duration income investors cannot.
Action Checklist
- Monitor FCFBG trajectory: management now expects 2026 FCFBG to come in at or near the low end of the prior $600 million to $700 million range; sustained performance below $600 million reopens the November 6 $7.20 52-week low as support.
- Track CEPF buyout timing: the remaining structures have annual intervals from 2028 through 2034.
- Watch NEE’s earnings for any XIFR-related guidance language; the parent’s posture signals CEPF counterparty flexibility.
- Size defined-risk. The stock has moved 15% or more on a single session multiple times in 2025 and 2026. Position sizing must reflect that range, not the 0.90 beta headline.