Dear Reader,
Todd Phillips has spent 30 years studying safe-money income.
And he says there’s one question that separates real retirement income from everything pretending to be income:
Can it promise the same income – to the dollar – every year for life?
Dividend stocks can’t.
Any board can cut their company’s payout.
REITs can’t.
Tenants leave. Rates move. Property values change.
Covered calls can’t.
The income depends on the market.
Even CDs can’t.
They mature… reset… and force investors back to the window hoping the next rate isn’t worse.
That’s why Todd came charging into my office three weeks ago.
He had found what we now call the 10.3% War Bond.
Not because it trades on Wall Street.
Not because it rises and falls with the market.
But because it’s designed to do what income investors want most:
A locked-in income stream that stays the same…
Year after year…
For LIFE.
Todd says the current 10.3% income rate for this war bond is in his opinion among the highest available anywhere.
But he does not believe this window will stay open long.
Click here now to see the 10.3% War Bond Blueprint.
To the future,
Roger Michalski
Publisher, Eagle Financial Publications
Trade Desk Reports Tonight. The Bar Is Already on the Floor.
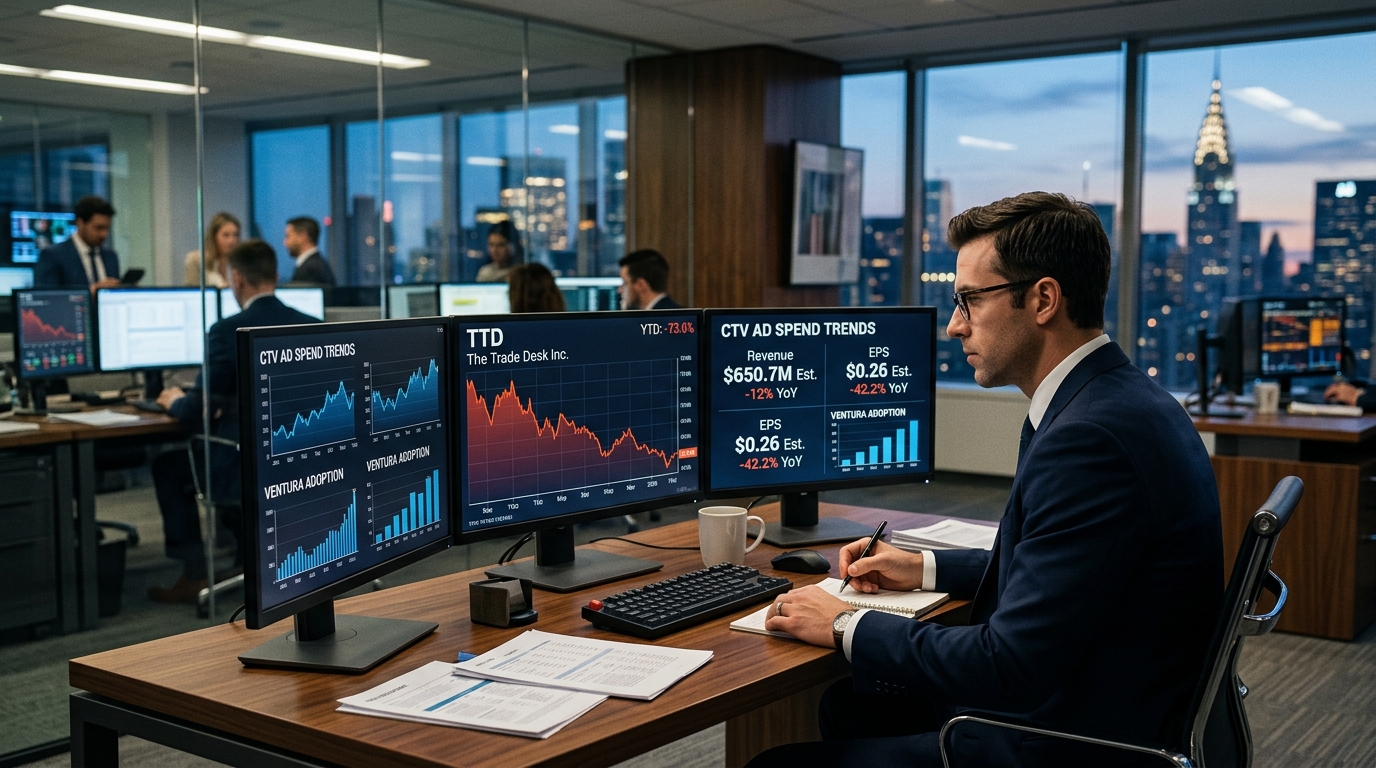
This is not a growth story anymore. Right now it is a stabilization story, and tonight’s Q3 2026 report from The Trade Desk is where that argument either gains ground or collapses.
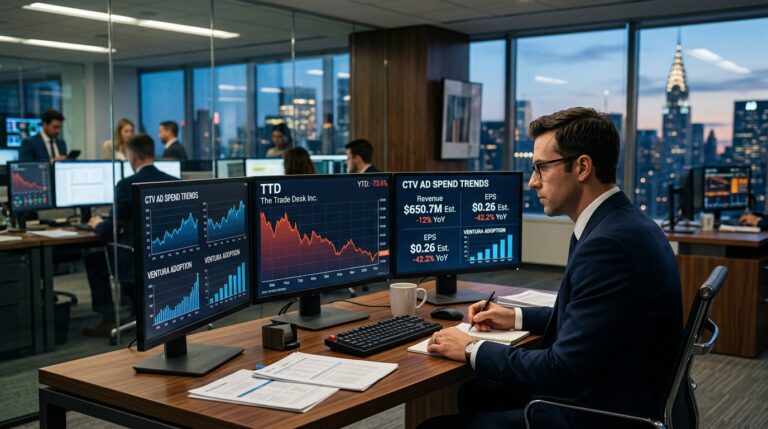
The Zacks consensus for Q3 revenue sits at $650.7 million, down 12% from the prior-year period, while EPS is pegged at $0.26, a 42.2% year-over-year decline. Management set the floor itself: guidance issued in August called for revenues of at least $650 million and adjusted EBITDA of approximately $160 million. Clearing that minimum is table stakes. What matters after-hours is the fourth-quarter guide and any signal on advertiser budget timing.
How the Decline Happened
The Trade Desk reported slower revenue growth in each of the past four quarters, and in the August 6 report, growth fell short of management’s own expectations. Q2 2026 revenue of $715.06 million came in below analyst forecasts, up only 3% year over year, and a wave of analyst downgrades followed, including Citi moving to Sell. Management pointed to autos and CPG, which together represent roughly 25% of Trade Desk’s business, noting that tariffs and oil prices set both categories back and that some brands temporarily reduced budgets while reworking their plans.
Over the past year, TTD shares have lost 73.1%, compared with a roughly 3% decline for the broader Zacks Internet Services industry. Magnite shares, by contrast, are up 57% year to date, which suggests the pressure on TTD reflects company-specific factors rather than a sector-wide ad pullback.
What CTV and Ventura Need to Prove
Trade Desk’s CTV platform is positioned to capture premium streaming advertising budgets, and video including CTV accounted for roughly half of its business in Q4 2025. In February 2026, the company expanded its CTV push with the launch of the Ventura Ecosystem, an industry-wide collaboration built to advance transparency, fairness, and revenue efficiency in streaming. CEO Jeff Green also introduced Kokai, described as an AI-fueled buying platform, as the cornerstone of the company’s innovation approach. Those bets need quantifiable traction tonight. Broad platform language will not move the stock.
Free cash flow in the June quarter was higher than a year earlier, and most of the company’s top 100 accounts were growing double digits as of the August earnings call, which is the internal signal the bulls are pointing to. The question is whether that pocket of strength is expanding or shrinking.
Options Market Analysis
Pre-earnings options volume is running 2.5x normal, with calls leading puts 3-to-2. Implied volatility prices in a move of roughly 11.8%, or approximately $7.10 per share. The median realized move over the past eight quarters is 9.0%. The options market is pricing a premium above historical norms, which means volatility sellers are accepting elevated risk and buyers are paying for it.
Structured Trade Framework
Bull case: If you believe management’s August guidance floor holds and Q4 guidance shows sequential improvement in ad spend from CPG and auto categories, a defined-risk call spread expiring in December captures the re-rating without unlimited downside. The stock at roughly $12.92 trading below the consensus analyst target of $13.53 leaves minimal upside buffer; size accordingly.
Bear case: For traders expecting Q4 guidance to disappoint again, a put spread struck below the implied move range, financed by selling a further out-of-the-money put, limits the cost of conviction in a stock whose execution credibility is already compromised.
Neutral case: With the implied move at 11.8% above the 9.0% historical median, an iron condor structured outside that range collects premium if the reaction stays inside the options-priced band. The 2.6x elevated volume environment argues for defined wings rather than naked short volatility.
Risk Analysis
The core risk is not the revenue number. It is guidance language. Coverage centers on whether revenue clears the $650 million minimum, whether Q4 guidance signals stabilization, and whether cost cuts can offset weaker spending from existing customers. A beat on Q3 revenue paired with a soft Q4 outlook will likely repeat the August pattern: initial relief, then a gap lower. The bear thesis has historical precedent. Over the trailing four quarters, TTD beat the consensus EPS estimate once, matched it once, and missed twice, for an average negative earnings surprise of 6.83%.
Action Checklist
- Watch the Q3 revenue print against the $650 million floor. Any shortfall accelerates the bear case immediately.
- Focus on Q4 revenue guidance language, not Q3. This is where the stock is priced.
- Monitor CTV-specific commentary and Ventura partnership adoption metrics. Vague platform language is a red flag.
- Note whether CPG and auto budget commentary shifts from “pausing” to “returning.” That is the catalyst for a durable re-rating.
- Size positions to withstand the full implied move of 11.8% in either direction. Defined-risk structures are the appropriate vehicle given TTD’s history of delivering outsized post-earnings swings.