Skip to content
Options Trading Report

Options Trading Report

Primary Menu
  • Home
  • Business
  • Economy
  • Top News
  • Newsletters
  • Home
  • 2026
  • September
  • Chipotle’s Beef Bill Is What Investors Actually Need to Price In
  • Top News

Chipotle’s Beef Bill Is What Investors Actually Need to Price In

The cyclospora cloud has lifted. What remains is a margin squeeze that a 1-2% menu price increase may not fully fix.
Editor September 12, 2026 3 minutes read
aae80687-f970-41a2-8d22-fffd485210d9

On September 11, the CDC declared the multistate cyclospora outbreak linked to iceberg lettuce over. Restaurant stocks, Chipotle included, bounced on the news. That relief is real. The food-safety overhang that had rattled dining rooms since July is gone. But for CMG shareholders, clearing one headwind simply puts the underlying cost problem in sharper focus.

During the Q2 earnings call, CFO Adam Rymer noted a softening of roughly 200 basis points in traffic trends tied to the cyclospora issue affecting the industry. Now that drag is fading. What stays is beef.

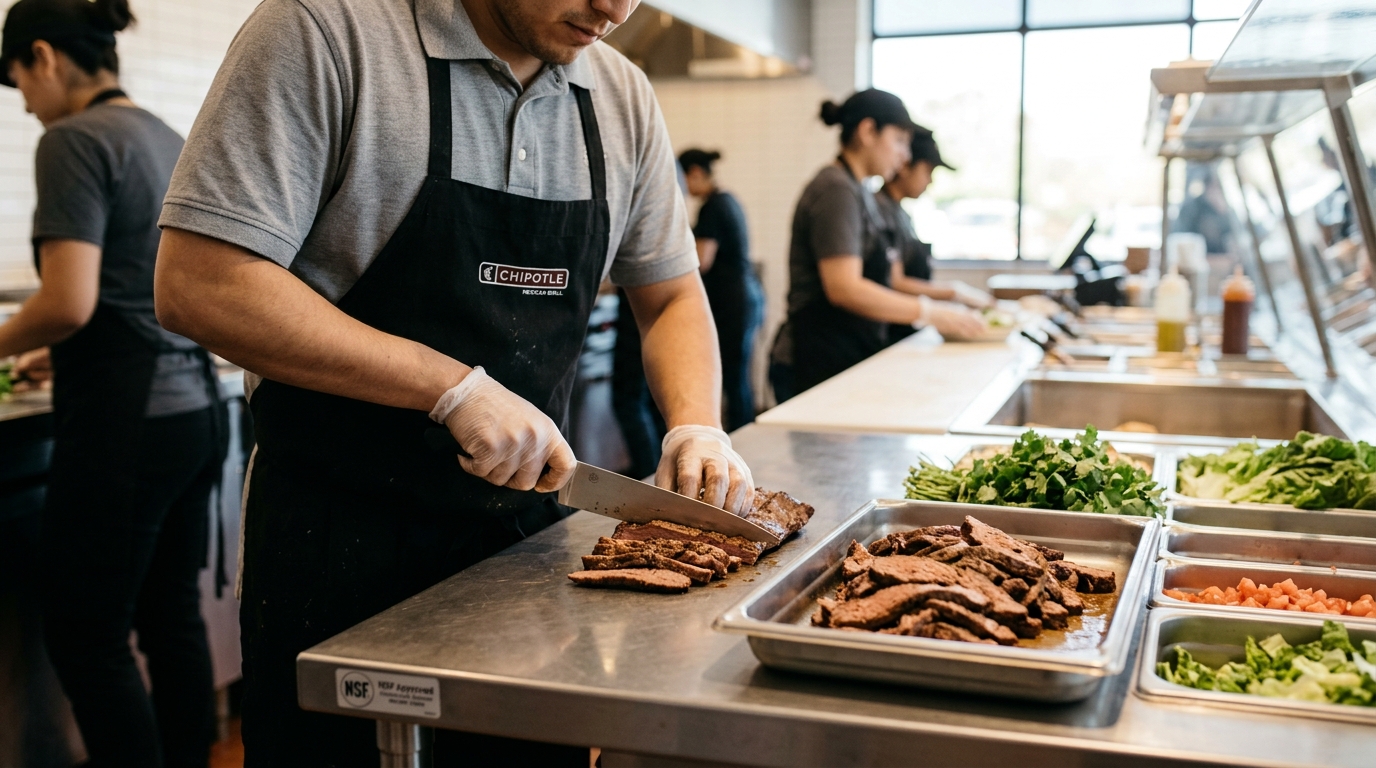
Food, beverage, and packaging costs in Q2 2026 hit 29.7% of total revenue, up from 28.9% a year earlier, driven primarily by inflation in beef and freight. Restaurant-level margin fell 220 basis points year-over-year to 25.2%, weighed down by higher labor, marketing, and other operating costs. Those are not small moves for a company whose premium valuation rests on expanding margins, not compressing them.

Management’s answer is measured: pass some of it on. CFO Adam Rymer told investors that margins in 2026 would be under pressure and that the company planned 1% to 2% menu price increases, which is modest relative to where the company pegged industry pricing. That increment is modest relative to the cost gap. For Q3, management projected inflation running near 3% against pricing in the mid-2% range, a combination that could keep pressing margins.

The confidence behind those price increases comes from a deliberate customer segmentation. CEO Scott Boatwright said internal research shows roughly 60% of Chipotle’s core customers earn more than $100,000 annually, a finding that has given executives confidence to lean into that group even as some lower-income diners pull back.

The comps tell a more cautious version of that story. Q2 comparable sales grew 2.2%, comprising a 1.2% increase in average check and a 1.0% gain in transactions. Management guided full-year comp sales growth to the low single-digit range, citing cautious consumer behavior and industry headwinds. Low single digits on a 33-times-earnings stock is a narrow margin for error.

The Real Question at This Valuation

Chipotle’s trailing price-to-earnings ratio stood near 34 in late August. Measured against that history, CMG looks compressed. But measured against the current growth rate, 33-to-34 times earnings still prices in a recovery that has not arrived yet.

The cyclospora episode will not appear in the full-year results as a lasting scar. Federal health officials described nearly 13,000 reported cyclospora cases tied to the multistate outbreak in 21 states, concentrated in a summer window that is now closed. What the episode did was delay an honest accounting of what CMG is worth when beef costs stay elevated and comp growth runs in the low single digits.

Long-term investors who believe Chipotle’s brand and unit economics are durable have a genuine argument. Rewards enrollment reached nearly 23 million active members, with daily sign-ups running nearly 20% higher since the April relaunch. The customer relationship is intact. The company’s innovation pipeline for the second half of 2026 includes additional limited-time protein options and more meaningful beverage innovation. These are real assets.

The wealth-building lesson here is not whether Chipotle is a good business. It clearly is. The question is the price you pay for patience. At current levels, CMG is not obviously cheap. Investors willing to own it through a beef-cost cycle at 33 times earnings are making a quality bet, not a bargain one. That is a legitimate strategy, but it requires knowing exactly what you are holding while you wait for margins to recover.
Post navigation

Previous: A warning signal no trader should miss!
Next: Elon Says AI’s Tipping Point May Be Closer Than You Think

Related Stories

4c7cab19-49f0-49cd-a193-aef8495206a4
  • Top News

Who Owns the Water Plant Now Changes Everything

Editor October 10, 2026
2f7f3c7c-2b58-457a-be68-bf23b0d92ea5
  • Top News

Moderna Is Up About 550% Since Late 2025. Oct. 24 Decides What Happens Next.

Editor October 7, 2026
0dbdde8c-6a92-4248-8056-3fc1e723a898
  • Top News

WEC Energy’s Nuclear Deal Shows Utilities Can Grow

Editor October 5, 2026

Live Market Pulse

The charting technology is provided by TradingView. Learn how to use theTradingView Stock Screener.

Want More Market News?
Add your email address below to get up to date market news and more!
By submitting your email address, you'll receive a free subscription to Options Trading Report newsletter (Privacy Policy). These newsletters are completely free - and always will be. You will also receive occasional offers about products and services available to you from our affiliates. You can unsubscribe at any time.

Recent Posts

  • Medicare Just Got More Complex for 2027 Enrollment
  • Amazon Chose a Full Buyout for Decart. The Regulatory Calculus Explains Why.
  • In at 9:35 AM. Out by 10.
  • TSMC Reports Thursday With a 65% Profit Jump on the Line
  • Preview: The Retirement Guide ($1,160/hr?)
  • Copper Is at $6.66. The Escondida Clock Is Running Out.
  • Johnson & Johnson Faces Its Toughest Earnings Test in Years

Search

Categories

  • Business
  • Economy
  • Market News
  • Newsletters
  • Top News

You may have missed

6d838224-6328-4d6a-8d5c-1492a25b2fb0
  • Market News

Medicare Just Got More Complex for 2027 Enrollment

Editor October 12, 2026
99af0d26-fad7-466c-bd78-d5455a0bece3
  • Newsletters

Amazon Chose a Full Buyout for Decart. The Regulatory Calculus Explains Why.

Editor October 12, 2026
9708832d-7898-4c61-a9ca-840dd0f41984
  • Newsletters

In at 9:35 AM. Out by 10.

Editor October 12, 2026
241e18ee-809d-4258-880a-000c7483ce41
  • Market News

TSMC Reports Thursday With a 65% Profit Jump on the Line

Editor October 12, 2026
  • About Us
  • Disclaimer
  • Privacy Policy
  • Terms of Service/Use Agreement
  • Contact Us
Copyright 2026 © All rights reserved | Options Trading Report | optionstradingreport.com SITE_OK
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}