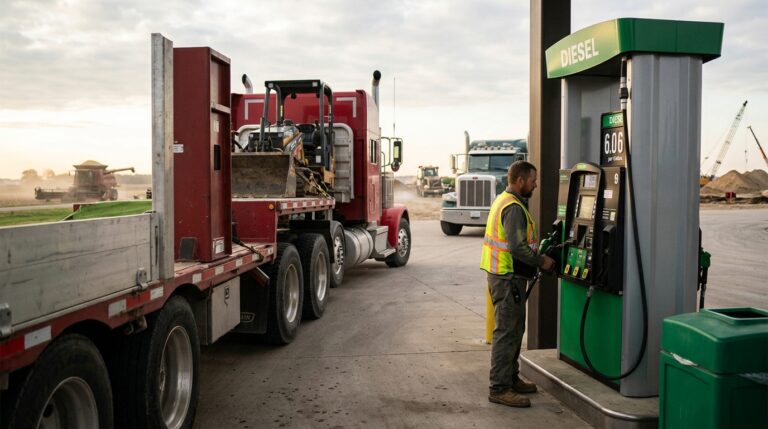
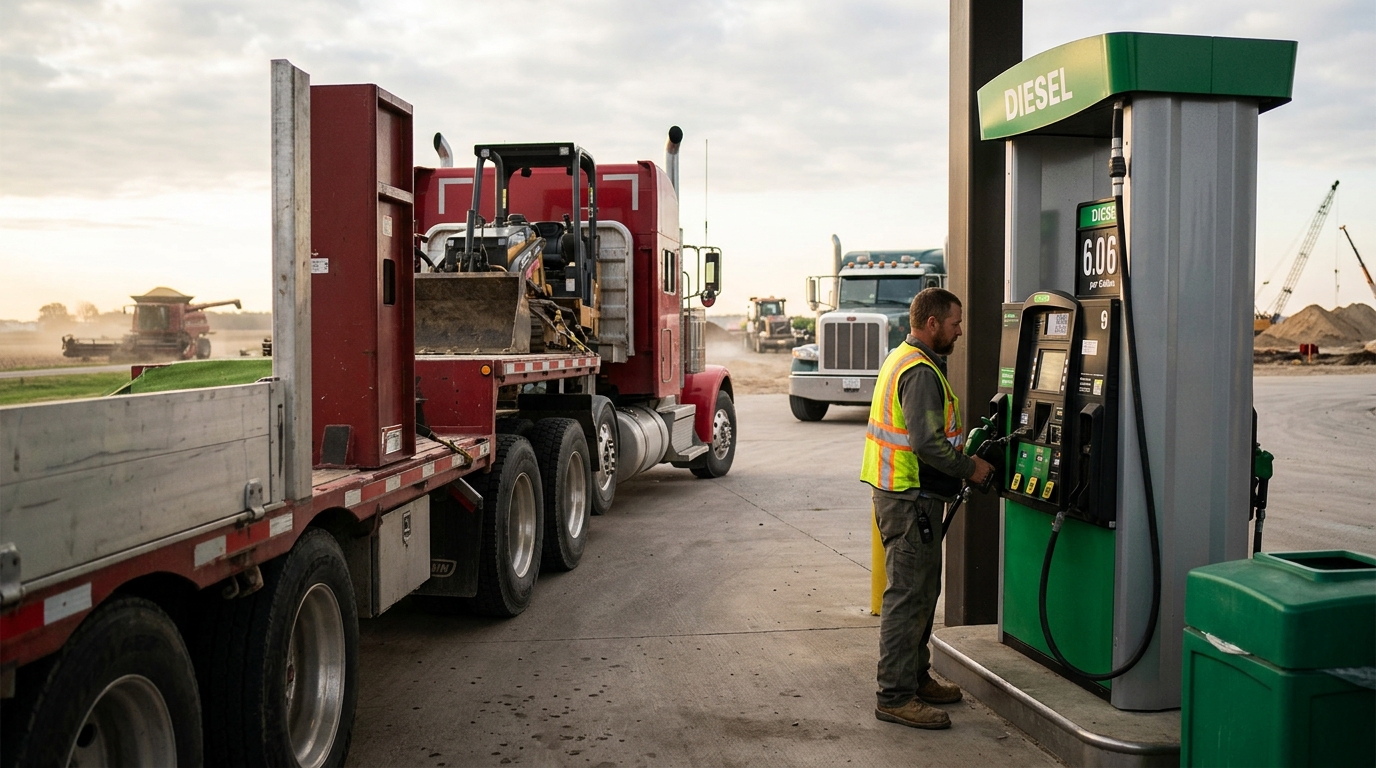
This is not a crude oil story. It is a refining story, a freight story, and a surcharge story. Crude matters. But the number that is actually reorganizing corporate profit-and-loss statements right now is $6.06 per gallon of diesel, the record AAA national average confirmed on September 11, 2026. A year ago the same gallon cost $3.71. That 63% move in twelve months is not a seasonal swing; it is a structural shift that now sits inside every freight contract, every harvest budget, and every construction bid in the country.
The catalyst stack is layered. The U.S.-Iran conflict has disrupted Strait of Hormuz flows and sent Brent crude back above $100 per barrel. On top of that, Ukraine has struck Russian oil facilities more than 300 times since 2022, hammering Russian refining capacity and prompting Moscow to impose diesel export restrictions in July. The result: a tight distillate market, with inventories projected to run below recent five-year lows into 2027.
Then came Sunday. President Trump, speaking during his Ireland visit, told President Zelensky to stop targeting Russian refineries. By Monday he posted on Truth Social that both sides had agreed to halt attacks on energy infrastructure entirely. Zelensky quickly qualified the claim, describing it as a proposal contingent on verifiable guarantees from Moscow. Worth noting: a similar energy truce was announced in March 2025, and previous partial ceasefire attempts repeatedly saw both sides accuse each other of violations.
Who Collects and Who Pays
The refining spread tells the downstream story. The ultra-low sulfur diesel crack spread hit a record $102.20 per barrel in mid-August, and it remains elevated as of this week. Valero (VLO) posted Q2 2026 adjusted EPS of $12.54 against a $10.03 Street estimate, with revenue of $44.48 billion versus a $37.95 billion consensus. Marathon Petroleum (MPC) returned $2.8 billion to shareholders in Q2 alone. Phillips 66 (PSX) delivered Q2 adjusted EPS of $9.41 against a $7.50 estimate. Combined, the three delivered some of their strongest quarter-level profit since Russia’s 2022 invasion.
The other side of that spread lands on every operator that buys diesel. Trucking fleets are carrying the sharpest squeeze because fuel surcharge mechanisms reset on monthly or quarterly schedules. When diesel jumps more than 40% in under two months, as it did earlier in 2026, those lagging resets create a gap that carriers absorb in the near term before recovery. Smaller carriers face an existential version of that math: equipment gets sold, drivers move on, and capacity does not come back quickly when conditions ease.
Agriculture and construction have no surcharge pass-through equivalent. California diesel is already above $8 per gallon on AAA’s daily tracker. Energy costs can run mid-single digits as a share of U.S. food spending in normal conditions and have been measured higher during energy spikes, with perishables absorbing first and fastest. Heating-oil prices, which typically move closely with diesel, point to sharply higher winter bills if current levels hold. The freight inflation lag is three to six months, which means the October-to-January CPI readings have not yet seen the full weight of $6 diesel.
Options Market Analysis
The options market is pricing genuine uncertainty in all three refiners. VLO’s 30-day implied volatility sat at 48, against a 52-week range of 29 to 49, placing it near the top of its annual range. MPC IV registered near the high end of its annual range. PSX IV was near the high end of its annual range. Put/call ratios in VLO showed 1.8 puts per call as of September 10, signaling that the market is buying downside protection despite the earnings tailwind. MPC was balanced near 1:1. PSX leaned slightly bullish.
The elevated IV levels reflect a binary in the options market: if the Trump-Zelensky ceasefire becomes operational and Russian refining capacity comes back online, crack spreads compress and refiner earnings estimates fall materially. If the ceasefire fails, the structural distillate squeeze continues through winter and Q3 estimates remain too low.
Structured Trade Framework
Bull case (refiners): For traders expecting the ceasefire to fail or stall, a defined-risk structure in VLO or MPC using a vertical call spread captures continued crack spread expansion into Q3 reporting. With IV near annual highs, long premium requires wider spreads or shorter duration.
Bear case (refiners): If you believe a credible energy truce removes the refinery attack premium, elevated IV makes put spreads on VLO attractive as a defined-risk hedge. The Q2 earnings base is high; any crack spread normalization hits Q3 estimates from an already-stretched starting point.
Neutral/volatility case: IV rank near the top of its range across all three names means premium selling structures (iron condors, short strangles with defined risk) collect elevated premiums while the binary resolves. Size accordingly given the geopolitical event risk.
Risk Analysis and Forward Outlook
The core risk is that diesel and crude are now partially decoupled. Even a Hormuz reopening or a genuine refinery ceasefire will not immediately translate to lower pump prices because the refining bottleneck runs on its own timeline. Lost capacity, whether from Russian strikes or California constraints, cannot be rebuilt in weeks. The freight inflation embedded in October to January consumer prices is already in the pipeline regardless of what happens in eastern Ukraine tomorrow.
For investors watching the crack spread as the primary signal, the threshold question is whether today’s elevated cracks represent a new mid-cycle floor, or a temporary wartime premium that compresses on any ceasefire news. That debate resolves in the Q3 earnings window, roughly six weeks from now.
Action Checklist
- Track weekly EIA on-highway diesel average as the leading indicator; any sustained move below $5.80 signals crack spread compression risk for refiner longs
- Monitor VLO/MPC/PSX IV daily into any ceasefire news; a volatility spike on a deal announcement may create a premium-selling entry
- Watch Russia diesel export restrictions; any relaxation is a clear near-term bearish refiner catalyst
- Freight operator exposure (ODFL, JBHT) warrants lag-adjusted analysis; surcharge recovery compresses margins now, but Q4 rate hikes could follow if capacity exits accelerate
- Treat the October CPI reading as the first full measurement of $6 diesel pass-through into core goods pricing