October 22, 2026
Bonus Content: GM Beat Every Number, Then Fell 7%. Here Is Why.
If you haven’t downloaded my “Top 10 Stocks to Buy This Quarter” report yet, please do it right now.
It takes about five seconds.
And once we swap in next quarter’s list, this edition won’t be available anymore.
Good Trading,
Bill Poulos
p.s. It’s the 10 stocks we like most right now, each one explained in plain English. Normally $29.97. Free here.
GM Beat Every Number, Then Fell 7%. Here Is Why.
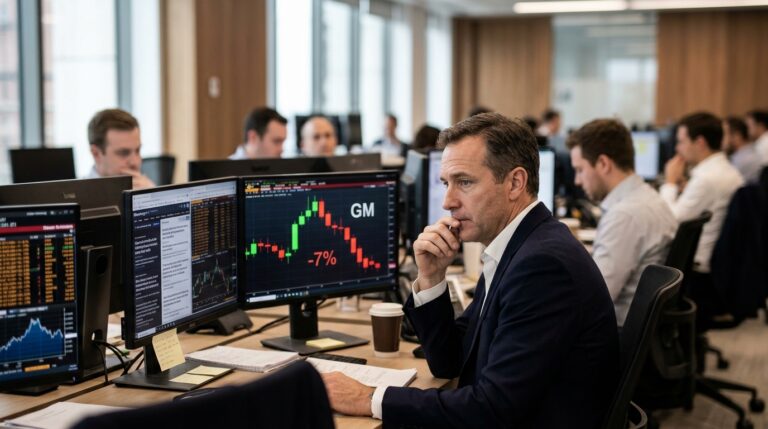
Markets don’t need a perfect quarter. They need a quarter that beats the number investors were secretly holding in their heads, not just the one published on Bloomberg. General Motors learned that distinction Tuesday, October 20, 2026, in the most expensive way possible.
GM reported adjusted EPS of $3.70 on revenue of $50.02 billion, topping Wall Street estimates of about $3.63 and about $48.76 billion, respectively. Net income attributable to stockholders rose to $3.3 billion from $1.3 billion a year earlier, and adjusted EBIT rose 21.6% to $4.1 billion. The company also raised its adjusted automotive free cash flow forecast and unveiled a buyback that eclipses most peers’ entire market caps. The stock still fell about 7% during Tuesday’s session.
The Numbers
Adjusted EPS of $3.70 came in 32% above the $2.80 posted a year earlier and cleared the $3.63 consensus; revenue of $50.02 billion topped the roughly $48.8 billion analysts had expected. GM raised its adjusted automotive free cash flow forecast to $11.5 billion to $12.5 billion, up from $9.5 billion to $11.5 billion. The board approved a $20.0 billion repurchase authorization after fully utilizing the $6.0 billion increase the board approved in January 2026 under the existing program. Shares outstanding stood at 849 million as of September 30, down from 904 million at the end of 2025.
Is This Elon Musk’s Next IPO?
After taking SpaceX public in the biggest IPO ever, Elon Musk is already working with a NEW startup that’s growing faster than Tesla…
Faster than SpaceX… And faster than any of Elon Musk’s previous ventures.
Bloomberg has just confirmed that this startup is moving towards “a blockbuster IPO.”
Click here to get the name completely free of charge
And Jeff Brown will also show you how to claim a pre-IPO stake for as little as $50.
Why the Stock Fell
The answer is on one line of the release. GM narrowed its full-year 2026 adjusted EBIT guidance to $14.5 billion to $15.5 billion, from $14.0 billion to $16.0 billion. Management narrowed that operating profit range without moving the midpoint, which meant the outlook delivered no upgrade to pair with the beat and the buyback. Analysts’ expectations included a full-year EPS midpoint of $13.41, compared with GM’s new $13.25 midpoint. That 16-cent miss on the midpoint, almost invisible in isolation, was the actual guidance number the market was trading against.
Ford slipped just 2% on the same day while Tesla barely moved, confirming the selloff was largely GM-specific. This is not a sector call. It is a forward-earnings re-rating on one company that delivered a clean quarter and a cautious tone about commodity and logistics costs heading into 2027.
Options Market: The Positioning and the Aftermath
The options market had this event reasonably well calibrated in magnitude, yet directionally ambiguous in the way only earnings events can be. Pre-earnings, the options market was pricing in roughly a 6% to 7% move in either direction in GM stock for the October 20 event.
The actual move landed near the expected range, which means premium sellers collected on the magnitude call even as directional buyers on the call side were carried out. Into the event, put activity was elevated versus calls, a sign that hedging pressure was building even before the release. Post-event, with the uncertainty resolved, option premium typically drops sharply in the volatility crush.
Structured Trade Framework
Bull case: If you believe the guidance midpoint miss is already fully priced into the roughly 7% decline and that the $20 billion authorization provides a durable floor, a defined-risk structure such as a bull put spread below current levels targets premium collection while the repurchase program absorbs selling pressure. Bear case: For traders expecting 2027 cost headwinds to compress the EBIT range further on the next update, a long put or bear call spread above the $82-$83 area captures continued re-rating risk with defined exposure. Neutral case: With implied volatility typically lower post-event, an iron condor centered on current levels suits traders expecting consolidation while the buyback and the clean balance sheet limit downside depth.
Risk Factors and Forward Outlook
The selloff suggests traders were focused on management’s caution around commodity and logistics costs, as well as the possibility that 2027 growth could be harder to deliver. Results outside North America also mattered, even if the buyback took the headline.
The new $20 billion authorization represents a large share of GM’s market capitalization. That is a structural bid under the stock, but not an immediate catalyst. Buybacks reduce share count over years, not sessions.
Action Checklist
- Re-anchor fair value to the new EBIT midpoint of $15.0 billion, not the prior $15.0 billion midpoint that was disguised inside a wider range.
- Monitor whether the EPS guidance midpoint of $13.25 moves toward or away from the $13.41 Street estimate on the next update.
- Treat post-event implied volatility as a new baseline; any re-inflation before the next catalyst can reopen premium-selling windows.
- Watch Ford’s next quarter for sector read-through on commodity cost trajectory.
- Size any defined-risk position against the buyback floor: the repurchase program creates absorption at lower prices, but does not prevent re-rating if 2027 guidance disappoints.