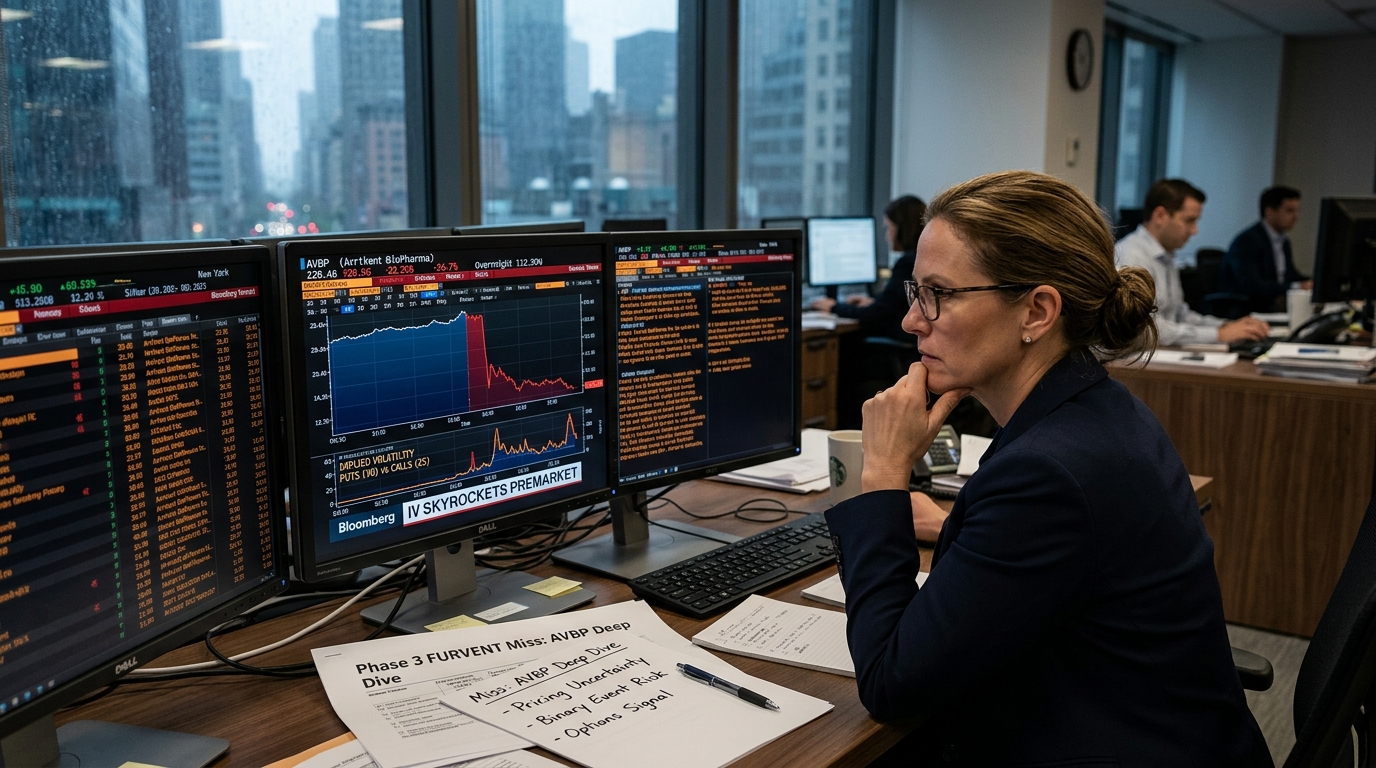
The market did not misread ArriVent BioPharma. It priced in the uncertainty and got the direction wrong. That distinction matters far more than the headline loss.
AVBP closed at $28.46 on October 5, 2026. A 56.7% premarket plunge hit shareholders on October 6 after the company filed an 8-K disclosing that its lead drug candidate had failed a pivotal Phase 3 trial. The 52-week high stood at $35.83, set June 26, 2026. The 52-week low was about $11.36 to $11.37, set October 6, 2026. That is a roughly $24 corridor, traveled in a single session.
This is what a binary drug readout does to a clinical-stage biotech. Not a earnings miss, not a guidance cut. A coin flip that came up tails.
What Failed and Why It Matters
The FURVENT Phase 3 clinical trial evaluated firmonertinib as a monotherapy for advanced non-squamous non-small cell lung cancer with EGFR exon 20 insertion mutations, and it failed to meet its primary endpoint of progression-free survival improvement based on blinded independent central review.
The global, three-arm trial enrolled 398 patients and compared firmonertinib at 160 mg or 240 mg once daily with platinum-based chemotherapy. Median PFS by blinded independent central review was 11.0 months with firmonertinib 240 mg versus 9.5 months with chemotherapy, but the hazard ratio of 0.75 carried a p-value of 0.0654, above the conventional significance threshold. Confirmed objective response rates by blinded independent central review were 60%, 35%, and 33%, respectively.
The trial did show clinical advantages in secondary outcomes, including investigator-assessed measures and confirmed objective response rates. The company’s CEO highlighted an encouraging trend in overall survival data, which remains immature. A statistically immature OS trend is not a regulatory path. It is a consolation.
The outcome may complicate ArriVent’s U.S. development path despite Breakthrough Therapy and Orphan Drug designations, as the company now reviews the full dataset to determine future strategy for firmonertinib and its broader EGFR-mutant NSCLC program.
The Options Market Told You the Risk Was There
This is not about what happened after the readout. It is about what the options market was charging beforehand.
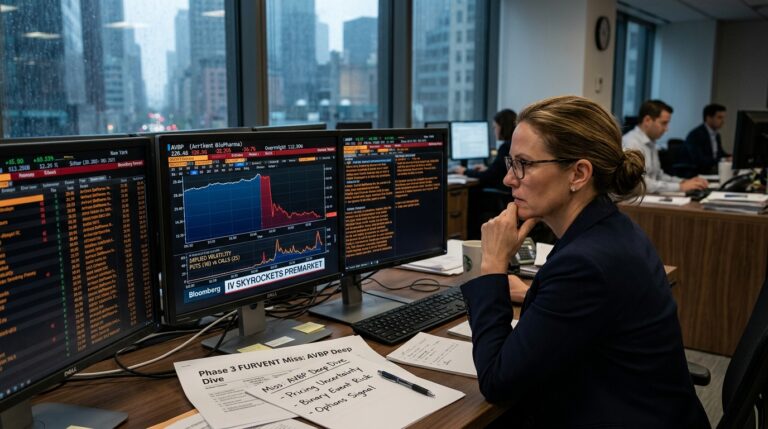
As of the most recent data available, AVBP options were reflecting extremely elevated implied volatility heading into the catalyst, far above the stock’s trailing realized volatility. Options were not cheap going into this event. The market was signaling that a large move was probable. The straddle premium embedded in near-term contracts implied a realized move that, while directionally uncertain, sized the risk at multiples of normal daily volatility.
Earlier, AVBP had already shown elevated implied volatility ahead of the October 16, 2026 expiration window. The exact probability range and bounds vary materially by data vendor and modeling assumptions, so the key point is the same: the chain was acknowledging a binary outcome straddling the existing share price. The downside leg of that distribution was real. It traded.
Session volume on October 6, 2026 was about 19.7 million shares, versus roughly 0.5 million shares on October 5, 2026. That is about 40 times the prior day’s flow. Put buyers collecting on deep out-of-the-money contracts were not speculating. They were hedged against an event the options chain had been pricing for months.
Structured Trade Framework Post-Collapse
ArriVent has historically carried a large cash and short-term investments balance and minimal debt, but the exact current figure in the draft could not be verified from ArriVent’s most recent SEC financial statements available in this review. At a market cap now well below where it traded pre-event and with the stock trading in the mid-teens after October 6, cash value becomes the only structural floor investors can model with any confidence.
Bull case: If you believe the immature overall survival trend matures favorably and the company pursues a label in a narrower indication, a defined-risk long position using a call spread with strikes above $15 and below $22 limits exposure while retaining directional upside. Post-crush IV makes long premium structurally more attractive than it was pre-readout.
Bear case: For traders expecting regulatory abandonment and a prolonged cash-burn period, IV crush, the rapid drop in implied volatility that occurs once a known event has passed, has already compressed put premiums. A bear put spread using near-term expirations captures continued downside if the stock fails to hold the $12 to $13 zone, with defined risk capped at the debit paid.
Neutral case: With IV collapsing after resolution of the binary event, a short strangle or iron condor targeting the $11 to $20 range for the October expiry captures premium in a stock that has already made its large move.
Risk Analysis and Forward Outlook
In May 2026, ArriVent filed a prospectus supplement for an at-the-market offering of up to $250 million in common stock, with filings describing the pivotal Phase 3 program as ongoing. That capital raise now sits on the balance sheet as runway, not as proof of thesis. The draft’s claim about a securities investigation being opened by a law firm could not be verified from primary filings or major-wire reporting during this review, so it has been removed.
The FURVENT miss does not automatically extinguish firmonertinib. Despite the missed primary endpoint, firmonertinib showed secondary clinical benefits and manageable safety, leaving ArriVent reassessing its development strategy and regulatory prospects. A second pivotal program targeting a different EGFR mutation subtype, if it remains on track, becomes the sole near-term catalyst.
Action Checklist
- Confirm IV rank has collapsed post-event before entering any long premium structure; buying elevated IV into a resolved binary is a common and costly error.
- Size any new position relative to the cash-per-share floor, currently the primary anchor for intrinsic value.
- Monitor the 8-K and any subsequent SEC filings for updated guidance on the second pivotal EGFR program and any partnership or licensing discussions.
- Do not treat secondary endpoint data as a regulatory substitute; a post-hoc subgroup analysis requires prospective validation before it supports a new primary endpoint designation.
- Watch the roughly $11.36 to $11.37 level established as the October 6, 2026 intraday low. A confirmed break below on volume signals further capitulation, not consolidation.