October 10, 2026
Bonus Content: UnitedHealth Heads Into Tuesday Earnings Down 18%, With Its Full-Year Profit Floor on the Line
Dear Trader,
My top income trading expert, Dave Aquino, just released a 1-hour trading strategy designed specifically to help regular investors generate enough income to become financially independent…
Without taking on excessive amounts of risk.
I’m talking about having the opportunity to collect $500 on Monday…
$563 on Wednesday…
Then as much as $625 on Friday.
Week in. And week out.
To better trading,
– Drew Day
Partner
Base Camp Trading
UnitedHealth Heads Into Tuesday Earnings Down 18%, With Its Full-Year Profit Floor on the Line
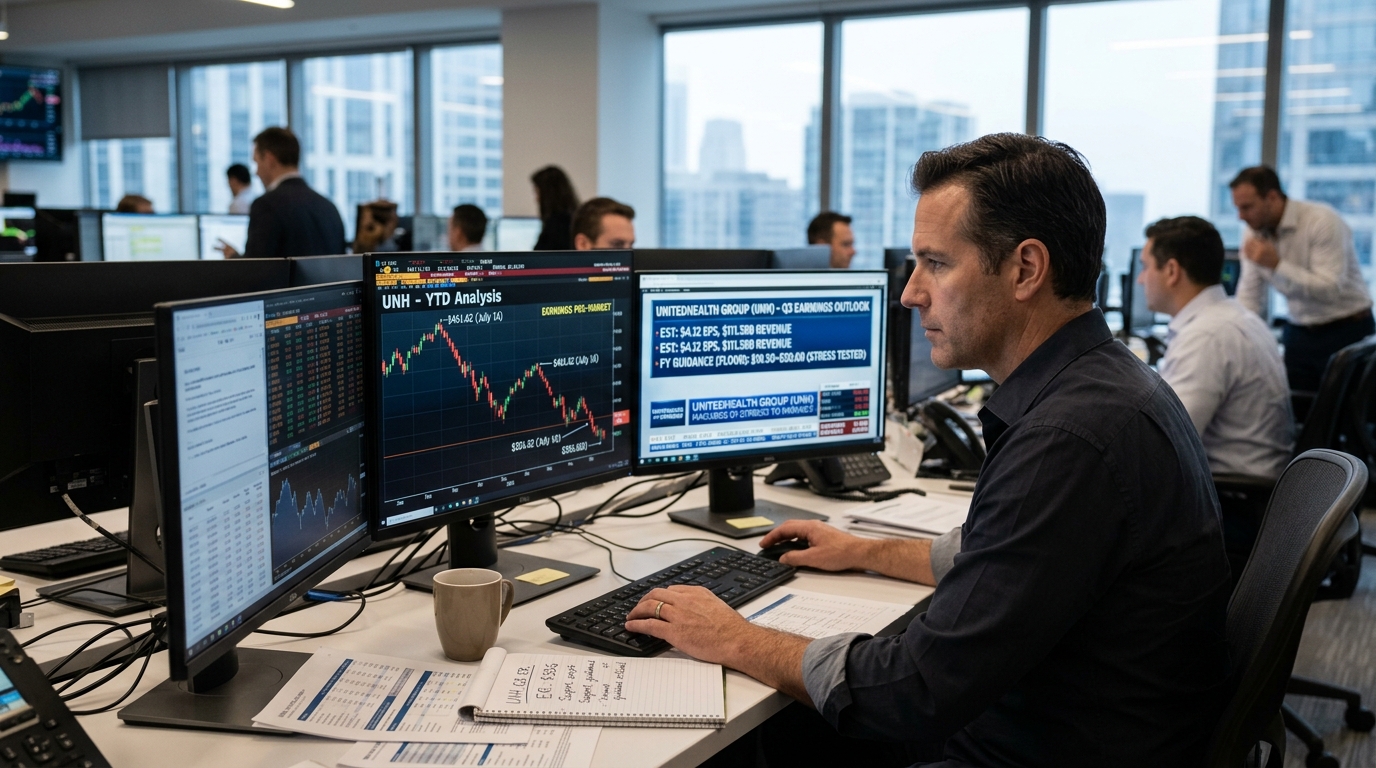
Markets don’t need UnitedHealth to post a blowout quarter. They only need it to defend its guidance. That distinction matters heading into Tuesday’s pre-market report, because the stock has surrendered roughly 18% since its July 16 all-time high of $461.62, and the full-year adjusted EPS floor of $19.50–$20.00 is now the number every managed-care investor is stress-testing.
UNH is set to report Q3 2026 results on October 13, 2026 before the opening bell, with the consensus estimate pegged at $4.12 per share on revenues of $111.38 billion. That quarterly bar implies a bottom-line improvement of 41.1% from the year-ago number. Revenue, however, is working against the current: the consensus for quarterly revenues implies a year-over-year decline of 1.6%.
Medicare Advantage enrollment is declining. On its July 16, 2026 earnings call, management said it now expects Medicare Advantage enrollment to decline by approximately 1.1 million in 2026.
What Q2 Bought — and What It Didn’t
The most consequential driver in Q2 was a meaningful improvement in the medical care ratio to 86.7% from 89.4% in Q2 2025, which included $860 million in net favorable prior period medical reserve development. UnitedHealthcare’s operating margin expanded to 4.6% from 2.4%.
On the back of that performance, the company raised its full-year adjusted EPS outlook to $19.50–$20.00, lifted operating cash flow guidance to approximately $24.0 billion, and doubled its share repurchase commitment to at least $5.0 billion.
The problem is that Q2’s MCR included a significant reserve tailwind. Full-year MCR guidance stands at 88.1% plus or minus 25 basis points. Any deterioration in Q3 cost trends beyond that tolerance could force a guidance revision, and the stock is sitting close enough to technical support that the reaction would not be contained.
The Star Rating Wildcard
CMS published the 2027 Medicare Advantage and Part D star ratings on October 8, 2026. The release reshuffled the competitive landscape. Humana said 95% of its Medicare Advantage members are now in 4-star-or-above plans for 2027.
The competitive stakes behind that 95% figure are concrete. Humana’s H5216 contract returning to 4 stars is worth roughly $1.5 billion of EBIT and $9 of EPS in 2028 bonus payments.
That gap matters beyond enrollment optics: the 2027 star rating drives the 2028 quality bonus payment and appears publicly on Medicare Plan Finder. Management will be pressed on Tuesday to quantify the 2028 revenue impact. Any guidance cut will carry that star-rating math inside it.
Where the Stock Sits Technically
The downtrend from July remains intact, though buyers have recently defended the lower Keltner band. A break below $356 would bring April’s unfilled gap into focus, while a sustained move above $408 would materially improve the chart outlook.
UNH is trading at about 17x forward 12-month earnings. Valuation compression provides a cushion against catastrophic de-rating, but it does not protect against a guidance cut in a downtrending market.
Options Market: What the Pricing Says
Options imply a move of roughly ±8% for UNH’s October 13 report. Applied to a Friday close near $379, that frames a post-earnings range of roughly $349 to $409. The lower bound coincides almost exactly with the $356 technical support level. A guidance cut that breaks that floor puts April’s gap squarely in play.
Sentiment among options traders is pessimistic. UNH’s put/call positioning has been elevated versus its own recent history, and the options market is pricing a wider-than-usual earnings move. The consistent message is that traders are not treating a relief rally as the base case.
Structured Trade Framework
Bull case: UNH reports Q3 MCR at or below guidance, reaffirms the $19.50–$20.00 full-year EPS range, and management addresses star-rating headwinds with a credible 2028 mitigation plan. For traders expecting that outcome, a defined-risk structure such as a bull call spread in the $375–$408 range captures the move toward resistance without naked upside exposure ahead of IV crush.
Bear case: MCR comes in above the 88.1% guidance midpoint, management trims the full-year EPS floor, or the star-rating impact on 2028 bonus math is larger than the market has modeled. A defined-risk bear put spread centered on the $356 level, buying the $360 put and selling the $340 put in the October monthly, defines maximum loss and targets the gap below support.
Your Download Link Will Expire
If you still haven’t downloaded my free “Safe Trade Options Formula” guide…
…please take a few seconds and download it right now before your new temporary download link expires.
I eventually plan to charge money for this training, so do yourself a favor and download it now…
That way, no matter what it costs in the future, you’ll have a free copy on your computer.
Make sense?
Neutral case: Given IV crush risk and an ±8% expected move already priced, a short iron condor positioned just outside that range, short the $340 put and $410 call, long the $320 put and $430 call, collects premium if the stock resolves within the implied band. Risk is defined on both wings.
Risk Factors and Forward Outlook
The $860 million in favorable reserve development that helped Q2 MCR will not repeat mechanically. If Q3 cost trends in Medicare Advantage have run hotter than reported, the reserve true-up lands on Tuesday’s release.
Sector peers ELV, CVS, and CI all carry their own medical-cost read-throughs into this number.
Action Checklist
- Watch the Q3 MCR print against the 88.1% ± 25 bps full-year guidance band. Any reading above 88.35% pressures the annual EPS floor.
- Listen for explicit 2028 star-rating commentary. Management needs to quantify any quality bonus haircut.
- Monitor $356 as the key post-earnings technical level. A closing break invites the April gap fill near $320.
- Confirm full-year adjusted EPS guidance is held at $19.50–$20.00. Any reduction resets the valuation debate.
- Account for IV crush when sizing options positions. A ±8% implied move with IV at elevated pre-earnings levels means long premium strategies require a move that exceeds what is already priced.