October 9, 2026
Bonus Content: ZIM Raised Its Profit Forecast 72%. The $35 Buyout Still Looks Far Away.
Early to America’s Next Defense Boom?
Sometimes Wall Street only needs one headline.
When a report named possible contenders for a $1.1 billion Pentagon drone contract, shares in the sector jumped as much as 57% in a single afternoon.
Another American drone manufacturer has climbed more than 700% from its 2024 IPO price.
Those moves do not guarantee what happens next. But they show how quickly investor money can move when Wall Street sees government demand building behind an emerging industry.
Yet, this little-known drone company is still trading under $5 on the Nasdaq… for now.
It has more than 25 years of experience, a growing patent portfolio and drone technology already used in real world missions.
Still, it has not received the same level of investor attention as some of the market’s earlier winners.
The question may not be whether drone companies can rally. It may be which overlooked name Wall Street discovers next.
ZIM Raised Its Profit Forecast 72%. The $35 Buyout Still Looks Far Away.
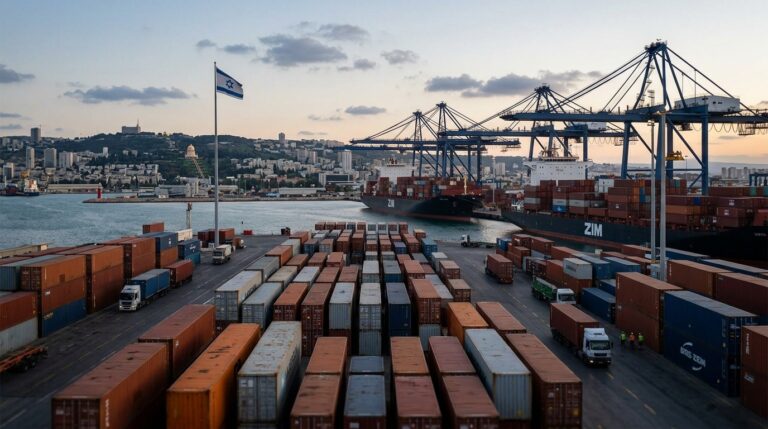
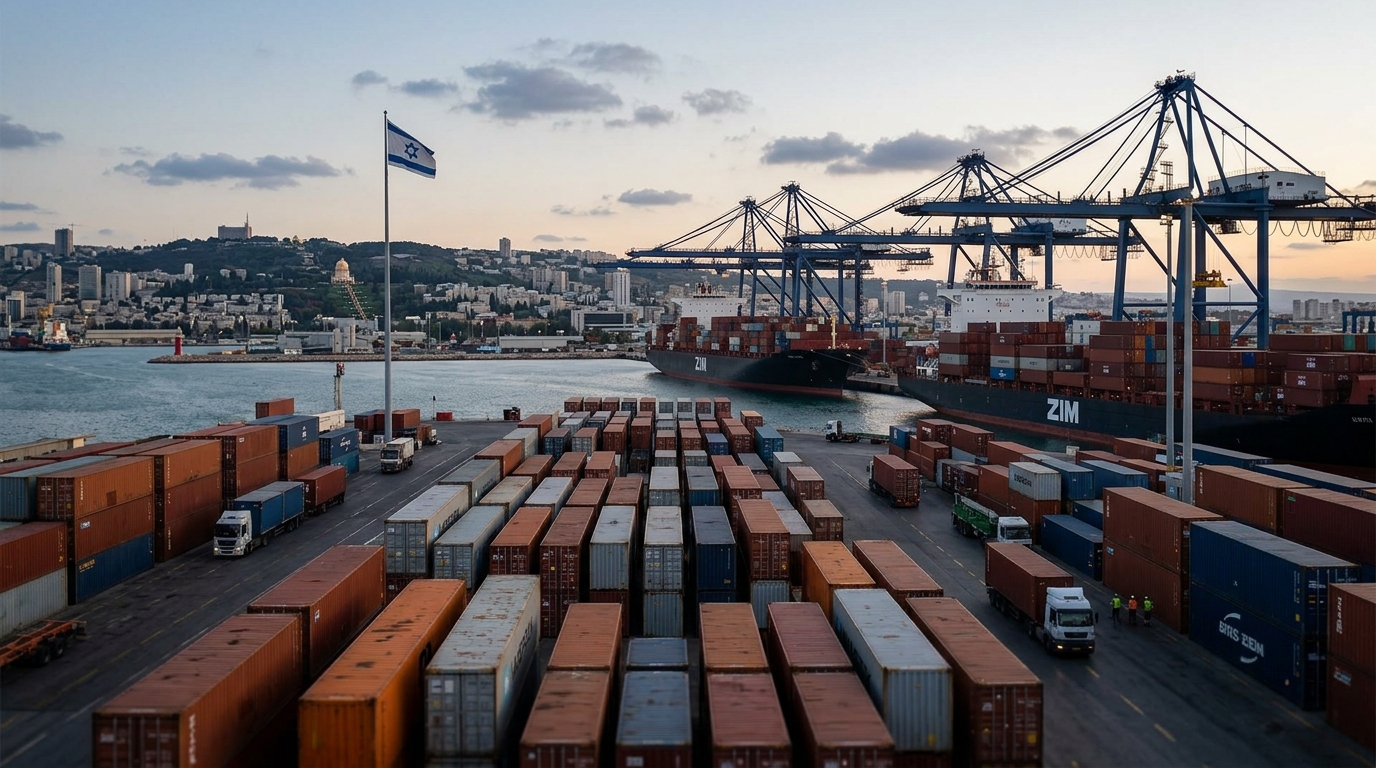
Container shipping has done something that usually takes tanker markets years to accomplish. Freight rates on the trans-Pacific have stayed elevated long enough to force carriers into back-to-back upward guidance revisions. ZIM Integrated Shipping Services raised its 2026 profit guidance on October 6, 2026, the second revision in roughly seven weeks. The revised adjusted EBITDA midpoint is about 30% higher than the prior outlook, while the adjusted EBIT midpoint represents a 72% increase from the previous forecast. The math is not subtle.
ZIM now expects adjusted EBITDA of $2.7bn to $3.0bn and adjusted EBIT of $1.4bn to $1.7bn for the full year. Higher container freight rates carry an outsized impact on shipping companies because much of their vessel and operating cost base is fixed or contracted. Stronger rates therefore translate quickly into higher operating profit when demand remains firm.
But here is where the analysis gets compressed. ZIM shares remain pinned well below Hapag-Lloyd’s $35 cash offer by Israeli approval risk. The company itself warns that its updated forecast is dependent on geopolitical factors and trade uncertainties, including risks and uncertainties relating to the outcome of the pending transaction with Hapag-Lloyd. The transaction had initially been expected to close by the end of 2026, but the merger agreement also includes an outside date in 2027, making a 2027 completion increasingly plausible if the regulatory process drags.
The Deal Spread
Israel’s Finance Ministry objected to the proposals, stalling the roughly $4.2bn sale and citing concerns tied to national interests. Israel’s Government Companies Authority stopped processing the parties’ existing approval application after Hapag-Lloyd and FIMI did not submit a detailed revised proposal for ZIM’s post-closing operations by the regulator’s deadline. Hapag-Lloyd has said it intends to resubmit revised terms.
The stronger earnings have not lifted shares toward the offer. At about $29.20, ZIM sits about 17% below the $35 in cash Hapag-Lloyd has agreed to pay. CEO Eli Glickman sold about 87% of his holdings at prices between $28 and $29. When insiders sell at a discount to a pending acquisition price, the implicit message is clear: they assign real probability to a delay or restructure.
Options Market Analysis
ZIM’s implied volatility and put/call statistics move daily, and the specific figures cited in the prior draft could not be verified from primary, timestamped public sources. The durable takeaway remains the same: the stock is trading like a deal spread with a macro overlay, so options pricing can show a split between near-term call-side speculation and longer-dated put demand tied to a binary regulatory outcome.
The divergence is the signal. Volume buyers can lean call-side, likely expressing deal-closure optimism. Existing open interest, built over weeks, can carry more put protection. When implied volatility is elevated, premium sellers are being compensated for uncertainty, and a wide put-over-call skew typically reflects asymmetric downside concern around the regulatory outcome.
Structured Trade Framework
Bull case. For traders expecting Israeli regulatory approval and deal closure at $35, the 17% gap represents a defined return window. A defined-risk structure would be a long call spread with the short leg near $33 and the long near $30, capturing the bulk of the close-to-deal move while capping cost. Keep expiry out past Q1 2027 given the slipping timeline.
Bear case. If you believe the deal collapses entirely, ZIM’s standalone freight fundamentals become the floor. ZIM reported total revenues of $1.64bn in Q2 2025, and its average freight rate was $1,479 per TEU in that quarter. A put spread around $26/$22 captures a reversion toward pre-deal trading levels at defined cost.
Neutral case. If you believe the deal drags into 2027 but freight fundamentals hold, a short strangle positioned inside the $26/$34 band collects elevated premium while the stock treads water. Risk is a binary event: surprise approval or collapse, both of which can be partially hedged by keeping position size modest.
Risk Analysis and Forward Outlook
The guidance does not break out how much of the upgrade is rate versus volume, making it hard to assess durability, and ZIM flags geopolitical instability and rate swings as risks. Rates on the Asia-Europe trade have now declined for 12 consecutive weeks, reflecting weak demand, which is a meaningful caveat for a carrier whose earnings revision leaned on broad rate momentum.
Action Checklist
- Current ZIM price approximately $29.20, deal at $35, spread roughly 17%.
- Options inputs (IV, IV rank/percentile, put/call) change daily. Treat any single snapshot as time-stamped, not static.
- Insider behavior: CEO Eli Glickman sold about 87% of his holdings at $28 to $29, below the $35 offer price.
- Deal timeline: a 2027 close is plausible if the Israeli approval process requires a full resubmission and re-review.
- Monitor Hapag-Lloyd’s revised proposal submission to Israel’s Government Companies Authority as the primary catalyst that will either compress or blow out the spread.
- Watch Asia-Europe freight rates: 12 consecutive weekly declines create a separate downside risk to standalone earnings if the deal falls through.