Dear Reader,
The Democratic Socialists won big at the polls this election cycle.
They’ve more than tripled their votes in Congress.
And even managed to win the mayor’s office in D.C.
But as terrifying as that is, there’s an EVEN BIGGER threat you should be paying attention to right now.
Frankly, I’m not surprised so many Socialists won.
They’ve pointed out many things that are genuinely wrong right now:
- The middle class is struggling.
- Your dollars aren’t going as far as they used to.
- Big business is in cahoots with the government.
Don’t get me wrong, I’ve spent my whole career warning where Socialism leads.
But fundamentally, these aren’t political problems more handouts will fix.
That’s why I’m stepping forward today.
Because the most dangerous economic force in America right now is EVEN WORSE than Socialism.
It’s managed to quietly take over Washington – long before this election cycle began.
And, based on the results, I’m afraid this will all reach a breaking point in the coming weeks… and have a serious effect on any money you’ve set aside for retirement.
I strongly encourage you to check out my important message, which explains everything you need to know. You can access it free of charge here.
Sincerely,
Dr. Ron Paul
12-Term Former Congressman
Former Presidential Candidate
Washington Insider for Over 50 Years
P.S. I think you’ll agree that one of the most interesting parts of my new video is where I reveal the #1 step Americans can take to protect themselves today from these coming disasters.
RYTM Trades Below the Bid. The Gap Is the Trade.
Markets don’t need a signed merger agreement. They only need enough probability and enough premium to make the spread worth holding. Right now, RYTM offers both, and the options market has not fully caught up.
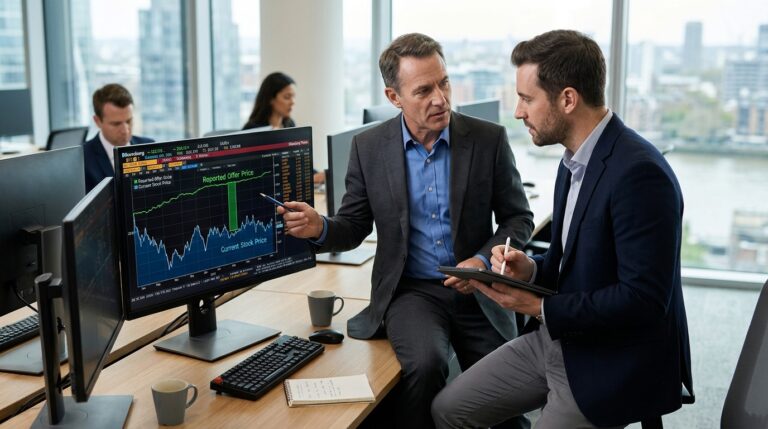
AstraZeneca reportedly made a non-binding offer of about $10 billion to acquire Rhythm Pharmaceuticals, with the value per share reaching as much as $134 if milestone payments are included. The Wall Street Journal had earlier reported a $124-per-share offer made last month. Shares of Rhythm closed up 28% at $110.68 on November 4, 2026 on the initial reporting. As of November 10, 2026, the stock is hovering around the low-$110s, leaving a spread of roughly the low-$20s to the top of the reported range. That gap is not noise. It is the market’s composite estimate of deal risk, timeline, and competing-bid probability.
The Underlying Business Is Not Speculative
Net product revenues from global IMCIVREE sales were $92.1 million in Q3 2026, compared to $51.3 million in Q3 2025. The U.S. represented about 73% of Q3 2026 IMCIVREE revenue. This is not a pipeline-only asset. Rhythm is a commercial-stage company with accelerating revenue, which is precisely what a roughly $280 to $295 billion acquirer pays a control premium to absorb.
Rhythm’s approved therapy Imcivree treats rare obesity caused by specific genetic defects, and on March 19, 2026 the FDA expanded its use to acquired hypothalamic obesity. Bivamelagon is advancing into pivotal development in acquired hypothalamic obesity, and the company has said it is targeting a Prader-Willi syndrome study in 2027, pending alignment with the FDA. Jefferies analyst Dennis Ding noted that AstraZeneca’s offer implies minimal valuation for the Prader-Willi program, including bivamelagon, which is moving toward later-stage development. That is the buyer’s leverage point and the seller’s negotiating argument simultaneously.
Bidding War Probability Is Not Zero
On November 6, Rhythm shares climbed about 4.2% following reports of a second potential bidder entering consideration. Analysts at Jefferies, Leerink, and William Blair have argued a bidding war could be brewing, suggesting Rhythm is unlikely to settle for AstraZeneca’s current pitch. While Rhythm’s therapies target rare genetic forms of obesity rather than the broader weight-loss market, an acquisition would give any buyer an established commercial presence in a fast-growing field while expanding their rare-disease portfolio.
The acquisition would be pursued through AstraZeneca’s rare-disease unit Alexion, which AstraZeneca acquired in a $39 billion deal that closed in 2021. That structural detail matters: Alexion is an integration-ready vehicle. A competing bidder without that infrastructure faces a steeper synergy argument to justify a higher price.
Options Framework
With RYTM trading roughly 18% below the top of the reported offer range and deal certainty still unconfirmed, IV on near-dated options has compressed relative to the early-November spike. That is the structural opportunity. Premium sellers who sold volatility immediately after the initial 28% gap-up captured peak IV; premium buyers entering now face a different calculus.
Bull case: If you believe the deal closes at or near $134, a defined-risk long call spread in the December expiry targeting the $120/$130 range captures upside while limiting exposure to deal-break risk. Spread cost is modest relative to the distance to the top-end bid.
Bear case: For traders expecting the deal to collapse or stall well below $124, a put spread below $100 defines risk while expressing the view that a failed auction returns the stock toward pre-bid levels in the mid-$80s.
Neutral case: With a contested ceiling between $124 and $134 and the stock consolidating in the low-$110s, an iron condor bracketing $105 to $130 collects premium from both sides if negotiations drag into Q1 2027 without resolution.
Risk Analysis
The offer remains non-binding. Neither company has commented publicly, and the offer is reported rather than formally announced. AstraZeneca also recently launched a restructuring program targeting $1.5 billion in annualized pretax run-rate benefits, with activities expected to be completed by the end of 2029. A company simultaneously restructuring and pursuing a $10 billion acquisition carries execution tension that boards and shareholders on both sides will scrutinize.
Checklist
- RYTM recent range: around the low-$110s
- AstraZeneca reported bid: $124 upfront, up to $134 with milestones
- Q3 IMCIVREE revenue: $92.1 million vs. $51.3 million a year earlier
- Second bidder reported: November 6, unconfirmed
- Bivamelagon Phase 3: acquired hypothalamic obesity initiation targeted by year-end 2026; Prader-Willi study targeted for 2027 pending FDA alignment
- Deal status: non-binding, unconfirmed by either party
- Key risk: deal break returns stock toward pre-bid levels in the mid-$80s