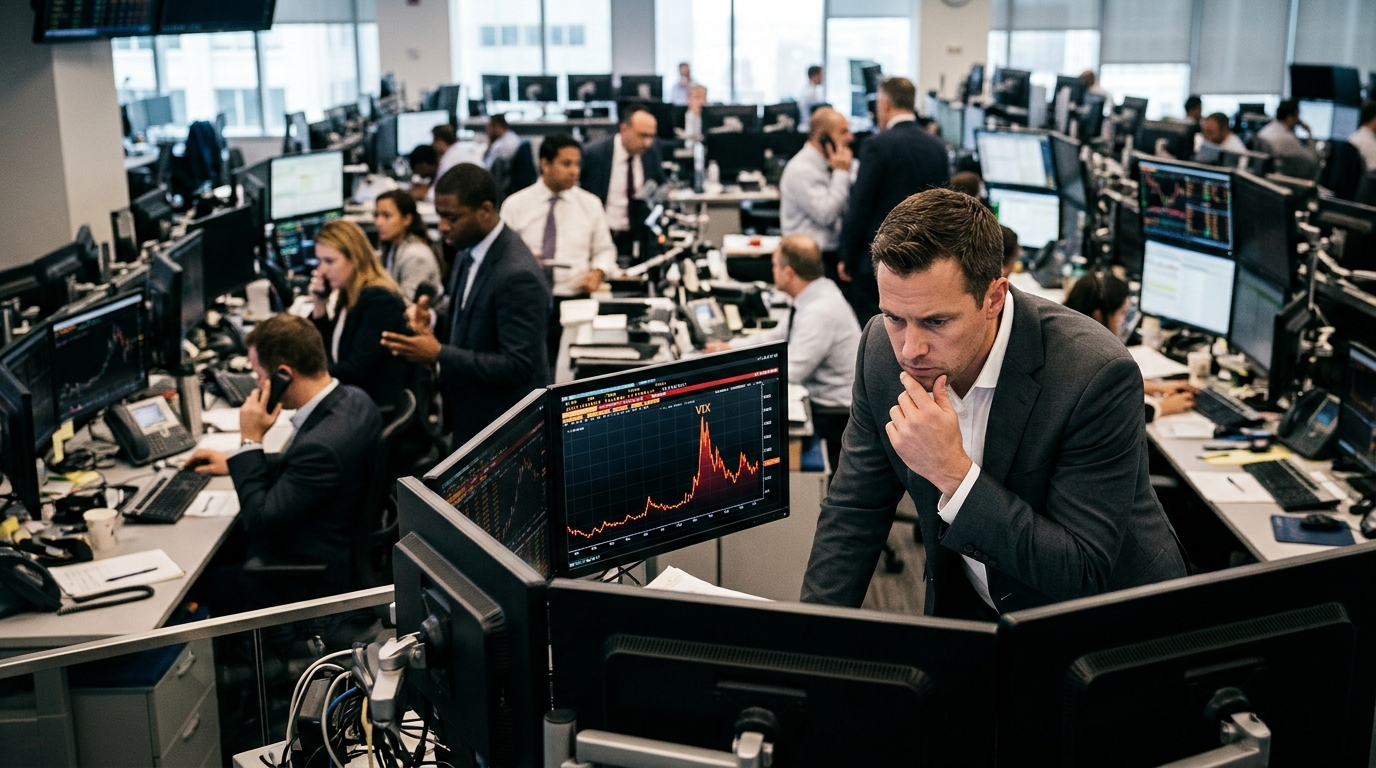
Markets don’t need a reason to adjust risk. They only need a gap between what was priced and what arrived. That gap opened wide on Thursday, and by Friday morning the question is not whether volatility is elevated, it is whether a VIX at 28 is telling the full story.
The Cboe Volatility Index closed at 28.18 Thursday, its highest finish since March 30, as investors sold off AI chip stocks across the market. The VIX gained 11.57 points on the day, the biggest point gain since April 4, 2025, when it added 15.29 points. That is the headline. Here is the problem: the headline undersells the dislocation.
The Gap Between the Number and the Move
With the S&P 500 down about 4.4% on Thursday, there is an argument to be made that volatility should be higher. Traders use a rule of thumb that 16 points for the VIX equates to a 1% daily move in the index. At that ratio, a roughly 3.5% to 4.4% realized decline implies a fair-value VIX closer to 56 to 70. The index closed at 28. The implied-to-realized gap is not a rounding error.
Eight-day realized volatility jumped from 16.03% to 27.72% while VIX jumped from 16.61 to 28.18. At 28.18, spot VIX sat approximately 2% above 8-day realized volatility, 43% above 21-day realized, and 63% above 30-day realized. The front of the curve is not expensive relative to what just happened. It is cheap.
Wednesday set up Thursday’s confusion. With the VanEck Semiconductor ETF down about 3% Wednesday, it was an unusually sharp divergence for equities and implied volatility. Options desks were offside walking into Thursday’s open.
What the Volatility Complex Is Pricing Now
The VIX curve inverted in the sharpest move since April 2025, with one-day vol surging into this morning’s payrolls, leaving the cash curve inverted from one day out to one year. The front VIX future still trades well below spot, so traders are paying up for the next few weeks while pricing partial calm by spring; the November contract, which spans the December Fed meeting, now carries the steepest premium.
Options are pricing approximately 1.49% for today’s payrolls report. As of midday Thursday, nearly 800,000 calls had traded on the VIX, several times the 30-day average, according to Cboe data cited by Capital Digest. Call flow of that magnitude into a spike is not hedging. It is directional positioning on further vol expansion.
The payrolls binary is not just a vol event — it is a Fed policy event. Each jobs number reshapes the rate path in a different direction, and options markets price that fork before economists do.
Thursday’s close surpassed the VIX’s peaks in June and October but stayed below 30, the level that has signaled this cycle’s worst stretches. Adam Turnquist, chief cross-asset strategist at LPL Financial, said volatility has not yet reached the “capitulation or contrarian extremes” that have marked market bottoms. JPMorgan’s Jason Hunter, per one desk note, stays defensive until the VIX clears 35 or the S&P 500 reclaims 7,500 to 7,600.
Carrying Protection Through Payrolls: Defined-Risk Frameworks
Selling every volatility spike has worked for most of 2026. That playbook is now competing with a backwardated curve, elevated skew at 149.37, and a payrolls number that could move the index about 1.5% in either direction before the open settles. The asymmetry has shifted enough to warrant defined-risk structures rather than naked short-vol positions.
Bull case (vol compression, payrolls in-line): If you believe the spike exhausted itself and payrolls land near consensus, a defined-risk short-vol position via an SPY put spread sale, selling the November 540/525 put spread, collects premium while capping the worst-case loss at the width of the spread. Break-even sits well below Thursday’s close.
Bear case (vol expansion continues): For traders expecting further deterioration toward the 7,200 SPX level that JPMorgan flagged as an entry point, a long UVXY call spread captures convexity with defined downside. The backwardated curve means UVXY carries positive roll while the structure is in place, reducing the cost of carry relative to typical contango environments.
Neutral case (payrolls binary, direction unclear): A short-dated SPX iron condor, selling the wings around the implied 1.49% expected move, monetizes the vol premium if the number lands inside the range. Risk is defined on both sides. Given that the VIX is already elevated relative to its 30-day realized base, premium sellers have more edge than they did a week ago.
Risk Factors and Forward Outlook
Funds that size positions by volatility have to cut exposure as the VIX rises, so bounces stay fragile until it settles. That mechanical selling pressure argues against assuming Thursday’s low is a clean floor. Since 1990, the VIX has risen 40% or more in a single day 24 times; a month later the S&P 500 was higher in 18 of those cases, and a year later it was up in 22 of 24. History favors the bulls over a medium-term horizon. The next 48 hours are a different question.
Action Checklist
- Confirm payrolls consensus range before entering any directional structure; the options market implies a 1.49% SPX move at the open.
- Check whether VIX spot clears or rejects the 30 level after the number; a close above 30 shifts the regime call toward further hedging.
- For short-vol bias: use defined-risk spreads only; naked short puts carry unlimited downside in a backwardated, elevated-skew environment.
- For long-vol bias: UVXY call spreads benefit from positive carry in backwardation; size to risk, not to conviction.
- Monitor the November VIX futures contract relative to spot; a narrowing of the spot-to-futures gap signals vol compression and supports a mean-reversion trade.
- Revisit positions if the S&P 500 closes below 7,200 or above 7,600; both levels represent structural decision points cited by JPMorgan’s desk.