The most interesting thing Anthony Noto announced Monday was not the $25 billion. It was the sentence that came after it.
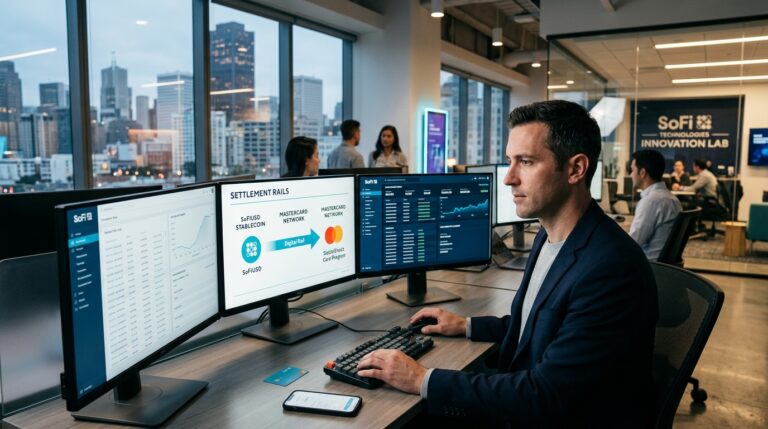
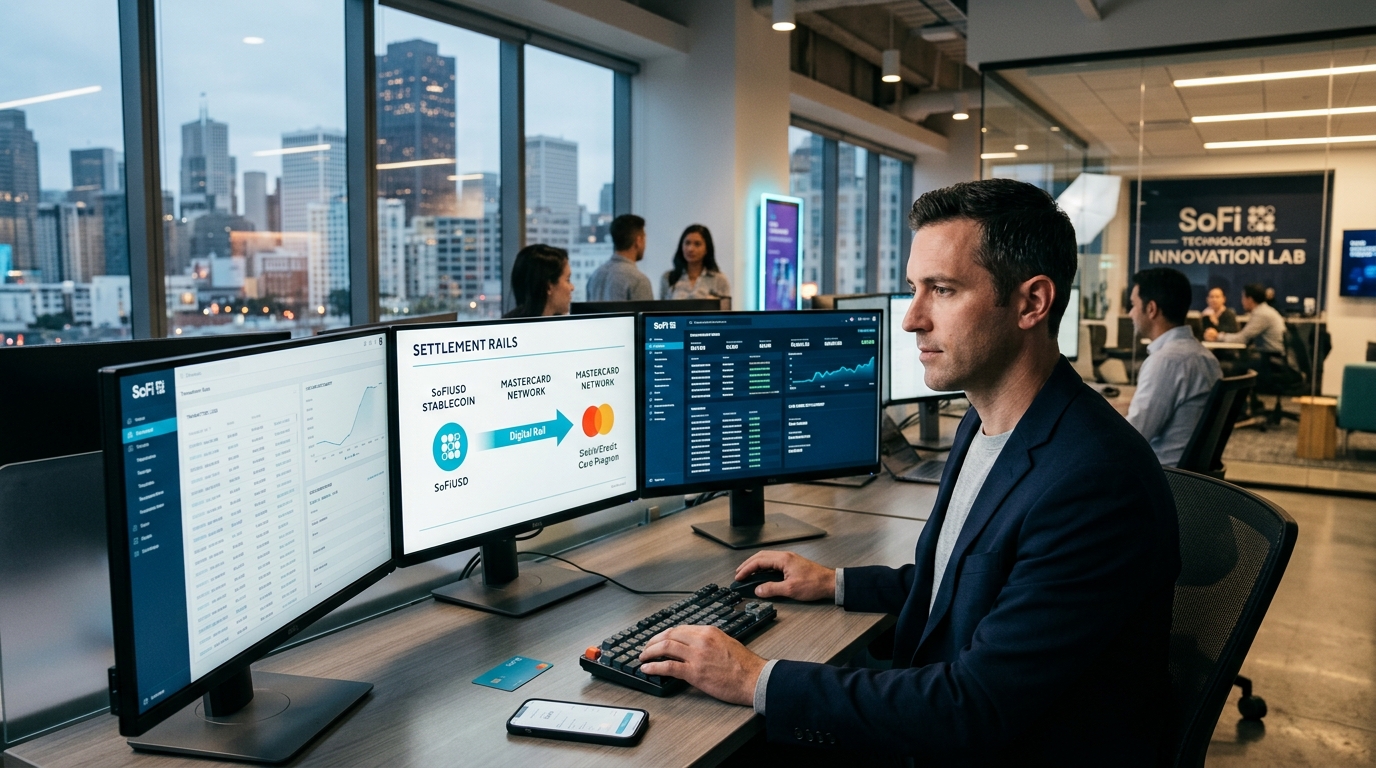
SoFi Technologies and Mastercard said stablecoin settlement is now live across SoFi Bank, N.A.’s debit and credit card program, bringing settlement through SoFiUSD, which SoFi says is issued by a federally regulated bank, to Mastercard’s global payments network. SoFi also said SoFiUSD is the first stablecoin issued by a nationally chartered bank, and that the full card program, which SoFi expects to exceed $25 billion in annualized volume, is migrating to it. That is the headline most outlets ran. Here is the part worth dwelling on: SoFi said it plans to offer stablecoin settlement to other issuing banks through the Galileo platform, which means the $25 billion figure reflects only SoFi’s own card volume today.
That is not a lender talking. That is an infrastructure company positioning itself to collect rent from competitors.
SoFi says SoFiUSD is issued by SoFi Bank, N.A., an OCC-regulated insured depository institution, and is fully reserved 1:1 by cash or cash equivalents for redemption. The legal foundation matters here. The GENIUS Act, signed into law on July 18, 2025, created a federal framework for regulating payment stablecoins in the United States. SoFi moved faster than almost anyone. The company launched SoFiUSD in December 2025, describing it as the first stablecoin issued by a U.S. nationally chartered, FDIC-insured bank on a public, permissionless blockchain.
The merchant value proposition is concrete. In its announcement, SoFi said merchants do not need to hold stablecoins, build new infrastructure, or change how they operate. Through SoFi’s Big Business Banking platform, SoFi said merchants can receive settlement funds instantly in a SoFi Bank account and withdraw to cash around the clock at zero cost. The practical gain over traditional card settlement is intraday finality on weekends and holidays. For large retailers managing weekend cash flow, that is not a minor convenience.
SoFi also said the product is not limited to use by SoFi Bank, and that it is in active discussions with large U.S. merchants about stablecoin-based settlement arrangements. Galileo already powers financial infrastructure for what SoFi has described as 134 million accounts globally. The distribution network exists. The regulated stablecoin now exists. The question is whether SoFi can convert those conversations into contracts before a JPMorgan or a Fiserv decides this is worth owning.
The risks are real. SoFi is a mid-sized lender with a market capitalization well below the incumbents it is trying to undercut. In its quarterly filing, SoFi reported net crypto revenue of $2.0 million for the six months ended June 30, 2026, a number that illustrates how early-stage this revenue stream remains. Regulatory posture could shift. Larger banks could launch competing stablecoins under the same GENIUS Act framework and absorb the market SoFi is seeding. Mastercard, for its part, has been explicit that it intends to support multiple regulated stablecoins for settlement. In a June 2026 announcement about expanding stablecoin settlement, Mastercard said the supported list includes Circle’s USDC, Paxos-issued PYUSD, USDG and USDP, Ripple’s RLUSD, and SoFiUSD. First-mover advantage in payments infrastructure is real but not permanent.
What separates this from prior fintech ambitions is the regulatory moat SoFi has constructed. A non-bank cannot replicate SoFiUSD. The OCC charter and the reserve posture SoFi describes, including reserves primarily held as cash balances at the Federal Reserve, are not features a crypto-native competitor can assemble quickly. SoFi and Mastercard also said they will explore additional opportunities for SoFiUSD settlement, including cross-border payments, remittances, and other money movement use cases. Each new corridor is another potential licensing fee.
Noto described going from idea to live product in six months. The more consequential timeline is what the next six look like, specifically, whether a multinational retailer or a regional bank signs onto Galileo’s stablecoin rails. That would confirm SoFi is building something the incumbents eventually have to rent, rather than simply running a better back office for its own cards.