Urgent Alert
Your Retirement Is at Risk – Here’s How to Protect It
Trump preserved a powerful IRS loophole for retirees, but the window to use it could be closing fast.
If you have a 401(k), IRA, or TSP – and you haven’t taken this one step – your retirement savings could be wiped out before you ever touch them.
President Trump’s return has unleashed historic economic reforms – extended tax cuts, stronger dollar policy, and a renewed push for American wealth. For retirees, this could mean more money in your pocket.
But here’s what most people aren’t being told: the same market forces being unleashed could devastate traditional retirement accounts that aren’t properly protected.
One bad year. One market crash. One unexpected crisis.
That’s all it takes to wipe out 30 years of savings – with no way to get them back.
There is a way to protect your savings – and Trump fought hard to keep it available to you.
It’s a little-known IRS loophole that lets you move your retirement savings – tax-free and penalty-free – into a time-tested asset that holds its value when markets collapse.
Everything you need to know is laid out in the 2026 Wealth Protection Guide from American Hartford Gold. Download your free copy here!
Inside, you’ll learn exactly how the loophole works, who qualifies, and the specific steps to take before the opportunity closes. This guide is free, but it won’t be available forever. Claim yours now before it’s gone!
Yes – Send Me the FREE 2026 Preservation Guide!
Free to Claim – Includes Step by Step Rollover Instructions
100% Free. No credit card. Ships to your inbox instantly.
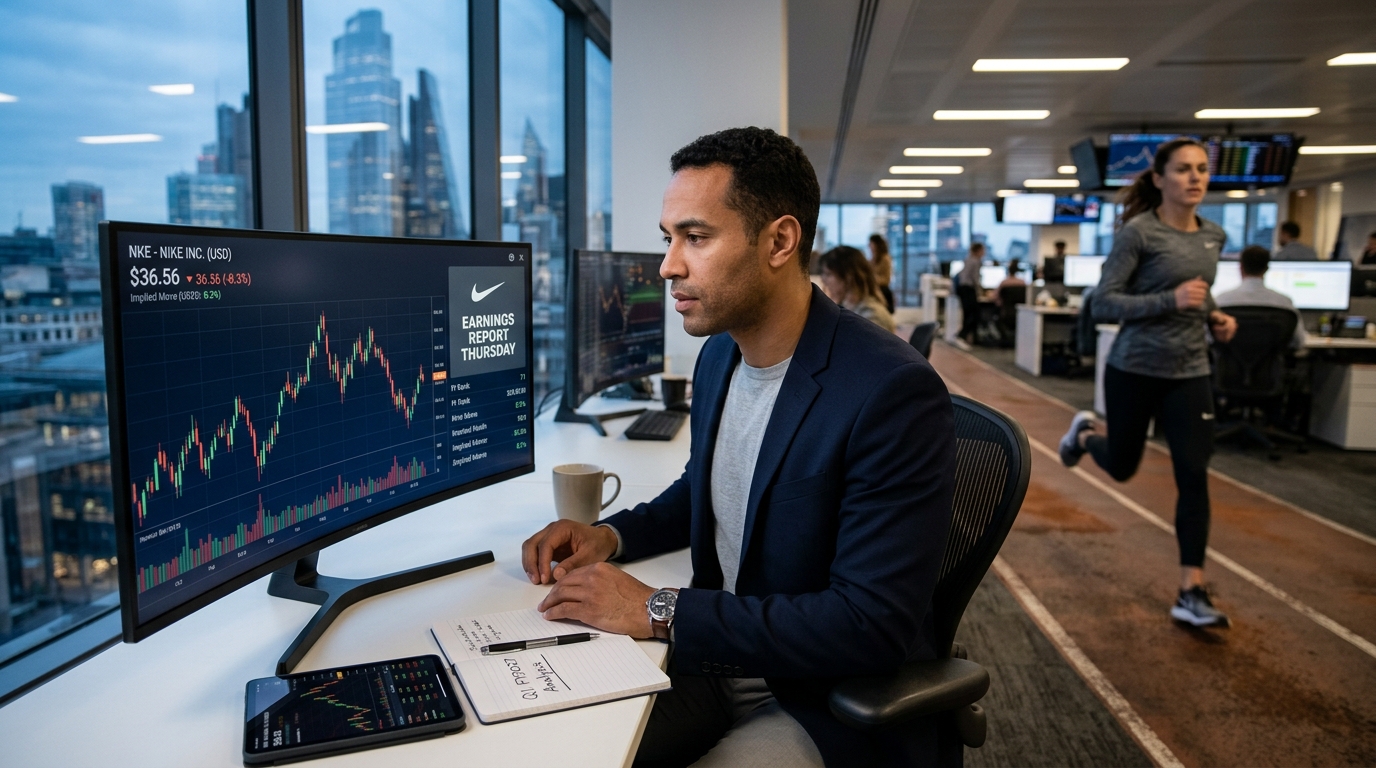
Nike Reports Thursday at $36. The Options Market Is Pricing a Move the Stock Has Repeatedly Exceeded.
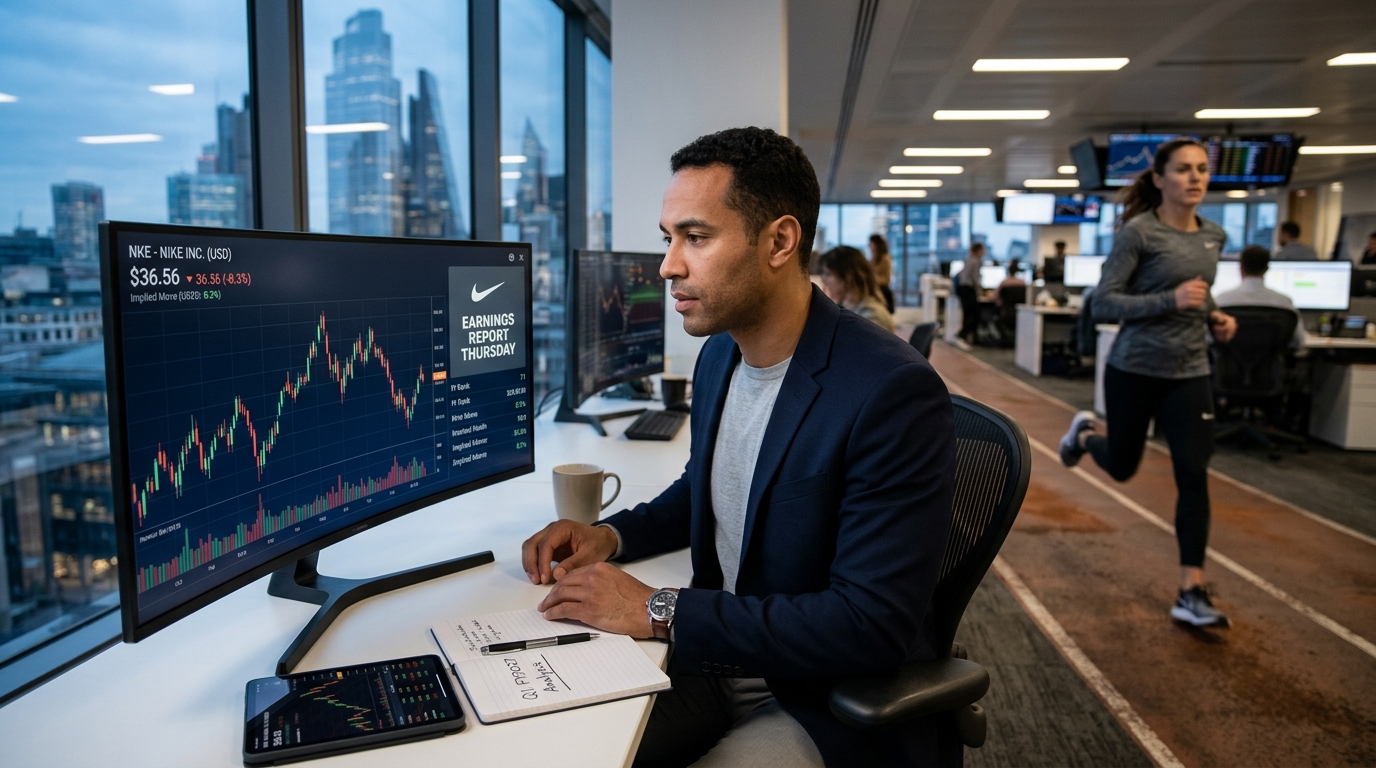
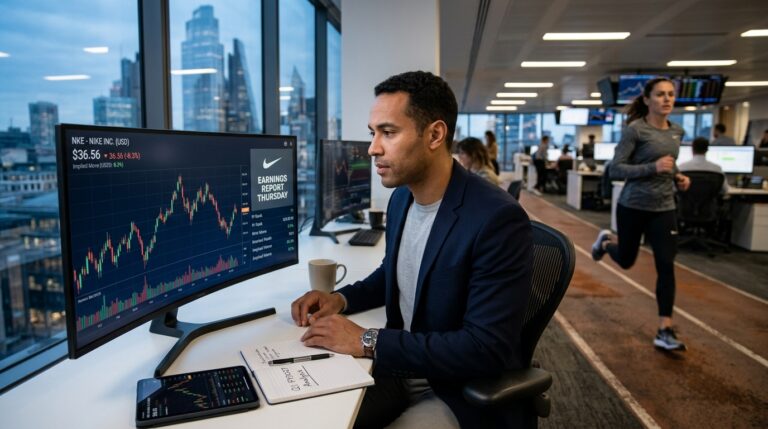
Nike closes Monday at $36.56 on a down Dow day, gaining 2.27% while the broader index retreats. File that away. The market is not pricing NKE as a broken brand on Monday. It is pricing it as a brand that reports Thursday after the close, with a binary outcome wide enough to demand respect.
The question is not whether Nike is struggling. That answer is already in the stock. The company’s share price has fallen roughly 80% from its November 5, 2021, all-time high. At $36 and change, the world’s largest athletic brand trades at a valuation the market typically reserves for retailers in structural decline, not for a franchise that still generates $46 billion in annual revenue. Whether that discount is warranted or excessive is precisely what Thursday’s print will begin to answer.
The Numbers Coming In
Full-year fiscal 2026 revenues were $46.4 billion, flat on a reported basis and down 2% on a currency-neutral basis. Nike Direct revenues were $17.7 billion in fiscal 2026 compared to $18.8 billion in fiscal 2025, primarily driven by a decrease in traffic. Gross margin in fiscal 2026 increased 20 basis points to 42.9%. That margin expansion is the one constructive data point in an otherwise flat year, but it came with an asterisk: fourth quarter net income rose 407% to $1.1 billion, but the gain included a $0.52-per-share benefit tied to the expected recovery of IEEPA tariffs.
Ahead of the release, analysts expect the company to report diluted EPS of 44 cents, down 10.2% from 49 cents in the year-ago quarter. Jefferies sits above the Street: analyst Randal Konik forecast sales of $11.5 billion and EPS of $0.48, compared to consensus estimates of $11.3 billion and $0.44 EPS. Bank of America sits below it. Bank of America analyst Lorraine Hutchinson downgraded Nike stock to Underperform from Neutral and lowered the price target to $30 from $47, cautioning investors about rising risks to Nike’s business and expecting the turnaround to take longer than expected.
Why This Quarter Is Different
Fiscal Q1 FY2027 is the first full quarter absorbed under the current tariff schedule. Nike sources heavily from Vietnam, Cambodia, and Indonesia. The U.S. set a 19% tariff on Cambodian imports, down from a previous 49%. Tariffs on goods imported into the U.S. from Indonesia stand at 19%. Tariffs on goods imported from Vietnam currently stand at 20%. Management guided for the pressure: Nike expects revenue to decline in the low- to mid-single digits through the first two quarters of fiscal 2027, citing a more cautious consumer and softer sell-through trends.
Overlay that guidance against a University of Michigan consumer sentiment reading of 48.1 in September 2026, and the challenge becomes concrete. Discretionary athletic footwear priced above $100 does not sell well when consumers rate their own financial expectations that poorly. Sportswear and Jordan Streetwear remained the weak spots in FY2026, while North America stayed the strongest region and Converse revenue fell 31% for the year.
There is also a brand signal worth tracking. Reuters reported on September 18, 2026 that Kylian Mbappé ended his partnership with Nike to join On as the Swiss brand pushes into football. Mbappé’s departure adds pressure during a turbulent stretch for Nike. Management chose not to renew. Whether that decision reflects disciplined capital allocation or competitive retreat is a question the market will eventually price.
Options Market Analysis
NKE carries an IV of 47.1, IV rank of 71, and IV percentile of 81 into the event. Premium is elevated relative to its own one-year history. The options market is pricing in about an 8.3% move in either direction on Q1 FY2027 earnings. That implied move is not cheap. It is also potentially not enough. Nike’s past four post-earnings moves averaged 9.34% in absolute terms, and the implied move sits below that average. The past reactions ranged from 4.90% to 15.51%. At $36.56, an 8.3% swing defines a range of roughly $33.52 to $39.64.
Options flow heading into Monday’s session showed mixed directional sentiment, roughly in line with average contract volume. That does not signal conviction. It signals a market waiting for data.
Structured Trade Framework
Bull case: If you believe the Jefferies read is correct, that revenue clears $11.5 billion and EPS reaches $0.48, a defined-risk call spread targeting the $39 to $41 range captures the breakout through the upper bound of the implied move. Define maximum risk to premium paid.
Bear case: For traders expecting the tariff burden to bite margins harder than consensus models and the consumer sentiment backdrop to suppress Direct revenues further, a defined-risk put spread from $35 down to $32 sits outside the lower implied move threshold and limits exposure to premium paid. Hutchinson sees downside risk to earnings estimates and valuation as the weakness in the company’s classics business continues to overshadow its innovation.
Neutral case: Given the historical tendency for realized moves to exceed the implied straddle, an at-the-money long straddle on the October expiry captures directional optionality in either direction. The cost is elevated premium; the thesis is that the market has again underpriced the actual move.
Action Checklist
- Confirm the implied move in October expiry at-the-money straddle before entry; 8.3% translates to approximately $3.03 at current levels
- Compare straddle cost against the four-quarter realized move average of 9.34% to assess whether IV is rich or cheap relative to history
- For bear structures, define maximum loss to premium paid; NKE has demonstrated willingness to gap through prior support levels
- Monitor gross margin guidance language on the earnings call: management had guided for gross margin expansion to begin in the first quarter of fiscal 2027, driven by cost actions taken in the supply chain
- Watch commentary on Nike Direct traffic and sell-through trends as the clearest leading indicators for FY2027 recovery credibility
- Nike will lay out its next phase of growth strategy at an Investor Day scheduled for November 16 and 17, which may anchor any post-earnings rally or extend any decline