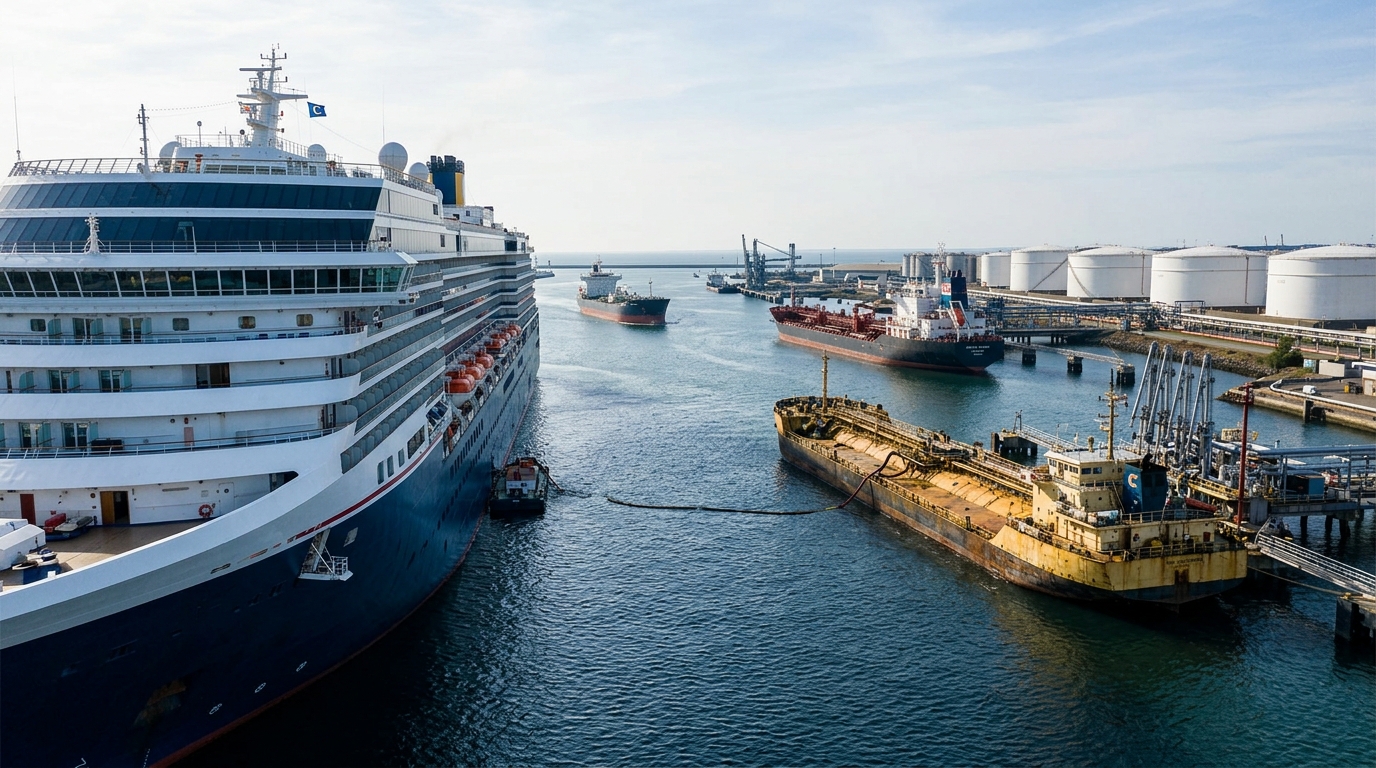
Carnival Corporation prints its fiscal third quarter this morning before the open. Consensus sits at $1.35 to $1.36 in adjusted EPS on roughly $8.36 to $8.39 billion of revenue, with revenue expected to be up year over year. The stock entered the week at $21.80, just above its 52-week low of $21.45, and is down roughly 27% year to date from a February high of $34.03. A beat on those EPS numbers will not be the story.
The story is $107 oil and what management says about it.
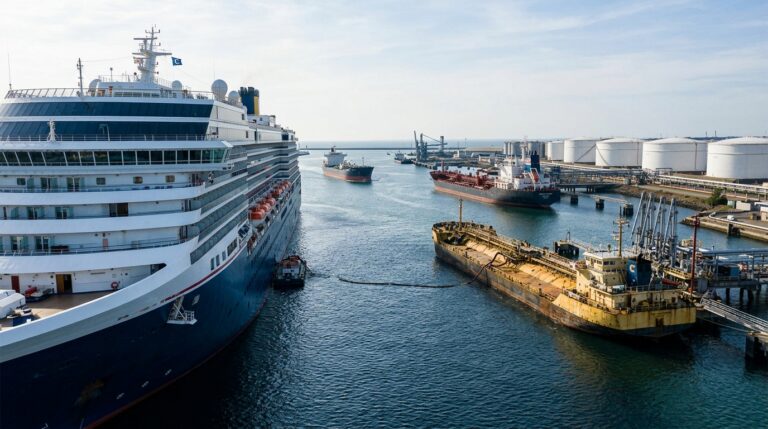
When Carnival issued Q2 guidance in June, the fuel model assumed Brent averaging $85 per barrel through the third quarter and $80 per barrel in the fourth. Brent closed Monday at roughly $106.89, and the driver is not a demand shock. It is geopolitical. US-Iran tensions over the Strait of Hormuz have kept a risk premium embedded in crude since mid-summer, and Trump’s rejection of Tehran’s latest reopening proposal over the weekend extended it. Every $10 per barrel above the company’s fuel assumption translates to roughly $160 million in additional cost, or about $0.11 per share, over the remaining year. The gap between $85 and $107 is not a rounding error.
What the Numbers Actually Show
Q3 adjusted EBITDA guidance stands at $2.88 billion, down from $2.99 billion in the year-ago quarter when net margin ran 22.7%. The consensus EPS decline of 4.9% year over year, from $1.43 to $1.35, is almost entirely a fuel story. The consensus Q3 EPS estimate was revised down 11.8% over the past 30 days, driven by analyst model adjustments for higher fuel assumptions rather than any deterioration in bookings. Demand, by every measure Carnival controls, is exceptional: customer deposits reached $9.0 billion as of late June, about $450 million above the prior-year record, and 93% of 2026 capacity was already booked. Carnival has beaten the Zacks consensus in each of the trailing four quarters, with an average surprise of 18.2%.
The Q2 report demonstrated exactly why beating on EPS is insufficient. Adjusted EPS of $0.41 topped the $0.33 estimate by $0.08 and revenue of $6.7 billion was a record. The stock still fell nearly 6% on the reporting session because the Q3 EBITDA guidance came in below expectations and management cut full-year normalized yield growth to roughly 2.25%, about a point below prior guidance, citing Middle East disruption to Mediterranean sailings. A beat without a guide raise will likely produce the same outcome today.
The Guidance Test
In June, CEO Josh Weinstein called the Mediterranean yield damage “already proving to be transitory.” Today’s Q3 report is the first hard data point on that claim. There are two specific lines to watch. First, whether Q3 adjusted EBITDA hits or holds the $2.88 billion target, given that Brent ran well above the embedded fuel model for the entire quarter. Second, what the Q4 and full-year EPS guide implies about fuel assumptions. The company’s existing full-year adjusted EPS guidance of approximately $2.22 was built on Brent averaging $80 per barrel in Q4. That assumption is now nearly $27 below spot. Management will need to either update the fuel bridge or explain why the efficiency gains and hedges absorb the gap. Fuel consumption per ALBD improved 5.6% in Q2, which partially offset a nearly 30% year-over-year rise in fuel price, but at $107 Brent, that buffer is getting thin.
Options Market Analysis
CCL’s implied volatility heading into the print is approximately 47%, with an IV Rank near 52%, placing current premiums in the middle of their 52-week range rather than at a historically elevated extreme. That is a critical asymmetry: the IV Rank does not scream expensive, but the guidance risk from a $22-per-barrel fuel miss is not adequately reflected in a midrange reading. For reference, at an IV of 47% on a $22 stock, the at-the-money straddle prices an expected move of roughly plus-or-minus 8% to 10% through the October expiration, consistent with CCL’s historical earnings reaction pattern. In Q2, the actual move was nearly 6% in a single session. The floor scenario, a beat on EPS plus a downward Q4 revision, could produce a move at the higher end of that range.
Structured Trade Framework
For traders expecting management to hold the Q3 EBITDA target and guide Q4 with a credible fuel bridge, a defined-risk bull structure would be a call spread, buying the October $23 call and selling the October $25 call, risking the net debit. The thesis: a modest beat plus unchanged full-year guidance on the back of hedges and efficiency gains could recover the gap to $23 to $24 resistance.
For traders expecting the guidance cut that Q2 foreshadowed, a defined-risk bear structure would be a put spread, buying the October $21 put and selling the October $19 put. At $21.45 as the 52-week low, downside through that floor on a negative Q4 guide is plausible. Risk is the premium paid.
For a neutral view, selling an iron condor bracketing the expected move, roughly the $19/$21 put spread against the $23/$25 call spread, captures premium in a midrange IV environment where the IV Rank of 52% does not justify net long volatility.
Risk Analysis and Forward Outlook
Sector peers face identical pressure. Norwegian Cruise Line already reduced its full-year adjusted EBITDA guidance to $2.48 to $2.64 billion and cut EPS guidance to $1.45 to $1.79, citing fuel and softer top-line performance. Royal Caribbean has hedged more aggressively and trades at a forward P/E of roughly 17x. CCL, by contrast, trades at approximately 8.78x forward earnings, far below the industry average of roughly 15x, a valuation that either prices in persistent fuel drag or represents the asymmetric opportunity, depending entirely on how Q4 guidance lands this morning.
Action Checklist
- Watch Q3 adjusted EBITDA vs. the $2.88 billion target before crediting or faulting the EPS headline
- Isolate management’s Q4 fuel assumption in the updated guidance bridge. Any figure below $100 per barrel on Brent will require scrutiny
- Listen for specific language on Mediterranean yield recovery in Q4: “firming” is constructive; “still soft” means the transitory thesis slipped a quarter
- Assess IV crush post-announcement before entering or holding any options position; a midrange IV Rank of 52% means post-earnings vol compression is probable regardless of direction
- RCL and NCLH will move in sympathy: watch the spread between them and CCL as a sector signal on whether the reaction is company-specific or macro-driven