October 1, 2026
Bonus Content: Brazil Votes Sunday. Your Ibovespa Position Cannot.
Nobody looked under these rocks for 130 years. Until July.
On 3 July a helicopter set a drill rig down on a mountainside where the last people to dig worked by candlelight.
Eight weeks later: eight holes collared, seven completed, three targets. Core at the lab, first assays expected in the fourth quarter.
Under the rig sits a 37,000-hectare block of an old silver district that has seen almost no modern drilling.
The clues that drew the team are historic surface samples running into thousands of grams of silver a tonne.
Brazil Votes Sunday. Your Ibovespa Position Cannot.
Markets don’t need certainty. They need a manageable range of outcomes. Brazil on Sunday offers the opposite: a binary, unhedgeable overnight event that lands while U.S. traders are asleep and the Ibovespa is closed. That is not a market to hold directionally. It is a market to define your risk before the bell on Friday.
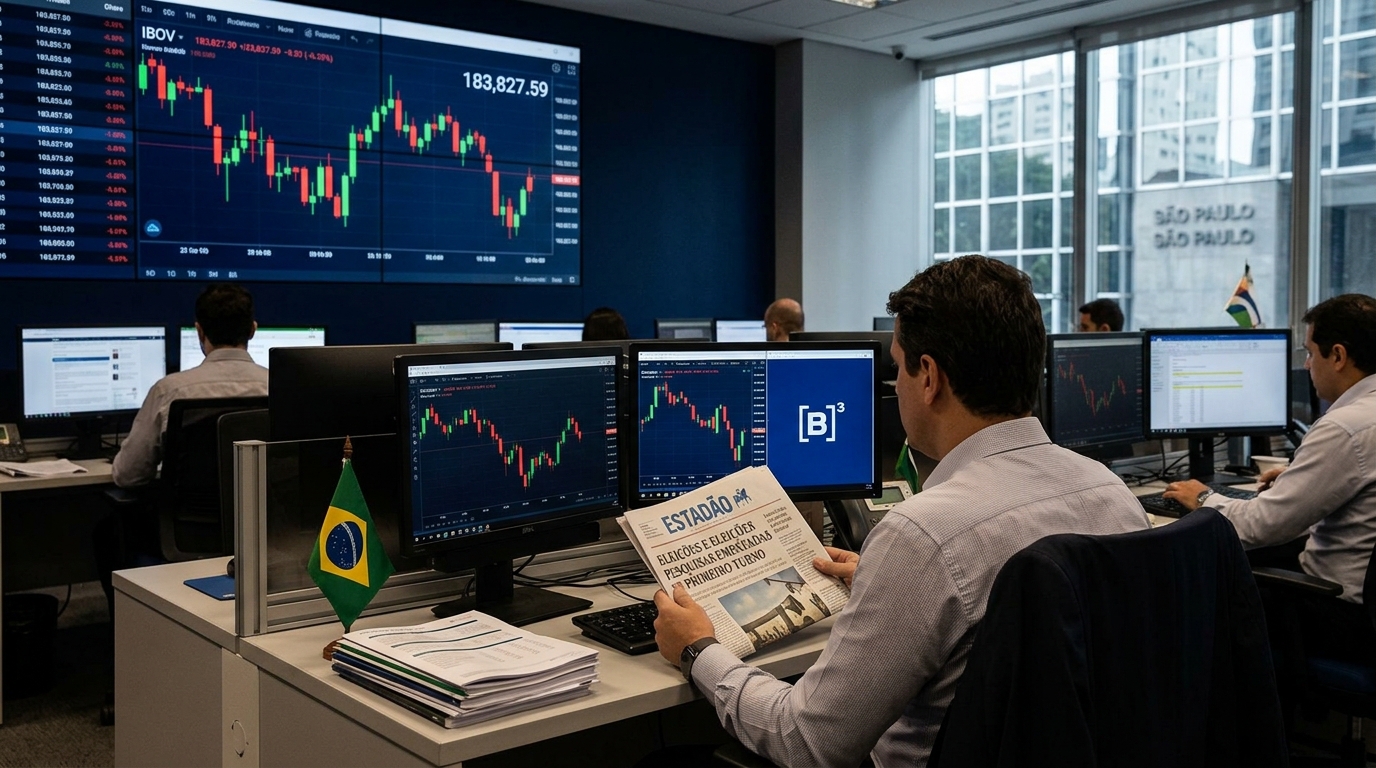
Brazil’s Ibovespa closed 0.46% higher at 183,827.59 points on Tuesday, September 29, ending a four-session losing streak. The recovery was narrow. Banks led it, with Banco do Brasil rising 2.56% and Petrobras preferred shares gaining 0.78%. Vale dragged the other direction, falling 2.18%, and CSN fell 9.85% as shares reacted after CSN Mineração cut its 2026 production guidance. That internal divergence matters: the Ibovespa’s rebound masked sectoral fault lines that a contested election result could rip open.
The Political Math
As the October 4 first round draws closer, President Luiz Inácio Lula da Silva is in a tight contest with Flávio Bolsonaro, son of former President Jair Bolsonaro. The runoff is a statistical tie: Reuters reported Sept. 28 that a Quaest survey had shown Flávio 42% to Lula’s 41% in a simulated runoff, while a BTG Pactual/Nexus poll put Lula ahead 46% to 44% in another runoff scenario, both inside the margin of error. Prediction markets have at times leaned toward the challenger over the incumbent. If no candidate wins a majority of valid votes in the first round, a runoff will be held on October 25.
The rate market has been parsing candidate differentiation all week. At Tuesday’s settlement, the January 2029 DI contract ended around 13.8% after a notable daily decline, a move Brazilian financial press linked to investors assigning a higher probability to a Bolsonaro-aligned win, given expectations of tighter fiscal posture. The Selic stands at 13.75% after the central bank’s fifth consecutive cut on September 16, reducing from a recent peak of 15.00%. The curve is not positioned for fiscal expansion. A Lula mandate with a loose budget could reprice the long end hard.
Options Market: EWZ Signals Maximum Alert
This is not about which candidate wins. It is about the gap risk that neither candidate eliminates before Monday’s open.
EWZ, the iShares MSCI Brazil ETF, ended September 30 with implied volatility at elevated levels, consistent with the top end of its one-year range on common IV-rank metrics. EWZ closed at $36.47 on September 30, with a 52-week range spanning from $28.66 to $42.02. When IV rank is pinned near the top of its range, premium sellers are harvesting maximum juice; premium buyers are paying up for protection that is, by definition, priced at its ceiling.
The skew has a clear tell. Downside puts carry higher implied volatility than equivalent calls, consistent with the hedging behavior you’d expect days before a contested election in an emerging market with USD/BRL near 5.18 and the US 30-year Treasury yield recently pushing above 5.6%.
Structured Trade Framework
Bull case (Bolsonaro first-round surprise or runoff odds sharply shift): A defined-risk long on EWZ, using a call spread in the October 25 expiration, contains the cost of entry given elevated IV. For traders expecting the fiscally restrictive scenario to price in, a $37/$40 call spread captures the upside without naked exposure to a gap lower. Maximum loss is the debit paid.
Bear case (Lula wins outright or runoff outcome spooks fiscal hawks): A put spread in the October expiration, positioned below current levels near $34/$31, isolates the downside without requiring a crash. With IV near a one-year extreme, buying naked puts is expensive; the spread structure reduces cost basis materially.
Neutral/volatility case: With IV near a one-year peak, a short strangle or iron condor in the November cycle captures premium decay after the election resolves. This is the textbook post-event structure when you expect volatility to collapse regardless of direction. Manage at 50% of maximum profit or 21 days to expiration.
Risk Analysis
The primary risk for any position is the gap. Brazil’s market opens Monday. In the U.S., equities and listed options trade on Columbus Day (October 12, 2026), but U.S. bond markets are typically closed, which can distort the usual cross-asset feedback loop around rates. PBR, VALE, and ITUB, which together make up roughly 32% of EWZ by weight based on recent holdings data, each carry their own commodity and sector sensitivity that amplifies any directional move in the index.
Secondary risk: the election goes to a runoff without a clear momentum shift, keeping IV elevated through October 25. In that scenario, premium decay is slower and both the bull and bear spread structures give back value while you wait.
Forward Outlook
Two dates own the calendar: October 4 and October 25. The Ibovespa near 183,828 and USD/BRL near 5.18 have already partially priced a Bolsonaro-Lula runoff as the base case. What they have not priced is a first-round surprise in either direction, and they cannot, because the polls provide no conviction to do so.
Action Checklist
- Verify EWZ position size before Friday’s close. Weekend gap risk is unhedgeable once markets shut.
- If holding EWZ directionally, consider converting to a defined-risk spread structure before end of day Friday to cap downside exposure across the gap.
- Monitor the January 2029 DI contract Monday morning as the first real-time read on how rate traders are interpreting the first-round result.
- For post-event premium sellers, the November cycle strangle becomes actionable after Sunday’s result removes the binary catalyst and IV begins to compress.
- Track PBR and VALE individually: each carries commodity price risk that can diverge from the broad Ibovespa move, creating spread opportunities regardless of the election outcome.