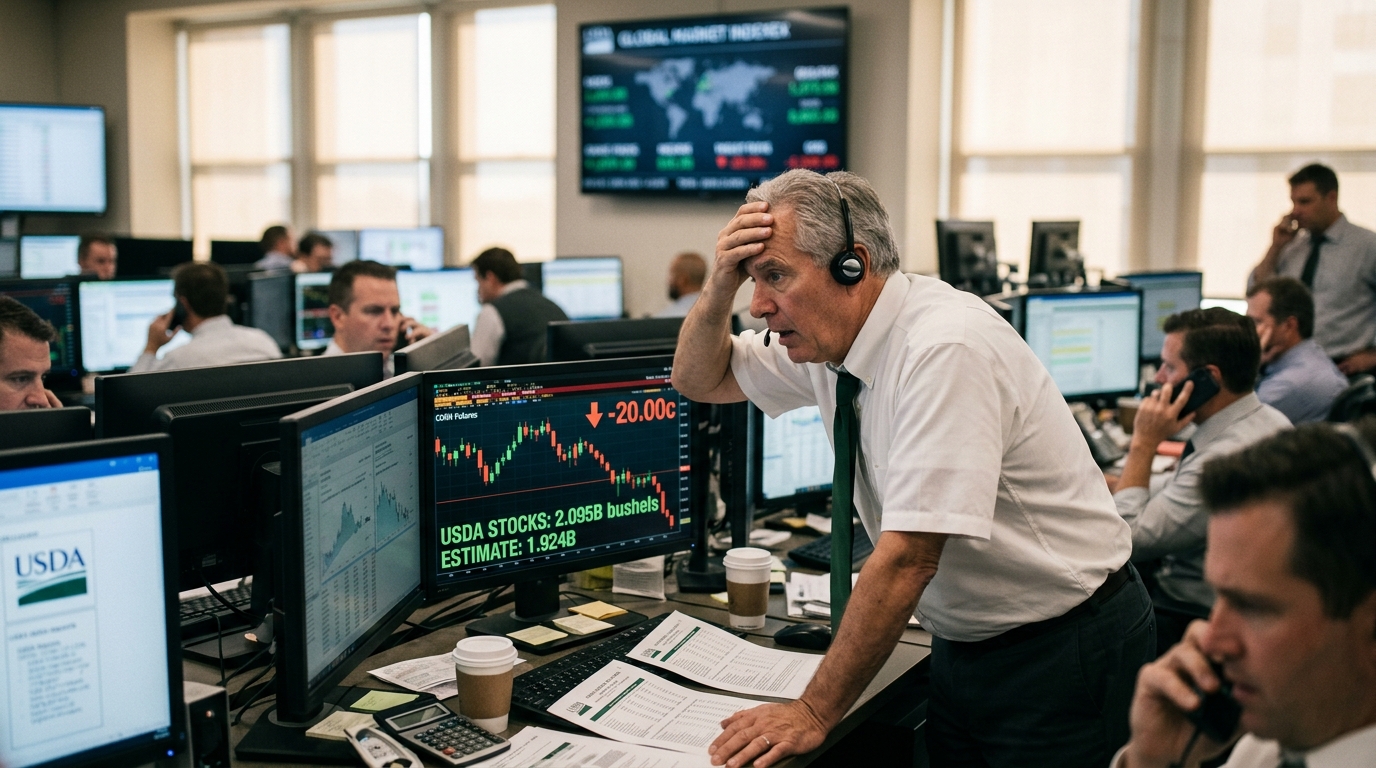
The September 30 USDA Grain Stocks report did not disappoint bears. It shocked them into being bulls, temporarily, before the math took over. USDA estimated U.S. corn stocks in all positions at 2.095 billion bushels as of September 1, up 35% from a year earlier. Analysts surveyed by Dow Jones had expected 1.924 billion bushels, with estimates running from 1.860 billion to 2.005 billion. The actual result came in 90 million bushels above the top of that range. Not above the average. Above every single trade guess.
Corn for December delivery fell 4% to $5.01¼ a bushel on the Chicago Board of Trade Wednesday after the USDA released its figures. The bearish stocks number landed on a fund net long of more than 414,000 contracts, and RCM Alternatives’ Doug Bergman said that combination positions the market for a larger pullback as weak hands get forced out. The Q3 rally, which had carried corn up 15% for the quarter, closed in a single session.
What the Numbers Actually Said
Old-crop corn stocks totaled 2.10 billion bushels, up 35% from a year ago, coming in above the high end of pre-report estimates. Off-farm stocks rose 44% from a year ago, while on-farm stocks climbed 22%. The geographic distribution underscores the concentration of supply. Iowa held 415.5 million bushels, up 23%. Illinois climbed 53% to 252.9 million bushels, and Nebraska rose 50% to 248.1 million.
Quarterly corn stocks were much larger than expected at 2.095 billion bushels, 35% above the prior year, implying slower demand than the market had priced in. The September report closes the books on the 2025/26 marketing year, meaning these stocks become beginning stocks for 2026/27. That matters for every forward price estimate through next year.
Why the Reaction Was This Large
Markets do not react to data. They react to the distance between data and expectation. This is not about how much corn there is. It is about how much more corn there is than the crowd believed.
The secondary restraint on further selling is weather. Rain from the remnants of Hurricane Polo is spreading from the Southwest through the Plains into the Midwest, carrying flooding risk that is extending corn and soybean harvest delays. Slower harvest means slower physical supply arriving at elevators, which cushions basis but does nothing for futures fundamentals.
Sector Exposure: ADM, BG, MOS, CF, DE
The corn selloff is not isolated to futures. Grain processors and agricultural input names move with corn volatility. Archer-Daniels-Midland (ADM) and Bunge (BG) process and trade physical corn; lower prices compress crush margins when input costs reset faster than contracted sales. Mosaic (MOS) and CF Industries (CF), as fertilizer suppliers, face a more nuanced read: lower corn prices reduce farmer income and can delay input purchasing decisions for the 2027 planting season. Deere (DE) carries similar downstream exposure through equipment demand tied to farm revenue.
Options Market Structure
ADM’s 30-day implied volatility sits at 31%, with an IV rank of 34%, placing current premiums in the middle of their 52-week range. ADM’s expected move through October 16 is 7.0%, implying a range of roughly $79.26 to $91.11. For MOS and CF, September data showed elevated IV, with MOS 30-day IV at 47 against a 52-week range of 32 to 63, and CF Industries at 46 against a range of 27 to 68. Neither is at extremes, which means premium is neither cheap enough to justify outright long volatility nor rich enough to favor aggressive short premium structures.
Structured Trade Framework
Bull case: If you believe Hurricane Polo’s harvest disruption extends through mid-October and tightens physical supply faster than the futures market implies, a defined-risk long structure on corn proxies like ADM or CORN ETF through a call debit spread targets a retest of pre-report levels near $5.20 December corn.
Bear case: For traders expecting fund liquidation from the 414,000-contract long to continue over the next two to three weeks, a put spread on ADM or BG below current support offers defined downside exposure. With IV rank at moderate levels, buying defined risk is more favorable than naked short delta.
Neutral case: A short strangle on either ADM or MOS with October expiration captures elevated post-report IV as it mean reverts. The risk is a further shock from the October 9 USDA supply and demand update, which is the next scheduled government catalyst.
Key Risk and Forward Outlook
USDA’s updated supply, demand, and production numbers are due October 9, while CONAB’s next look at Brazil is set for October 2026. Both are binary events for corn. The October 9 report will be the first official opportunity for USDA to revise 2026/27 ending stocks higher, which would confirm the bearish stocks read. A weather-driven production cut, on the other hand, could re-anchor prices above $5.20.
Action Checklist
- Verify ADM and BG position sizing against current IV rank of 34%; mid-range premium does not support oversized long volatility bets.
- Mark October 9 USDA supply and demand report as the next hard catalyst.
- Monitor harvest progress weekly. Corn harvest stood at 18% complete as of September 27, in line with the five-year average before Polo’s rains pushed another delay.
- Size any corn-linked equity exposure to the defined-risk side; the 414,000-contract fund long is still unwinding.
- Watch December corn $5.00 as near-term technical support; a close below that level reopens the gap to $4.80.