October 7, 2026
Bonus Content: The Valve Makers Controlling AI’s Next Bottleneck
Dear Reader,
The FDIC invited public comments on renewing its branch-deposit survey.
It received none.
A survey about bank deposits. An opportunity to weigh in. No comments received.
Now another date deserves a closer look.
On October 26, 2026, public-comment windows close on four federal information collections covering bank deposits, financial customer-data security, securities-market activity and institutional trade settlement.
What information do these collections cover?
And what is the public being asked to comment on?
Those are the questions to examine before the windows close.
Our coverage explains the four proceedings and includes a public FDIC exchange about communicating the resolution of major financial institutions.
You can also follow our bank-branch closing counter.
See what’s open for comment before October 26.
Bill Brocius
Author of The Vanishing Dollar and Digital Dollar Exposed
Dedollarize News
The Valve Makers Controlling AI’s Next Bottleneck
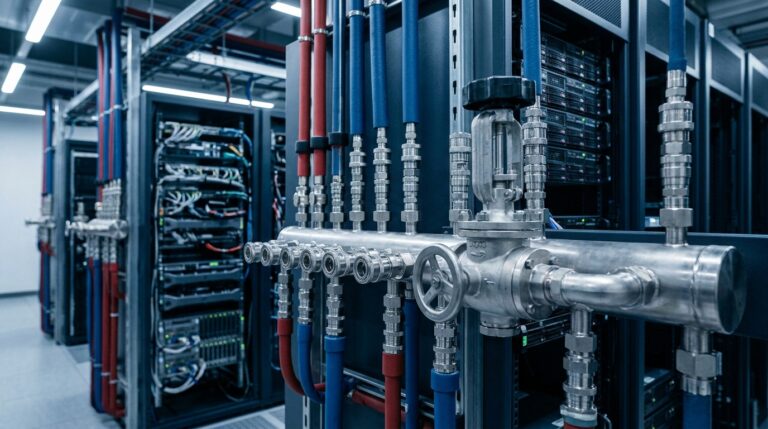
Markets do not need another chip story. They need to understand where the AI buildout actually slows down. Right now, that place is not a fab in Taiwan or a server rack in Virginia. It is a stainless-steel valve, a precision manifold, a certified quick-disconnect fitting.
Goldman Sachs has argued that rising rack power density is forcing data centers toward liquid cooling, turning plumbing, coolant distribution units, and leak detection into gating infrastructure rather than optional upgrades. That rate of adoption compresses a normal infrastructure procurement cycle into something closer to a controlled emergency. The specialized nature of components like precision plumbing and coolant distribution units leads to extended procurement lead times, delaying deployment of essential AI accelerators.
The market still relies on a relatively small pool of qualified suppliers, creating a constrained ecosystem struggling to meet rising demand. Supply-chain resilience, component availability, and standards harmonization will become critical in determining how quickly liquid-cooling technology can scale.
Where the Revenue Is Actually Showing Up
The clearest financial signal comes from Belimo, the Swiss control-valve manufacturer most investors have never heard of. Belimo delivered accelerated sales growth of 29.6% year-on-year in local currencies in the first half of 2026, with data center cooling solutions accounting for slightly more than half of its absolute sales growth. Data centers now represent 23% to 24% of total sales, up from approximately 18% in H2 2025. Control valves, the category that includes the flow hardware embedded in every liquid-cooled rack loop, grew 48.3% in local currencies and now represent 58% of Belimo’s net sales at CHF 389.3 million.
Danfoss tells a parallel story. In 2025, data centers accounted for about 7% of Danfoss’s global sales, and the company has said it expects that unit to account for about 14% to 16% of sales in 2026, according to Chief Executive Officer Kim Fausing. On a revenue base of roughly EUR 9.4 billion, that is a swing worth several hundred million euros, driven almost entirely by flow-control components inside cooling loops.
Parker Hannifin is the largest pure industrial name in this group. The company reported $5.49 billion in revenue in fiscal Q3 2026, up 10.6% year over year. Parker is increasingly positioning itself as a key supplier to AI-focused data centers through liquid cooling components, including couplings, fluid-control valves, and refrigerant-loop hardware. A record backlog of $12.5 billion and higher fiscal 2026 guidance reinforce the near-term catalyst of improved profitability.
The Supply Moat Nobody Is Talking About
Secondary-loop pipework running 30 to 50 degrees Celsius in long-term contact with glycol-water requires corrosion-resistant materials such as stainless steel or copper. Every weld, valve, and flange must hold for years. That is a moat, not a market opportunity, and it is priced into almost nothing outside of Belimo’s Swiss-listed shares.
Boyd Thermal’s 2026 revenue was forecast at $1.7 billion, with $1.5 billion from liquid cooling, making it essentially a pure-play AI thermal platform. Eaton paid $9.5 billion for it and closed the deal on March 12, 2026. That premium valuation reflects the scarcity of hyperscaler-qualified, scaled liquid cooling manufacturers. When a strategic buyer pays more than 5x revenue for a manifold-and-cold-plate business, it is telling you something about how few alternatives exist.
Options Framework
Vertiv (VRT), Eaton (ETN), and Parker Hannifin (PH) are the three U.S.-listed proxies with material liquid-cooling exposure. Vertiv stock has jumped roughly 50% in 2026 but has fallen about 35% from its 52-week high in mid-May 2026, changing the entry math versus peak optimism. For traders who believe the manifold crunch sustains margins into 2027, a defined-risk bull structure in VRT using a call spread captures the rebound without full downside exposure to a multiple contraction. If you believe Eaton’s Boyd integration stalls, a put spread on ETN with strikes bracketing the roughly $9.5 billion purchase price provides a defined-risk expression of that thesis. PH, trading at record backlog with industrial optionality, suits a neutral income approach: covered calls against existing long exposure reduce cost basis while the core cooling demand plays out.
The risk is technology rotation. Direct-to-chip liquid cooling dominates, but immersion and two-phase approaches are emerging, requiring suppliers to stay on the winning roadmap. A supplier certified for today’s cold-plate architecture is not automatically qualified for a 500 kW immersion rack in 2027. Position sizing matters as much as direction.