October 8, 2026
Bonus Content: Levi’s Beat the Earnings Number. The Market Didn’t Buy It.
Ian Cooper here,
For the longest time…
I thought successful options trading required:
- ❌ Staring at charts all day
- ❌ Learning 100 different strategies
- ❌ Taking huge risks
- ❌ “Predicting” the market perfectly
And honestly?
That belief nearly cost me everything.
I was overwhelmed, confused, and constantly second-guessing every trade.
Then I discovered something that completely changed the game…
A surprisingly SIMPLE options setup that helped me stop overthinking and start trading with clarity.
No complicated indicators.
No endless market analysis.
No “Wall Street genius” required.
Just a straightforward approach almost anyone can learn.
That’s why I just released this FREE report:
“The $50 to $500 Options Strategy;
Inside, you’ll discover:
- ✔ The #1 mistake rookie options traders make
- ✔ A simple & repeatable trade setup
- ✔ Step-by-step trade blueprints you can copy tonight
- ✔ How to ignore the noise and focus on bigger opportunities
👉 Get your free copy here now.
In your corner,
Ian Cooper
Levi’s Beat the Earnings Number. The Market Didn’t Buy It.
Markets don’t need a big EPS number. They need a clean one.
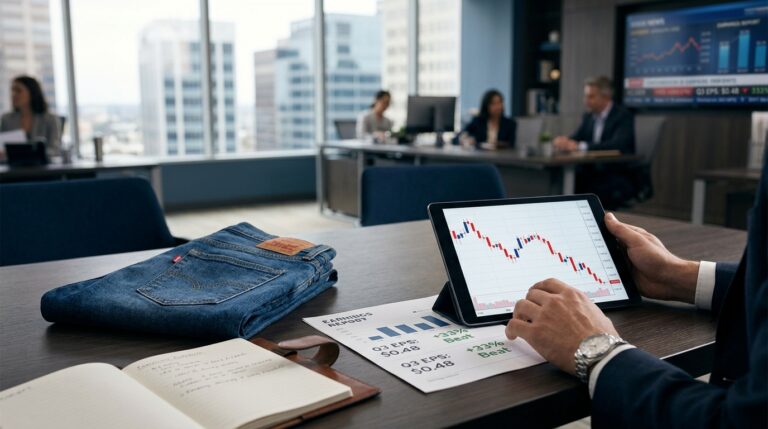
Levi Strauss reported fiscal Q3 2026 after the close on October 7. Adjusted EPS came in at $0.48, a 33% beat versus the $0.36 consensus. Revenue rose 4% to $1.6 billion on a reported basis and 5% organically. Gross margin expanded 450 basis points to 66.2%. On the surface, that is a strong quarter. LEVI initially traded higher after hours. By the time the dust settled, the stock was down roughly 1.5% in after-hours trading, and it opened October 8 down roughly 5% from Tuesday’s close of $20.53.
The market had questions. Once it read the footnotes, it had answers.
What the Numbers Actually Said
Roughly $0.11 of the EPS outperformance came from about $79 million in tariff refunds recorded under the International Emergency Economic Powers Act, net of the amount the company redeployed into promotions and marketing. Strip that out and the headline beat shrinks from $0.12 to roughly $0.01. Gross margin widened sharply to 66.2%, and tariff refunds played a large role.
Levi said it saw a 4% increase in net revenues in the Americas during the quarter, though revenue in the U.S. decreased by 1%. DTC growth in the U.S. on a reported basis reflected a 1% decrease. The US DTC channel faced challenges due to a back-to-school campaign that under-delivered, with traffic and demand lower than anticipated, though trends improved into September. Internationally the story was better: Asia revenue rose 10% organically. Global wholesale grew 6%.
The company trimmed its full-year reported revenue growth outlook to approximately 7.0%, the low end of its prior range, even as it raised its adjusted EPS guidance to $1.54 to $1.56. The narrowed revenue outlook implied about $6.72 billion, versus the $6.76 billion analyst estimate. Raising EPS while tightening the sales outlook is a combination the market has learned to penalize in apparel. It signals margin management rather than demand.
Why the Reaction Flipped
This is not about the magnitude of the beat. It is about the source. When $0.11 of a $0.12 EPS beat traces to a one-time tariff refund that management then partially redeployed into promotional spending, the market correctly asks: what does the core business earn? The answer, based on operating trends, was underwhelming. The move suggests investors were not fully convinced by the EPS beat, likely because revenue missed expectations and the company described weaker U.S. DTC traffic and higher spending on marketing and distribution.
LEVI’s initial reaction was higher, then about 1.5% lower after hours. Four straight EPS beats, and the market keeps pricing the guide, not the beat. The pattern repeated exactly here.
Options Market Behavior
Pre-earnings options volume in Levi Strauss was elevated, with call volume ahead of put volume. Heading into the report, 30-day implied volatility was in the mid-50% range, and the options-implied move was about 7% based on near-dated pricing. The actual move through the next session’s open was in the bearish direction and in line with that neighborhood, meaning directional call buyers faced the typical post-event volatility compression.
For traders evaluating the next apparel report, the LEVI framework is instructive. Call-heavy positioning, combined with elevated IV heading into a report where guidance quality matters as much as the headline number, is a structure that can transfer returns from directional buyers to premium sellers.
Sector Read-Through
KSS, GPS, and ANF all report within the next two months. Each carries its own DTC mix, tariff exposure, and wholesale dependency. The LEVI result does not doom them. It does set a higher bar for what constitutes a genuine beat. Revenue in line or below, EPS aided by one-time items, and guidance at or below the low end of prior range: that combination no longer gets rewarded.
Structured Trade Framework
For traders with a view on LEVI specifically, the stock now sits near the lower end of its 52-week range with IV likely to compress post-event.
- Bull case: If you believe September DTC improvement continues into Q4 and the tariff refund reinvestment into marketing begins to show in comparable sales, a defined-risk call spread targeting the mid-$21 area captures recovery without naked exposure to further guide cuts.
- Bear case: If U.S. consumer softness persists and the full-year revenue guide of roughly $6.72 billion proves optimistic, a put spread below current levels with defined risk is the structure. Do not buy naked puts into low IV following the crush.
- Neutral case: IV has now deflated. A short iron condor in the weeks preceding the next sector report (GPS or ANF) can capture premium without a directional bet, given the elevated sector uncertainty that LEVI’s mixed result has introduced.
Risk Checklist
- Full-year EPS guidance of $1.54 to $1.56 includes a benefit from IEEPA tariff refunds, with about $60 million of that benefit expected to be redeployed into the business for the full year, including about $35 million in Q4.
- US DTC distribution network transformation is not expected to yield cost savings until 2027, per management commentary.
- LEVI stock had already declined more than 15% over the prior three months heading into the report. Mean reversion exists, but requires a clean demand signal.
- Sector peers pricing: use LEVI’s reaction as a calibration tool, not a template. Each name carries different channel mix and margin structure.