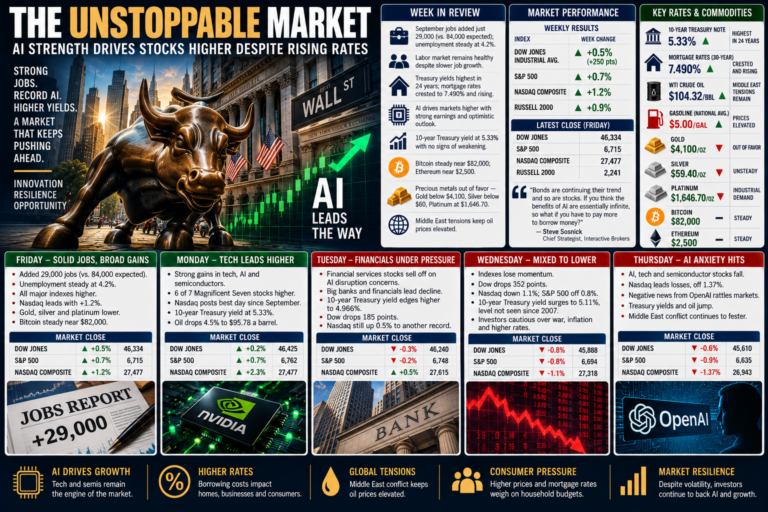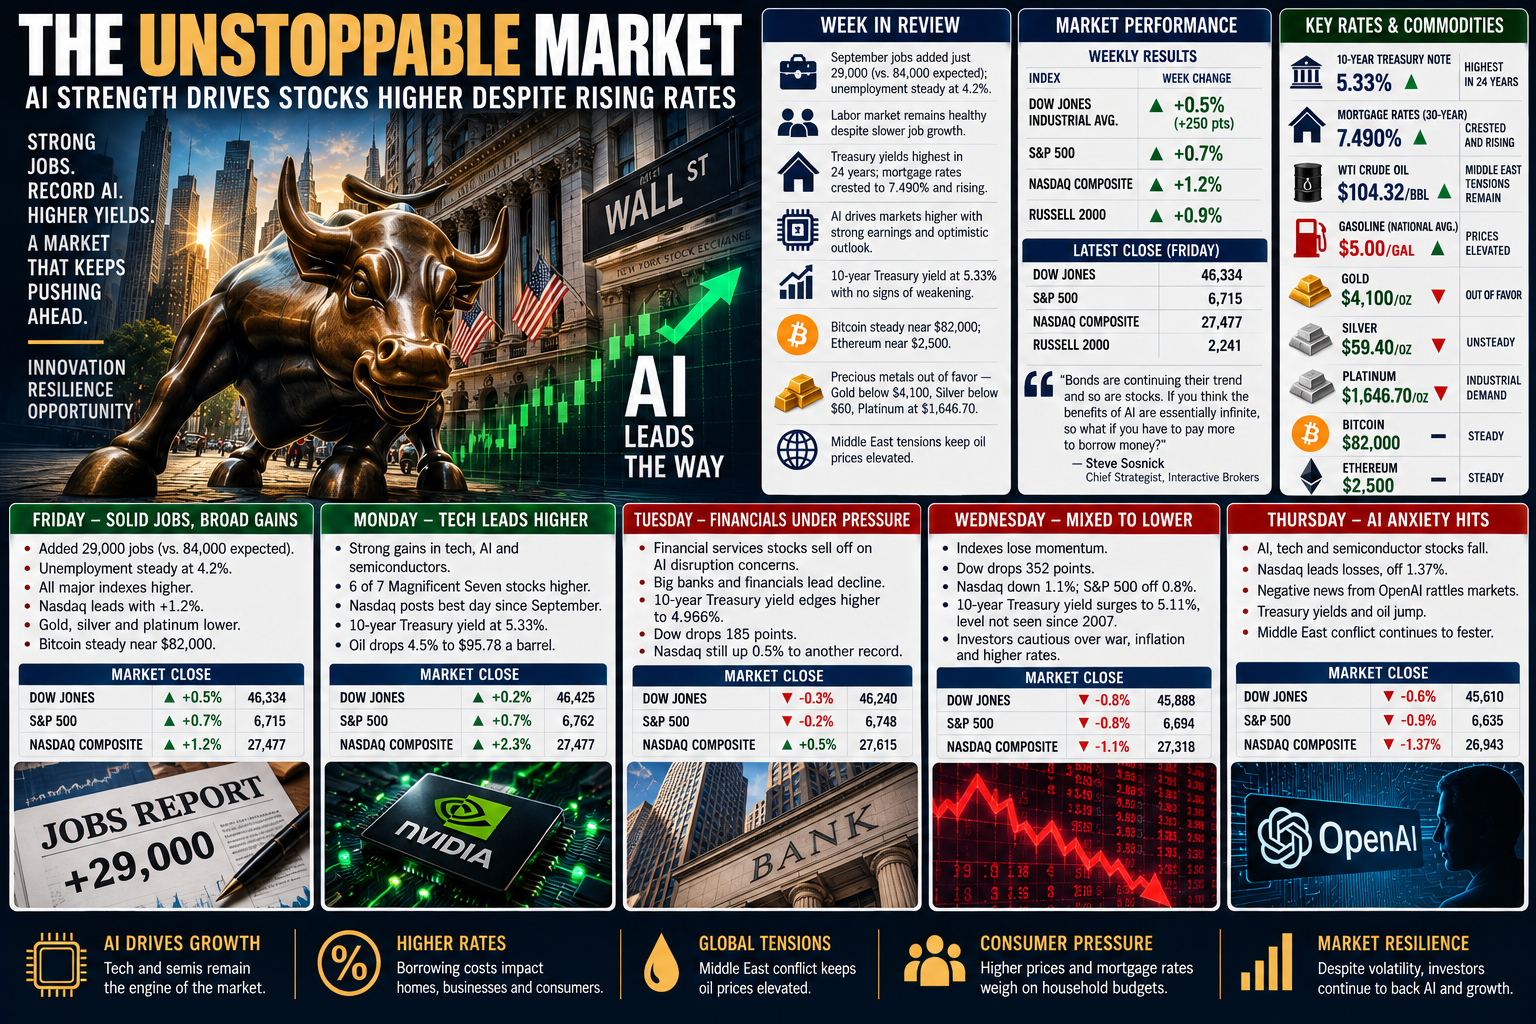
The Labor Department released jobs numbers last Friday for September, with just 29,000 jobs added. A far cry from what analysts had predicted of 84,000. Yet the unemployment rate of 4.2% stayed close to August’s rate of 4.1%, still at a historically low level, indicating a healthy labor market overall. “That all speaks to continued strength in the labor market,” said Kathy Bosrjancic, chief economist at Nationwide. “A very important reading on consumer prices” for September due out October 14th will give the Fed a barometer of the need for possible future rate increases. Treasury yields are the highest in 24 years, while surging mortgage rates have crested to 7.490% and creeping higher. Stymied home buyers along with investment home buyers are pulling back–fearful of reaching desired returns. The solid jobs report gave a significant boost as all three indexes and the Russell 2000, an index composed of high quality value-oriented smaller companies climbed 0.9% Friday. The bread and butter Dow Jones Industrial Average added 250 points or 0.5%, while the S&P 500 was up 0.7%. The tech laden Nasdaq Composite led all indexes, up 1.2% at Friday’s finish. Bitcoin was steady at near $82,000 while ‘little sister’ Ethereum was steady at $2,500 a coin. Precious metals were ‘out-of -favor’ as investors looked to the high-flying AI market, with gold slipping below $4,100 a troy ounce. Silver was unsteady, slipping below $60.00 a troy ounce Wednesday at $59.40 a troy ounce. The ‘unpopular’ precious metal, platinum, used heavily for industrial needs, is trading lower at $1,646.70. The forgotten metal plays a ‘second–fiddle’ to gold and silver.
It was a ‘grand–opening’ of the markets Monday for the technology sector as it drove the “Bull-Hesitent” market, reassuring investors of the powerful influence of artificial intelligence sector on the economy. The bond markets continued to march higher with yields reaching monumental highs. The 10-year Treasury note yield, a fine barometer of bond-market yields, is showing no signs of weakening, with the present rate at 5.33%. Monday’s indexes followed suit, with The Dow Jones Industrial Average and S&P 500 adding 0.2% and 0.7% respectively. The heavy–tech Nasdaq Composite had the best day since September, finishing the day at 27477.31. “Bonds are continuing their trend and so are stocks. If you think the benefits of AI are essentially infinite, so what if you have to pay more to borrow money?,” said Steve Sosnick, chief strategist at Interactive Brokers. According to The Wall Street Journal, “Bond yields and equity prices often move in opposite to one another–not so in recent weeks.” Soaring earnings, a stronger AI outlook regarding the build–out have boosted across–the–board stock prices. The Magnificent 7 group “hit a new market–cap high Monday of $24.8 Trillion valuation. According to Michael O’Rourke, chief market strategist at JonesTrading; “Investors are wagering that megacap tech can withstand the risks of higher rates.”
Tuesday’s blazing market was more of Monday’s, heavily influenced by the unbelievable AI sector. AI has impacted nearly every market sector, ‘thrusting’ stocks upward for many of the wrong reasons.’ Both the Nasdaq and S&P 500 streaked to new record highs. Even higher interest rates heavily affecting AI build–outs don’t seem to slow the AI momentum as the buying tempo just increases. “People look around and say, ‘Which areas of the market can weather this?,‘“ said Keith Lerner, chief investment advisor for Truist Advisory Services. “Tech is almost seen as defensive in some ways.”
The S&P 500 and the Nasdaq Composite skidded back from record high on Wednesday as markets were concerned that “stock’s valuation multiples are dropping, as investors are being more cautious buying.” The 10–year Treasury note hit yet another high, then backed off as markets were lethargic. Mark Hackett, chief market strategist at Nationwide Investment Management said; “Higher interest rates make stocks less valuable.”
Stocks continued to fall on Thursday as AI anxiety droveAI, techs, and semiconductors downward. The Nasdaq Composite finished off 1.37% and led all indexes to negative finishes. Bad news Thursday, from OPEN Al spread quickly, dampening techs, semiconductor, and software stocks. Treasury yields and oil jumped as the Middle East conflict festered.
RUMBLINGS ON THE STREET
Jamie Cox, managing partner at Harris Financial Group, WSJ – “We were due for a relief rally,” said Mr. Cox. “There needed to be a catalyst, and this jobs report was it.”
Everett Dirkson, Former Senator representing Illinois, referring to the use of the word ‘trillion,’ Barron’s – “A trillion here, a trillion there and pretty soon you’re talking ‘real money.”
Jeff Killburg, KKM Financial CEO, Barron’s – “I’m in the camp that we’re going to find a solution in Iran. I think we get out this month, and then we see crude oil crack, and we see rates crack with the 10–year yield falling back below 5%.”
Carol Schleif, Chief market strategist, BMO Wealth Management, WSJ – “While investors fret over inflation, bond yields and geopolitics, stocks continue to climb the wall of worry–with double–digit gains this year.”