October 9, 2026
EPS missed, guidance collapsed by nearly $1.65 at the midpoint. CFO Erik Snell said it plainly: all of it is fuel.
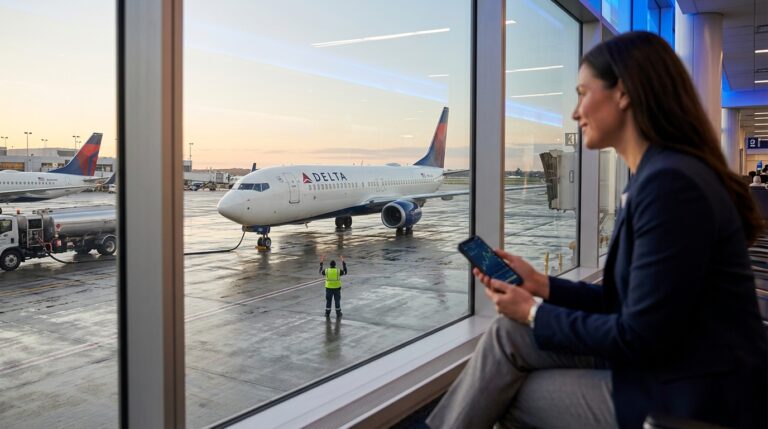
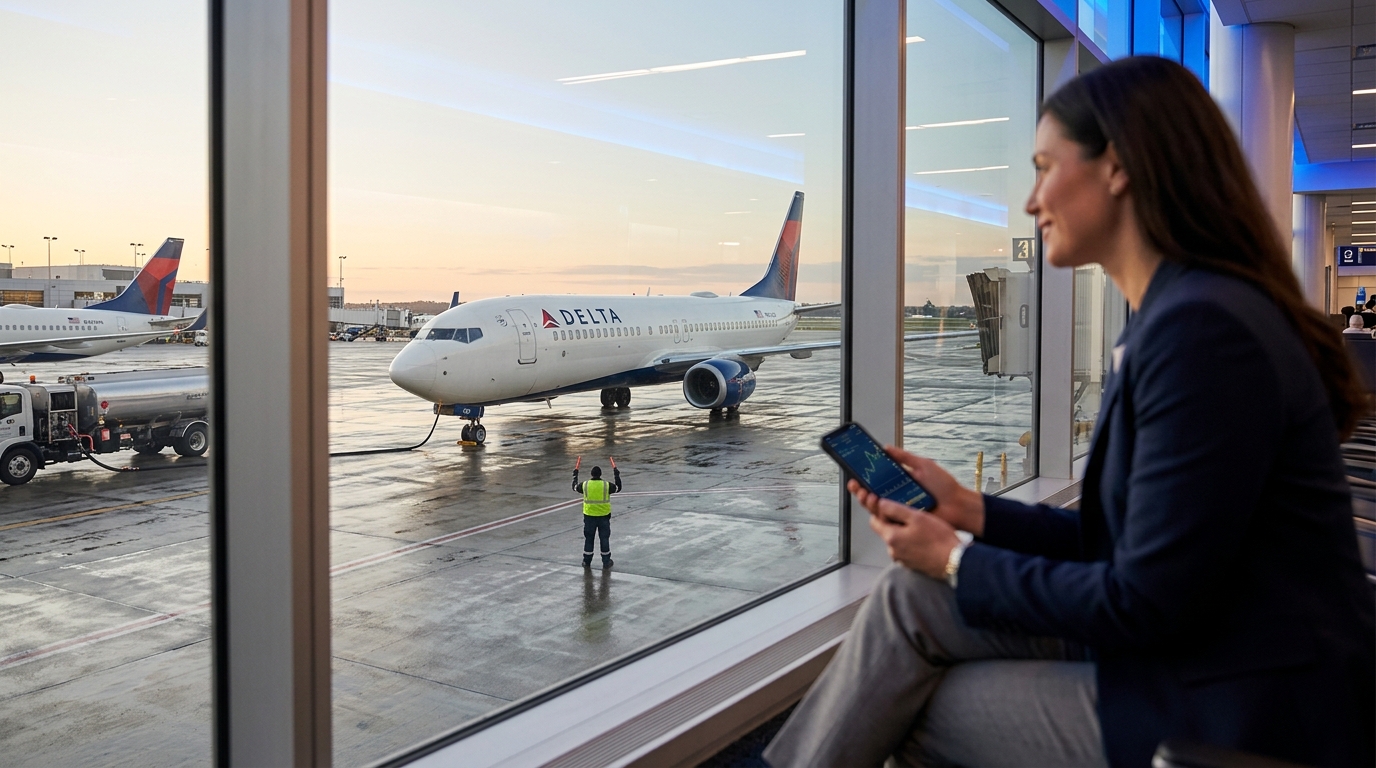
Delta Air Lines reported Q3 2026 adjusted EPS of $1.72 on Friday morning, missing the consensus estimate. Revenue came in at $20.2 billion, up 21% year over year and above expectations. The stock fell roughly 4% in early trading to around $79. That combination of a top-line beat and bottom-line miss has a single explanation: a fuel bill that overwhelmed everything working in Delta’s favor.
Your Power Bill Is Funding the AI Boom
The bulk order that keeps the lights on across 13 states just jumped from $2.2 billion to $14.7 billion – nearly 7x in one year – because data centers are draining the grid. There’s one energy source that runs 24/7 with no fuel, and Washington just preserved its tax credits through 2033 while terminating everyone else’s. Google signed for 15 years. Bill Gates invested $100 million. One company has spent sixty years building it.
What the Numbers Actually Say
Adjusted EPS of $1.72 landed below the $1.75 to $1.77 consensus range, marking Delta’s first earnings miss in two years. GAAP EPS came in at $1.15, down 47% from the same quarter a year ago. Revenue growth of 21% is real and meaningful. The problem is that fuel cost growth ran at 62%.
Adjusted fuel expense hit $4.14 billion in the quarter, with the average adjusted fuel price rising 60% to $3.61 per gallon. CFO Erik Snell told reporters the quarter absorbed more than $500 million in additional fuel costs above Delta’s early July forecast. The adjusted operating margin narrowed to 9.4% from 11.1% a year earlier. Delta’s own July guidance assumed a very different fuel environment.
The Guidance Cut Is the Story
Delta slashed its full-year adjusted EPS outlook to $5.10 to $5.60, down from the $6.50 to $7.50 range issued in July. The midpoint falls from $7.00 to $5.35, a 23.6% reduction. Free cash flow guidance dropped from $3 to $4 billion to approximately $2.5 billion. Gross leverage is now projected at 2.2x, up from roughly 2x. Delta now expects a $6 billion increase in full-year fuel costs, which Snell characterized in a single line: “All of it’s fuel.”
For Q4, Delta guided adjusted EPS of $1.15 to $1.65 and total revenue growth of approximately 20%. The Q4 fuel cost assumption is $4.25 per gallon, up from $3.61 in Q3, with a 40-cent refinery benefit baked in. CEO Ed Bastian maintained that travel demand has not cracked, and premium cabin and loyalty revenue continued to grow through the quarter. The demand side is not the problem.
Stop Picking AI Winners. Start Collecting Every Thursday.
Everyone wants to know which AI stocks are going to win. But you can invest in one fund that owns them all and collects up to $1,051 a month, delivered every Thursday.
Sector Read-Through
The JETS ETF dropped 0.5% on the news while the S&P 500 climbed 0.4%, a clean divergence that shows the fuel shock landing across the group. United Airlines fell 0.9% and American Airlines slipped 1%, with both carrying lighter damage than Delta because they have not yet reported. That dynamic typically reverses at their own print dates. AAL reports October 22. UAL follows closely. Neither stock has priced the full cost of $4.25 per gallon fuel.
Options Market Structure
The stock moved roughly 4% on the print, consistent with a modestly sized implied move for an airline in a known high-fuel environment. Post-earnings IV crush is now the dominant dynamic, though residual uncertainty around sector fuel exposure keeps premium in UAL and AAL elevated ahead of their reports. For traders positioning in the sector, the edge has shifted: selling premium into peer earnings events with defined-risk structures captures that elevated IV without naked directional exposure.
7 AI Stocks to Invest in Today
AI is fueling the Fourth Industrial Revolution – and these 7 stocks are front and center. One of them makes $40K accelerator chips with a full-stack platform that all but guarantees wide adoption. Another powers the . From core infrastructure to automation leaders, these companies and other leaders are all in 7 AI Stocks to Invest in Today.
Trade Framework
Bull case: If you believe Brent crude retreats meaningfully from current levels and Delta’s Q4 fuel assumption of $4.25 per gallon proves conservative, the $5.10 to $5.60 full-year range has upside. A defined-risk call spread in the $82 to $88 range over 30 to 45 days captures a fuel-relief recovery without uncapped exposure.
Bear case: If fuel holds or climbs above $4.25 per gallon through November, Q4 guidance breaks at the low end. The $1.15 floor on Q4 EPS is thin. A defined-risk put spread below $74 hedges continued pressure without full short exposure.
Neutral case: With DAL now range-bound between $78 and $84 and IV elevated in peer names, a short iron condor in UAL or AAL with 21 to 30 days to expiration collects premium from a sector-wide event without requiring a directional call on crude.
Action Checklist
- Q3 adjusted EPS: $1.72 actual vs. $1.75 to $1.77 consensus. First miss in two years.
- Full-year EPS guide cut to $5.10 to $5.60 from $6.50 to $7.50. Midpoint down 23.6%.
- Q3 fuel expense: $4.14 billion, up 62% year over year. Average price: $3.61 per gallon.
- Q4 fuel assumption: $4.25 per gallon. Every 10 cents above that is direct margin risk.
- Watch AAL on October 22 and UAL shortly after. Neither has repriced the $4.25 fuel environment yet.
- Premium and loyalty revenue held through the quarter. Demand is not the variable to short.
- Free cash flow guidance reduced to $2.5 billion. Debt repayment target of $2 billion-plus remains intact.