October 10, 2026
Bonus Content: Bearish Bets on Apollo, KKR, and Ares Are Rising. Here Is How Options Traders Are Playing It.
Attention Traders…
If you’re willing to be at your computer between 9 am and 10:45 am on most weekdays…
I can show you one simple trade that can potentially bankroll your retirement.
Hi… I’m Dave Aquino and I help everyday Americans go after their retirement goals sooner… by teaching them how to master the retirement trade.
The Retirement Trade is designed to be used every morning between 9am and 10:45am eastern time.
Why this window?
Well… I can’t share that information here on this page…
But don’t worry because you’ll discover the exact reason why inside the free report you see pictured below…
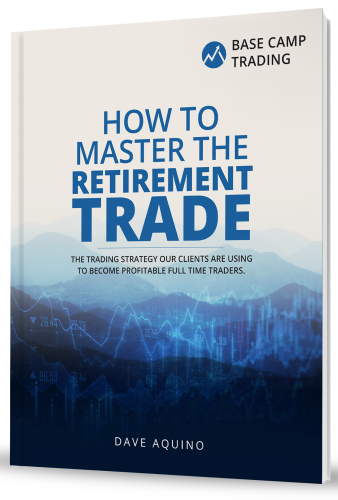
And it’s yours – for FREE!
But please don’t delay, because it might not be free for long.
Bearish Bets on Apollo, KKR, and Ares Are Rising. Here Is How Options Traders Are Playing It.
This is not about whether private credit is broken. It is about how little anyone really knows what it is worth, and what listed equities are now pricing in because of that uncertainty.
Just 4% of fund groups perform a full daily valuation update on private credit, reassessing unobservable inputs, cash flow assumptions, and methodologies. The largest group of fund managers, 39%, conduct those comprehensive, judgment-based updates quarterly. That gap is the core tension behind everything moving in this space right now. Quarterly marks in a bond selloff is not valuation. It is a lag.
Apollo announced it has begun providing daily pricing information to additional investors across its $850 billion credit business, extending the initiative across direct lending, asset-backed finance, multi-credit, and opportunistic credit vehicles after launching daily pricing for its investment-grade Fixed Income Replacement suite on July 1, 2026. Asset-level pricing for applicable funds is expected to be made available to investors beginning on October 30, 2026. Apollo describes the daily pricing as an estimated fair value using its own internal methodology benchmarked against public market data. It is explicitly not a market-clearing price, nor is it intended to serve as a definitive valuation or as the basis for subscriptions, redemptions, or any other transaction.
The Shorts Are Back
Short-sellers are taking aim at private credit as a bond rout deepens, with a flurry of September activity driving bearish bets toward levels unseen since an exodus from the asset class in the first quarter. Traders can take positions against listed vehicles and other proxies, including BDCs, collateralized loan obligations, and alternative asset managers with significant exposure to the sector.
A major change to U.S. bank accounts could arrive in months.
It may allow closer tracking of your transactions.
The numbers are specific. Net short selling across a 14-ETF sample tracked using FINRA data reached $88.6 million during the first half of September, roughly double August’s $44 million and close to the $102 million recorded in March, when investors were exiting private credit positions more aggressively. The number of shares sold short climbed sharply, reaching 6.4 million by mid-September from 2.9 million at the end of August. The growing appetite for downside exposure is being supported by major banks, with Goldman Sachs, JPMorgan, and Bank of America among those offering clients ways to take bullish or bearish positions on private credit through baskets of publicly traded companies.
Short interest as a proportion of assets under management across the ETF sample stood at 2.1% in August but had recovered to 2.7% by mid-September, closing in on the record 3.4% hit in March. The backdrop amplifies the pressure: the global bond selloff deepened last week, with 10-year Treasury yields climbing as high as 5.36% intraday, their highest level since 2002.
The leverage embedded in the Treasury market amplifies that pressure. Hedge fund gross Treasury exposures doubled to $4 trillion between 2023 and late 2025, creating the basis-trade fragility that turns a yield spike into a forced-selling event.
What the Equities Tell You
APO’s 52-week range extends from $99.56 to $153.29. At $118.65 on October 9, the stock is nearly 23% below its 52-week high. Blue Owl Capital dropped to $9.32, down about 27% from its August high, while Blackstone traded around $118.50. These are not minor pullbacks. They represent a resetting of fee-earning power tied directly to AUM stability inside the private credit sleeve.
The KKR situation adds texture. K-FITS, the firm’s non-traded BDC for retail investors, received repurchase requests for approximately 5.06% of shares for the offer that expired September 29, and the fund said it would slightly exceed its 5% limit to satisfy all requests. At a moment when virtually every major non-traded BDC, including Blackstone, Blue Owl, Ares, and HPS, has enforced strict 5% caps and let queues roll forward, KKR opted to go above its limit and clear all remaining requests. Differentiation at the fund level does not insulate the listed equity.
Options Market Analysis
The options flow in APO confirms what the short data suggests. On September 24, options trading in APO rose to 80,673 contracts, with put volume hitting 79,823 contracts against 850 calls, producing a roughly 94:1 put/call ratio. The four largest October 16, 2026 puts at strikes of $105, $110, $115, and $125 accounted for 56,004 contracts combined. That is not hedging. That is directional conviction.
With earnings not until November 3, the near-term options market is priced around continued macro pressure rather than a company-specific catalyst. The put/call open interest ratio sits below 0.70, which reflects legacy long positioning still in place, but the flow is pointed one way.
Structured Trade Framework
Bull case: For traders expecting stabilization in the bond market and a positive read on Apollo’s October 30 asset-level pricing rollout, a defined-risk structure such as a December bull call spread in APO at the $120/$135 strikes captures upside if the transparency initiative narrows the valuation discount. The analyst consensus price target of $151.45 provides the fundamental anchor.
Bear case: If you believe the bond selloff continues and redemption queues at BDCs re-accelerate, a November put spread on APO in the $110/$100 range offers defined downside exposure. The September flow in $105 and $115 strike puts shows institutional players are already positioned there.
Neutral case: An October/November calendar spread on APO around the $118 strike collects elevated short-dated volatility while maintaining optionality into the November 3 earnings event.
He went 11-for-11 during the last Fed shock. Another one is about to hit.
In 2022, when the Federal Reserve made its most dramatic pivot in history and the S&P lost nearly 20%, Larry Benedict didn’t lose a single trade.
He knew where the money was going and positioned his readers to profit.
Trump is now installing his own Fed Chair, something Wall Street is already calling a generational shift.
Larry says his readers will be ready for it.
Click here to find out the one ticker he’s positioning in, completely free.
Risk Analysis and Forward Outlook
The US Securities and Exchange Commission issued a statement reminding firms to apply rigor when valuing private assets, calling out private credit alongside other private assets because of its rapid growth. Regulatory pressure combined with a higher-for-longer rate environment keeps the asymmetry skewed bearish for the group until redemption queues clear and AUM flows stabilize.
Apollo’s October 30 date is the next observable signal. If asset-level pricing is perceived as credible and does not surface material markdowns, APO could recover toward the $130 range. If the transparency initiative reveals previously obscured losses, it accelerates the bear case across the entire sector, pulling Ares, Blue Owl, and Blackstone lower in concert.
Action Checklist
- Monitor APO options flow around October 30 for any shift in the put/call ratio as asset-level pricing goes live
- Track BDC repurchase and redemption filings for Q3 close across Blue Owl, Ares, and Blackstone, due in the next two to three weeks
- Watch 10-year Treasury yield relative to the 5.36% intraday high seen this week for directional signal on the broader private credit proxy basket
- For defined-risk positioning: confirm IV levels before entering any spread structure
- Note earnings dates: BX reports October 22, ARES reports October 29, APO reports November 3, creating a sequential catalyst window