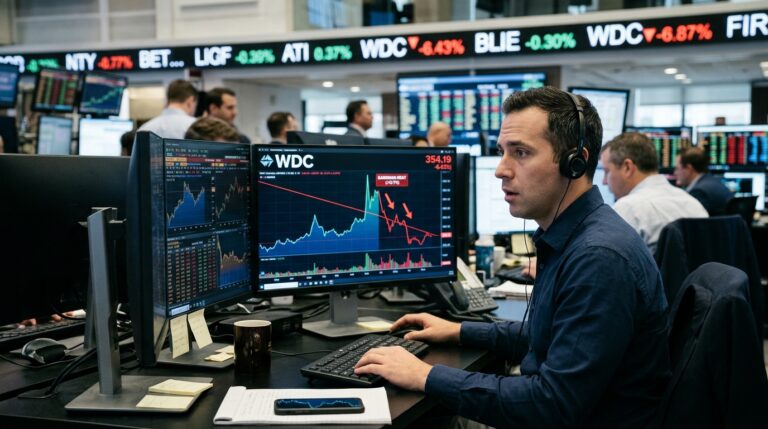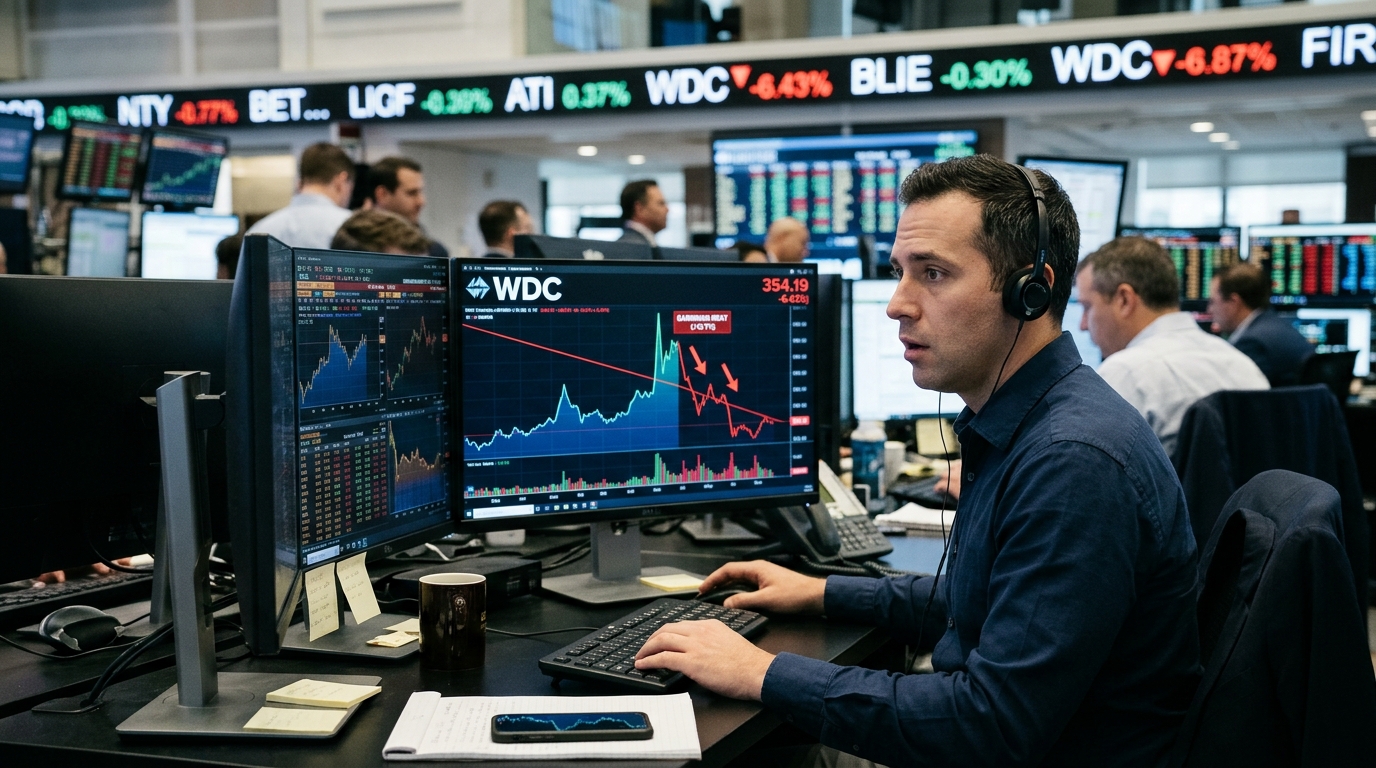
Markets don’t need a bad quarter to punish a stock. They only need a quarter that fails to exceed what was quietly priced in. Western Digital handed Wall Street $4.64 in non-GAAP EPS against a $4.08 consensus, a 13.7% beat on the bottom line and roughly $240 million above revenue expectations on the top. Then the shares dropped 6.43% in the regular session to $354.19, bounced briefly after the earnings release, and slid further in after-hours trading. The options market had a clue before the earnings call ended.
This is not about whether Western Digital is a good business. It plainly is. Revenue reached $4.38 billion, up 55% year over year. Non-GAAP gross margin came in at 58.1% and free cash flow hit $1.38 billion. The board raised the quarterly dividend 17% to $0.175 per share, with the first higher payment set for December 17, 2026. The fundamentals are not the story. The positioning is.
What the Numbers Actually Said
For the December quarter, Western Digital guided adjusted EPS of $5.60 to $6.00 and revenue of $5.0 billion to $5.2 billion, both above prior market expectations of about $4.84 per share and $4.57 billion in revenue. At the midpoint, that implies roughly 69% year-over-year revenue growth, with gross margin guided to 60%-61%. Management attributed the strength to a favorable pricing environment, with blended average price per terabyte up 28%, and a fast-ramping ePMR platform. CEO Irving Tan said the company now has deeper multi-year visibility with key customers.
The result marked a sixth straight quarter of adjusted EPS exceeding expectations. Consecutive beats of that length tend to raise the implied bar. By the time WDC reported, the stock had already reflected considerable optimism, and any shortfall in how the guide was received became a selling event.
The Options Market Read
Ahead of the report, the options market priced a mid-to-high single-digit implied earnings move for WDC. The stock’s post-earnings swing pushed beyond that envelope as the move unfolded from the regular session into after-hours trading. Implied volatility had been elevated into the event, and the flow skewed bullish. When the guide failed to clear the most aggressive expectations discussed into the call, the unwind was swift.
Broader selling pressure hit the sector as markets remained concerned about whether large-scale capital expenditures can generate meaningful near-term returns. That macro weight compounded the technical unwind in WDC specifically.
Sector Read-Through: CXMT’s Shadow
The selloff was not contained to WDC. SanDisk, Western Digital, and Micron all fell as memory and storage stocks extended a multi-session decline, with worries about competition from Chinese memory maker CXMT driving the pressure. SanDisk dropped 8%, still leaving the shares up 429% year to date. Added supply from China could weigh on memory pricing, a risk that cuts deepest for names with the biggest runs. Mizuho pushed back on the fear, reiterating an Outperform on SanDisk and arguing that flash pricing is likely to stay stable because capacity outside China is expected to remain largely unchanged. That has not stopped the group from selling off in tandem.
Micron faces the same CXMT supply narrative that is weighing on WDC and SanDisk. Michael Burry’s short position in Micron rests on exactly the Chinese memory oversupply thesis now hitting the entire sector.
Structured Trade Framework for the December Guide
The December quarter guide, $5.60 to $6.00 EPS and $5.0 to $5.2 billion revenue, is now the only number that matters for WDC price action. After IV crush following the earnings event, defined-risk structures around that guide become more cost-effective than they were 48 hours ago.
- Bull case: For traders expecting the December delivery to validate the guide, a January call spread centered above $360 defines risk while capturing a rebound toward the pre-earnings $378 close. Elevated sector fear has compressed the stock, not the business.
- Bear case: If CXMT supply fears accelerate or neocloud capex slows, a put spread below $320 into November expiry captures continued sector pressure without naked short exposure. The implied move was large across the event window, and a second leg lower is not implausible.
- Neutral case: A post-crush short strangle in the $320/$380 range through November expiry collects premium against a period where the next fundamental catalyst, December quarter data points, is weeks away. Defined-risk via an iron condor limits tail exposure to a sector gap event.
Risk Factors
The stock has fallen over 50% from its June high, meaning sentiment damage preceded the earnings report. Any recovery requires not just strong delivery in December but a simultaneous easing of CXMT competition fears and a stabilization in AI capex sentiment across hyperscalers. Management noted that a slowdown in any one demand segment, including neoclouds, would be offset by the other three growth drivers, but markets are unlikely to take that argument on faith until December numbers confirm it.
Action Checklist
- WDC closed at $354.19 in the regular session post-earnings. Monitor $320 as near-term support and $360 as first resistance.
- IV crush post-event: reassess long premium structures; favor defined-risk spreads over outright options purchases.
- Watch SNDK and MU for sector confirmation. A stabilization in both signals the CXMT fear trade is exhausted, not accelerating.
- December quarter data points, hyperscaler capex guidance and NAND spot pricing, are the real catalyst. The December guide is not worth trading until those inputs are cleaner.
- The dividend raise to $0.175 per share provides a modest yield floor, but at current prices that is a sentiment signal, not a valuation anchor.