November 3, 2026
Bonus Content: ASML’s 2030 Revenue Floor Just Moved. Old Guidance Is Obsolete.
If you still haven’t downloaded my “Simple Options Trading For Beginners” book…
…please take a few seconds and download it right now before your new temporary download link expires.
I eventually plan to charge for this book, so do yourself a favor and download it now…
That way, no matter how much it is in the future, you’ll have a copy on your computer already.
Make sense?
FREE: Simple Options Trading For Beginners << Download Now
Good Trading,
Bill Poulos
P.S. Go here to save a copy of my “Simple Options Trading For Beginners” book to your computer before I start charging for it.
ASML’s 2030 Revenue Floor Just Moved. Old Guidance Is Obsolete.
Markets don’t need a company to beat a quarter. They need it to prove the ceiling is higher than anyone thought. ASML just did both, and the more consequential data point has nothing to do with October.
When ASML set its long-term 2030 revenue framework at the November 14, 2024 investor day, the range was €44–60 billion. That low end now looks almost quaint. The top end of ASML’s 2026 full-year guidance already sits at €45 billion, meaning the company is touching the floor of its six-year target in year two of that plan. The question worth framing is not whether ASML will hit 2030 guidance. It is whether the guidance still reflects reality at all.
What the Q3 Numbers Say
ASML reported third-quarter net sales of €11.7 billion and net income of €5.0 billion, and guided full-year 2026 net sales at €44–45 billion with gross margin around 56%. Management also flagged that customer demand is expected to exceed its planned supply through at least 2028, a structural constraint rather than a cyclical shrug.
On an EPS basis, ASML reported €12.93 a share (diluted). Q4 sales are guided at €14.2–15.2 billion with gross margin around 57%, supporting full-year sales of €44–45 billion with a gross margin of approximately 56%.
The Demand Signal No One Is Pricing Correctly
CEO Christophe Fouquet said customers continue to increase their short- and medium-term equipment demand forecasts, driven primarily by their views on the size and duration of AI-related investments, and that some customers are expressing interest in placing orders for 2029 and even 2030. These are not letters of intent. ASML’s order book reflects chip manufacturers placing real, multi-year commitments for machines that take months to build.
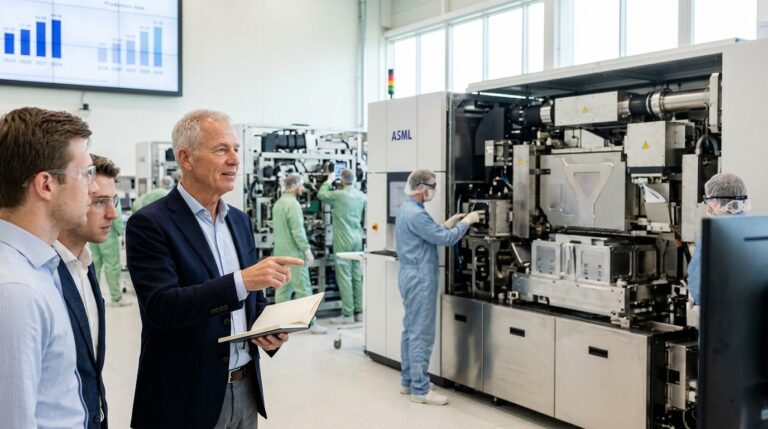
ASML has been discussing an expansion path that adds about 30% to its 2026 low-NA EUV output of roughly 65 systems for 2027, with a further 30% increase investigated for 2028. A similar 30% increase has been discussed for DUV immersion capacity in 2027, with an additional expansion investigated for 2028. Morningstar estimates ASML could deliver close to €70 billion in revenue already in 2028, even without fully utilizing that capacity, making the previous 2030 ceiling of €60 billion look irrelevant.
The same demand signal is visible downstream from ASML’s fabs. Dell’s $95 billion AI server backlog shows chipmakers’ customers are also placing multi-year commitments faster than the supply chain can clear them.
Options Structure and Defined-Risk Framework
Options priced a 5.5% move into the Q3 report, implying a trading range of approximately $1,615 to $1,804. Shares fell 3.9% in the event window despite the EPS beat, a pattern consistent with sell-the-news behavior after multiple guidance raises and a stock trading at a forward P/E of roughly 29x.
For traders who believe the 2030 demand runway is real, a bull case would involve a defined-risk call spread targeting the $1,750–$1,900 range ahead of the June 10, 2027 Capital Markets Day, where management has said it will update its longer-term views. Waiting for the Capital Markets Day on June 10, 2027 to reset the long-term revenue framework is defensible as an entry discipline, not a reason to avoid the thesis. A bear case would focus on supply-chain capacity, China exposure, and upgrade durability as limits on how much demand converts into sustained margin. A neutral structure would be an iron condor anchored around current levels, selling the post-earnings volatility crush.
The options structure here mirrors a broader pattern across AI infrastructure names. Alphabet fell more than 7% after a record quarter when the market shifted from rewarding AI spending to demanding proof of returns on that capital.
The Risk That Matters
Looking beyond 2026, management has emphasized improving customer demand visibility via longer-term volume commitments while still maintaining its official 2030 guidance of €44–60 billion in revenue, which many analysts treat as conservative. Export controls on China remain the variable no model prices cleanly. ASML has said it expects China to account for around 20% of total net sales.
The real trade is not the quarter. It is the gap between a guidance floor already breached in 2026 and a formal 2030 target that won’t be updated for another seven months. That is where the asymmetry lives.
Action Checklist
- Monitor Q4 installed-base revenue: ASML is expanding upgrades that allow customers to process more wafers with existing equipment, and upgrade demand contributed to stronger revenue in Q3. Sustained upgrade strength would indicate demand is structural, not cyclical.
- Watch for China export control developments: any tightening beyond the current ~20% China sales expectation is the fastest way to impair near-term guidance.
- Treat the June 10, 2027 Capital Markets Day as the next hard catalyst for a formal 2030 guidance reset.
- If entering long exposure, prefer defined-risk structures: the stock has fallen on each of its last two beats. IV tends to compress sharply post-earnings, favoring spread buyers over outright long positions.