November 4, 2026
Bonus Content: Super Micro Beat by 47%. The Stock Moved Only 8%.
Hey Trader,
Before the market opens again, read this…
My top trader, Thomas Wood, just released a new strategy he calls Opening Bell Trades.
This simple system is designed specifically to help regular investors generate income from his #1 trade setup.
I’m talking about finding monster winners like these…
- 113% on GOOGL
- 240% on META
- 70% on CAG
- 37% on MCD
- 139% on GLD
Best of all, he looks for these trades every morning starting at 9:30 AM and by 10 he’s done.
Everything you need to know about how this works is in a free report called “The Opening Bell Trade Guide”…
Take a few seconds and download FREE right now before this link stops working.
This report won’t be free forever, so grab it now while you can.
Once it’s on your computer, you’ll have it for good-no matter what we charge other traders for it later.
No credit card required. No strings attached.
>> Get Your FREE “Opening Bell Breakouts” Trade Guide Here
This guide shows you the exact 15-minute window trade he uses, and how to spot the setups the big funds are watching.
FREE: Discover One Simple Options Trade You Can Make Each Morning – and Be Done by 10 AM.
To better trading,
Drew Day
Founder & CEO
Base Camp Trading
P.S. Inside, you’ll see why Thomas uses weekly options and how to use them to trade stocks like GOOGL, META, and TSLA with as little as $75. Go here to save a copy of the “Opening Bell Trade Guide” before its taken down.
Super Micro Beat by 47%. The Stock Moved Only 8%.
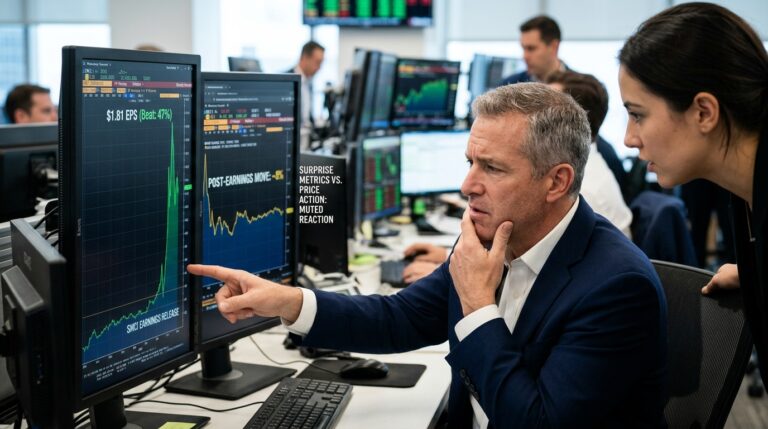
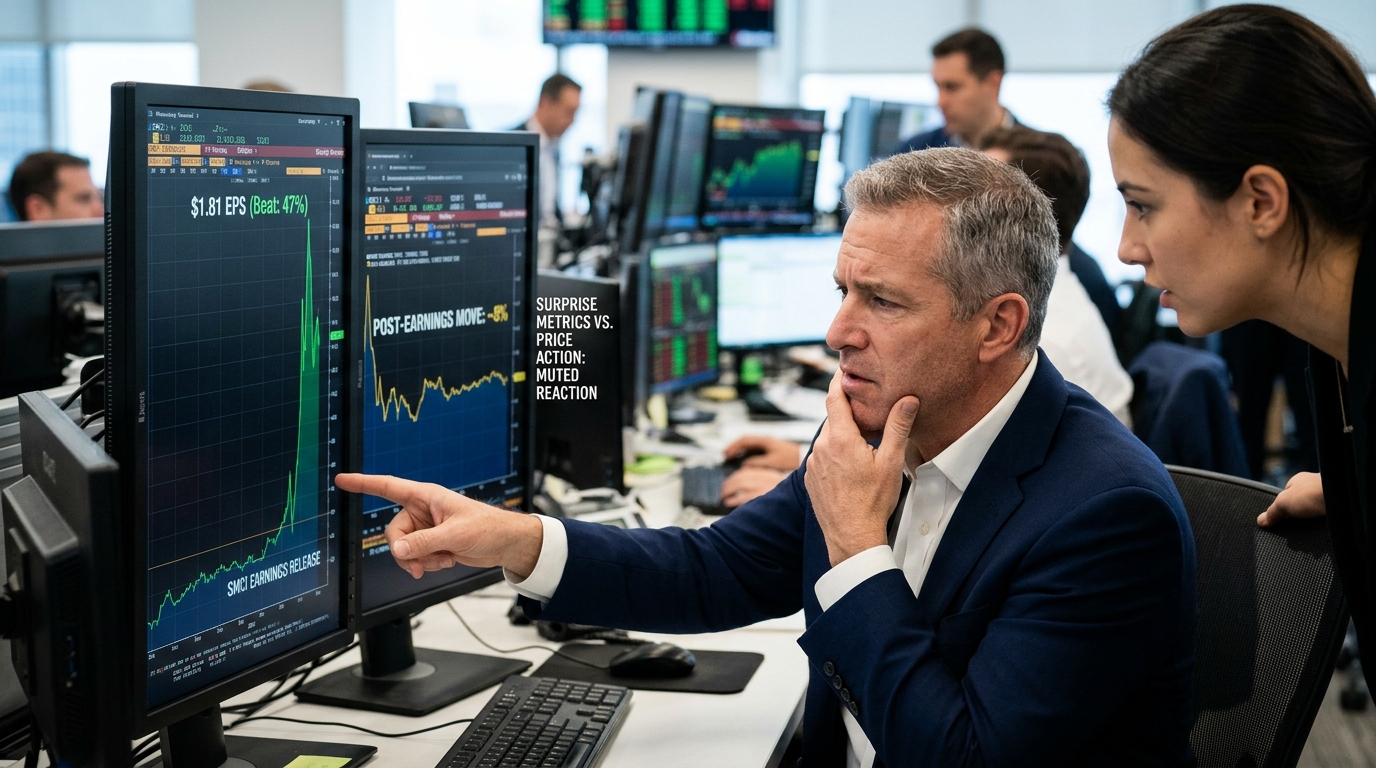
Markets don’t reward the size of a beat. They reward surprise. Super Micro Computer delivered one of the more decisive earnings beats of this AI hardware cycle on Tuesday evening, posting non-GAAP EPS of $1.81 against a consensus of $1.23, a 47% overshoot, while revenue came in at $19.9 billion against the $16.26 billion Wall Street expected. Adjusted net income was not disclosed in the company’s earnings release, but GAAP net income was $1.594 billion. And the stock, in one of the most reliably volatile names in the index, moved roughly 7-8% in after-hours and Asian trading.
That gap is worth examining carefully. Options expiring November 6 had implied a larger potential move in either direction, but widely published estimates vary. The realized move is landing near the bottom of that envelope. This is not a failure. It is data.
The Numbers
Net sales reached $19.9 billion versus $11.1 billion in the prior quarter and $5.0 billion a year ago, while GAAP gross margin came in at 12.7% versus 17.5% in the prior quarter and 9.3% a year ago. The year-over-year margin recovery is the number that mattered most heading into this report. Non-GAAP gross margin expanded to 12.8% in the quarter, compared with 9.5% in the year-earlier period, easing a key investor concern.
For Q2, the company guided revenue of $19.5 billion to $21.5 billion against analyst estimates near $17.5 billion, with non-GAAP EPS of $1.60 to $1.90 versus a consensus near $1.14. The company did not raise full-year fiscal 2027 revenue guidance to $72 billion to $82 billion in its earnings release. Every line above consensus.
Why the Reaction Was Smaller Than the Beat
Part of this was already priced. On October 20, the company pre-announced revenue of $18.5 billion to $19.5 billion versus prior guidance of $14.5 billion to $15.5 billion. Sophisticated market participants had already adjusted. At-the-money implied volatility ahead of the report was widely cited around 200%, meaning options buyers were paying generously for a move that, in the end, fell short of the implied range.
The gross margin at 12.7% also carries an asterisk, but not the one originally described. The company did not disclose a $2.3 billion catch-up revenue item in the earnings materials or call transcript that would reduce reported revenue to $17.6 billion. Strip away the headline and you still have the same signal: a growth engine that is running hot, and a margin profile the market still treats as fragile.
Sector Implications
SMCI’s results extend a pattern across the AI server triad. Dell, SMCI, and HPE are all seeing surging AI infrastructure demand, record backlogs, and stronger guidance as data centers expand AI buildouts. HPE’s Cloud and AI revenues hit $9.0 billion in Q3 fiscal 2026, up 25.4% year over year, with a 17.0% operating margin, a far superior margin profile to SMCI’s current 12.8%. Dell, meanwhile, exited Q1 fiscal 2027 with a $51.3 billion AI backlog and has said it expects $60 billion in AI server revenue in its fiscal year ending January 2027. SMCI wins on growth velocity. Its peers win on margin. That tension is unresolved.
The margin gap between SMCI and its peers is not the only place where strong AI infrastructure numbers have failed to satisfy the market. Lam Research beat on every line and still fell 6% after hours, a pattern that shows how crowded AI equipment trades punish even genuine outperformance.
Options Market Analysis
Before the report, the options market was positioned for a large binary move. Call volume outpaced puts on the November 6 expiration in widely circulated flow recaps, a clear call-side lean. That elevated activity and sub-1.0 put/call ratio signaled a bullish tilt among options traders favoring calls over puts.
Post-event, the picture shifts. Specific post-earnings implied volatility levels, IV Rank, and IV Percentile readings vary materially by data provider and timestamp, so the clean takeaway is structural: implied volatility fell sharply after the event, and the premium that made selling volatility attractive before the report was largely removed. The event-driven opportunity has passed. What remains is a directional question at reduced volatility levels.
Structured Trade Framework
Bull case: If you believe the demand cycle supports another quarter near the high end of management’s Q2 revenue guide and gross margins hold above 12%, a defined-risk long structure through a December call spread can express upside while limiting exposure to renewed margin skepticism. SMCI’s mean analyst target has been cited at $43.27, and forward valuation screens vary by provider and earnings basis, so treat single-number multiples as directional rather than definitive.
Bear case: For traders expecting margin pressure to reassert itself, a put spread into the next earnings window provides defined-risk exposure to a retest of the $30 area. A short-term retest of the $30 mark cannot be ruled out.
Neutral case: With the event resolved, short-premium structures generally carry less edge than they did pre-earnings. A defined-risk iron condor bracketing the recent post-earnings range can express a mean-reversion view, but it requires discipline on the upside wing given SMCI’s historical tendency to move aggressively after earnings. Published estimates for SMCI’s typical post-earnings move differ by sample window, but it has frequently been a double-digit mover.
Risk Analysis
The core risk is the same one that has followed SMCI for two years: margin durability. Despite strong profitability, third-party models have recently shown SMCI’s free cash flow yield as deeply negative, reflecting heavy working-capital and reinvestment demands. Revenue growth is a compelling headline. Cash generation is not yet keeping pace. BofA Securities analyst Ruplu Bhattacharya has maintained an Underperform rating in recent coverage, citing margin and execution risk.
Forward Outlook
The next hard data point is the Q2 report, which the company has indicated should follow the close of its fiscal second quarter ending December 31, 2026, typically reported in early February. Analysts’ near-term EPS estimates can lag management’s guidance immediately after a reset quarter. That gap sets up another potential beat cycle, provided the demand environment holds and no supply constraints emerge. The company guided Q2 gross margin to 12% to 12.5% and flagged the usual constraints: supply availability, mix, and macro uncertainty.
Action Checklist
- Monitor SMCI’s regular-session open on November 4 against the after-hours levels for confirmation of overnight gains.
- After the post-earnings volatility reset, treat premium selling as less compelling than it was into the event; directional defined-risk spreads tend to screen better when the volatility premium is thinner.
- Focus on what management said it can repeat: Q2 revenue of $19.5 billion to $21.5 billion and gross margin of 12% to 12.5%.
- Watch DELL and HPE for sympathy moves; AI server sector-wide re-ratings can lift or compress SMCI independent of its own fundamentals.
- Key risk events: any NVDA supply commentary, macroeconomic guidance revisions, or audit-related filings ahead of the next earnings window.