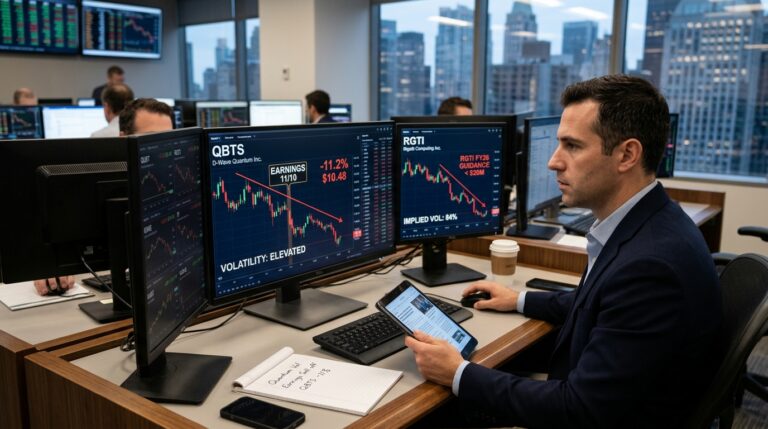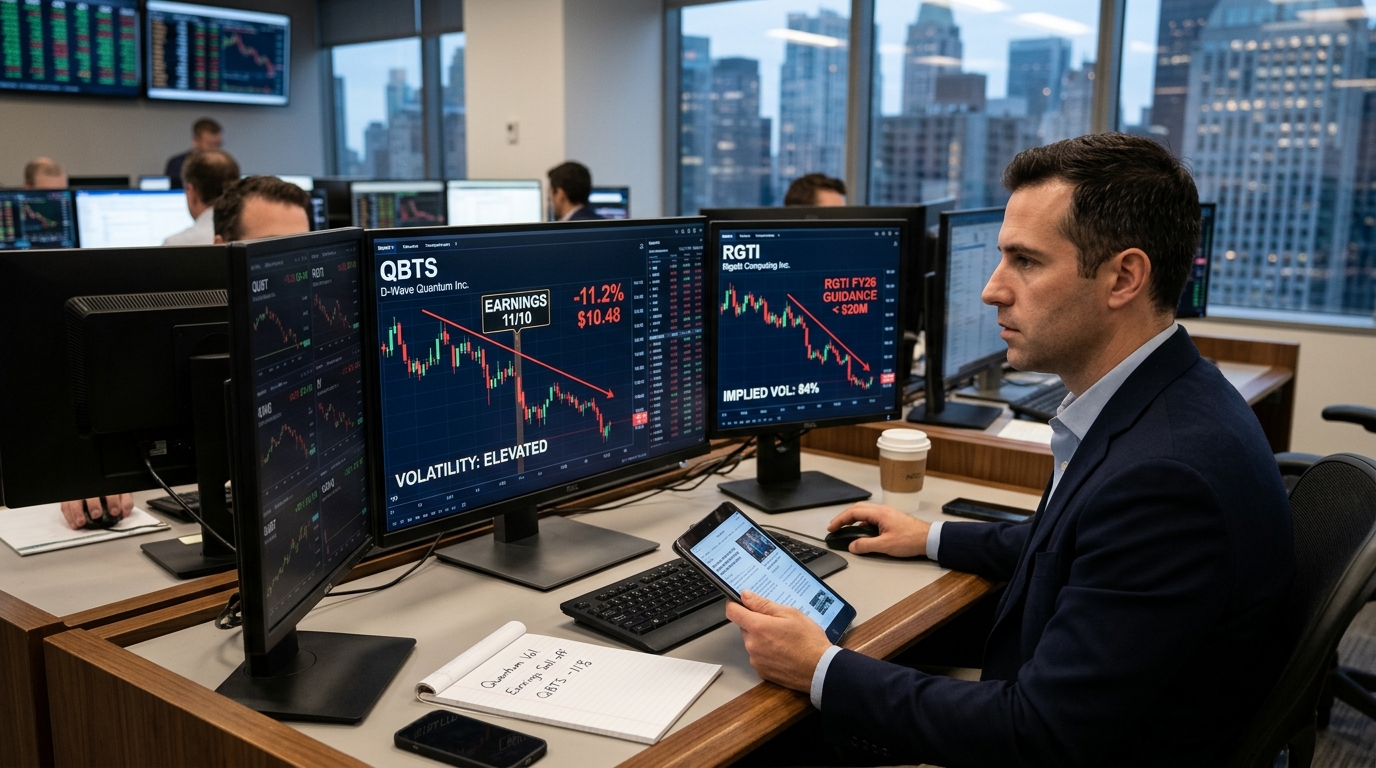
Markets don’t need a reason to buy speculative growth. They only need one to sell it. On November 10, the quantum computing group supplied two in a single session.
D-Wave Quantum (QBTS) reported before the open and fell as much as 11% intraday, closing around $10.48. Rigetti Computing (RGTI) followed after the bell, dropped more than 9% in extended trading, and carried that weakness into Wednesday morning. Neither result was catastrophic on its face. Both were enough to remind traders that in a sector priced on potential, the distance between a revenue beat and a good reaction is wider than it looks.
What the Numbers Actually Said
D-Wave posted Q3 revenue of $4.51 million, up 21% year-over-year and modestly above consensus estimates. The beat was real. So was everything underneath it. Operating expenses surged 84% year-over-year to $55.9 million. GAAP gross margin fell to 52.9% from 71.4% a year earlier, driven by a revenue mix shift toward lower-margin professional services. The GAAP loss came in at $0.13 per share. Quarterly bookings fell 19% year-over-year to $1.9 million, even as nine-month bookings surged 611% to $37.4 million. D-Wave’s adjusted EBITDA loss widened 83% to $37.7 million on $4.5 million in quarterly revenue. That math tells you exactly why the stock moved the way it did.
Rigetti’s report was more direct. Q3 revenue came in at $1.4 million, well below consensus estimates and down from $1.9 million in the same quarter a year earlier. The non-GAAP loss was $0.06 per share. Operating loss widened year-over-year to $33.2 million, with R&D costing about $25.5 million in the quarter. Full-year 2026 guidance was set at approximately $20 million, and management said it assumes a Q4 customer acceptance and associated revenue recognition from India’s C-DAC. Remove that one deal and the guidance doesn’t hold.
The Context That Matters
This is not about one bad quarter. It’s about what the group was priced for before these reports arrived.
IonQ (IONQ) reported on November 5 and delivered Q3 GAAP revenue of $173.8 million, up 336% year-over-year, raising its full-year 2026 revenue guidance to $505-$515 million. That set the tone for the rest of the group. But by November 10, the sympathy bid had already faded. The sequence exposes something structurally important: QBTS and RGTI were not moving on their own fundamentals. They were moving on IonQ’s. When their own results arrived, the correlation snapped.
That snap came after a punishing October. D-Wave declined roughly 36% and IonQ fell approximately 32% over the 30 days prior to the IonQ report, a drawdown that left implied volatility elevated across the entire group heading into earnings week.
That drawdown did not happen in a vacuum. The Nasdaq correction that erased more than a trillion dollars in tech value pushed implied volatility higher across every speculative growth pocket, quantum included.
Options Market Analysis
QBTS 30-day implied volatility was roughly in the mid-90% to low-100% range in the days surrounding the report, depending on the specific expiration used, with IV percentile readings that sat near the middle of its own 1-year range. Rigetti’s near-term implied volatility was also elevated in the high-double-digits to low-90% area. Put/call ratios can vary by source and whether you use volume or open interest, but positioning into earnings leaned call-heavy in many snapshots, reflecting optimism that the C-DAC delivery story would hold. It did not, at least not in Q3.
The key observation for premium sellers: both stocks moved violently on earnings, but neither broke outside the implied expected move. That is exactly the environment where selling premium with defined risk earns its edge.
Structured Trade Framework
Bear case. For traders expecting continued deterioration in quarterly bookings at D-Wave or further revenue misses at Rigetti, a defined-risk put spread captures directional exposure while limiting the binary risk that high IV creates for outright long puts. A 30-45 day put vertical on QBTS below current levels, financed by selling a lower strike, keeps the debit manageable against an elevated IV backdrop.
Neutral case. With implied volatility still elevated in both names, a short strangle or iron condor on either QBTS or RGTI prices in meaningful premium while the stocks find their post-earnings range. If you believe the worst of the news is in the price and volatility compresses, the credit spread structure extracts that compression. Define the risk with long wings outside the expected move.
Bull case. If you believe D-Wave’s $38.3 million remaining performance obligation converts on schedule and the C-DAC acceptance closes Rigetti’s Q4 gap, a risk-defined call spread captures the upside without fully paying the IV premium that an outright long call demands.
Risk Factors
Rigetti’s full-year outlook explicitly assumes a single Q4 contract acceptance. If C-DAC slips into 2027, the ~$20 million revenue target is at risk. D-Wave reported consolidated cash and marketable investment securities of $503.4 million as of September 30, 2026. The burn rate matters, and both companies remain pre-profit with no quantitative forward guidance on earnings. Sector correlation to AI sentiment means macro or big-tech shocks move these names independent of company-specific news.
Forward Outlook
IonQ’s $1.2 billion backlog and 336% revenue growth set a credible commercial ceiling for where this sector can go. D-Wave and Rigetti remain two to three tiers below in revenue scale. The dispersion inside the group is now explicit, not theoretical. Traders pricing these three names as a single basket will be wrong more often than they were six months ago.
Action Checklist
- Confirm current IV rank or IV percentile on QBTS and RGTI before entering any premium-selling structure; when IV is elevated versus its own history, credit spreads tend to compare better than debit structures.
- Size any defined-risk structure to no more than 2-3% of portfolio given the binary event risk still present in RGTI’s C-DAC Q4 acceptance.
- Monitor Rigetti’s C-DAC delivery confirmation as the single most important near-term catalyst for the stock.
- Watch D-Wave’s quarterly bookings trajectory. Nine-month bookings are strong; the Q3 single-quarter decline bears watching in Q4.
- Avoid treating IONQ, QBTS, and RGTI as a single trade. The group has fractured on fundamentals.