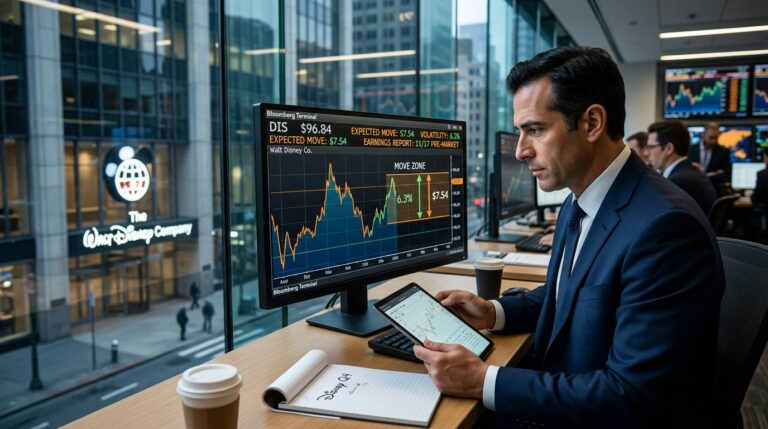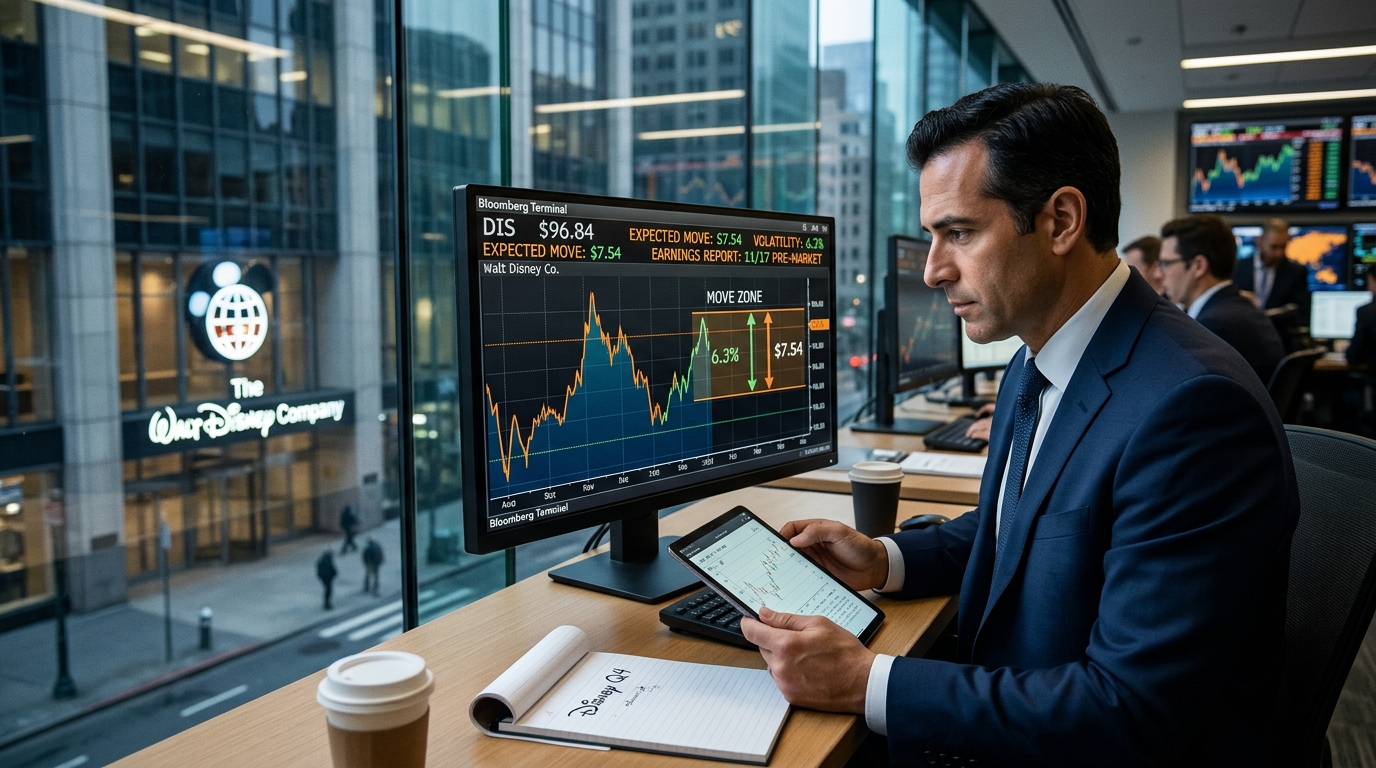
Markets don’t need a great quarter. They only need one that beats what was already priced in. That distinction matters enormously for Disney heading into Tuesday’s pre-market release, where the options market has staked out a $7.54, or 6.3%, expected move in either direction.
Walt Disney is set to report its fourth-quarter fiscal 2026 earnings on November 17 before the market opens, with options traders pricing in a potential 6.3%, or $7.54 per share, swing in the stock following the results. That implied move is not unusual for Disney around earnings. What is unusual is the asymmetry between the magnitude of the consensus growth expected and the stock’s recent habit of declining despite delivering beats.
The Numbers
Consensus has Disney posting $1.69 in adjusted EPS, up from $1.11 a year ago, representing expected EPS growth of 52.3%. Revenue is forecast at about $25.25 billion, up 12.3% year-over-year. Management guided Q4 total segment operating income to approximately $4.9 billion, including the impact of the 53rd week.
In Q3 FY2026, Entertainment generated $11.35 billion in revenue, up 6% year-over-year, while operating income rose 64% to $1.68 billion. Advertising revenue declined 1%, reflecting a softer advertising environment. Disney+ SVOD operating margin was about 13% in fiscal Q3.
Beat vs. React: The Structural Disconnect
Disney has beaten the Street’s EPS estimate in every quarter of fiscal 2026. The stock has not always cared. Shares rose about 2.6% to 2.9% following Q3 FY2026 results on August 5. However, the stock declined after each of its Q2 FY2026, Q1 FY2026, and Q4 FY2025 earnings announcements. The Q1 drop was particularly severe: the company’s stock fell roughly 5% to 6% following those results.
This is not about whether Disney can beat $1.69. Disney’s earnings have surpassed the consensus estimate in each of the trailing four quarters. The question is whether the guidance and commentary around parks trajectory, ESPN sports rights costs, and streaming margin durability will give investors a reason to hold through Nvidia’s simultaneous close the same day and Walmart’s report two days later.
The pattern of beating estimates and still selling off is not unique to Disney. Amazon posted record margins and 39% cloud growth and still fell 9% when one line on the income statement disappointed.
The company enters the report with stronger streaming and Experiences trends, but sports costs, Asia parks demand, layoffs, and valuation remain central investor concerns.
Options Market Analysis
The implied move is calculated using options expiring November 20, the first expiration after the announcement. Using Disney’s November 11 closing price of $119.65, the November 20 call option was priced at $3.62, while the corresponding put was at $3.92, bringing the straddle premium to $7.54.
The most recent earnings announcement on August 5 produced about a 2.6% to 2.9% price change, well below the 6.3% implied move. On May 6, the stock moved about 6.5% against a roughly 6.8% implied move. In other words, the options market has consistently overpriced the realized move, except when sentiment was already constructive. Put pricing at $3.92 against a $3.62 call reflects a modest downside skew, consistent with a market that respects the downside risk in a crowded calendar week.
Structured Trade Framework
Bull case: For traders expecting Disney to beat and guide higher on streaming margins and Q1 FY2027, a defined-risk long call spread in the November 20 or December expiry, buying the $120 call and selling the $127 call, captures upside to the analyst consensus price target of $129 without full premium exposure to a 6.3% implied move.
Bear case: If you believe sports rights costs disappoint or management softens FY2027 guidance, a put spread buying the $119 put and selling the $112 put defines the $7 of implied move on the downside with contained cost. The put skew already prices in some of this fear.
Neutral case: A defined-risk iron condor selling the $127 call and buying the $131 call on the upside, while selling the $112 put and buying the $108 put on the downside, profits from the stock staying inside the implied range, as it did in August when the realized move was only about 2.6% to 2.9%.
Risk Analysis
The crowded macro context is real. This marks the second quarterly report under new CEO Josh D’Amaro, who took the reins on March 18, 2026. Leadership transition risk compounds the binary event. Sports segment operating income in Q3 fell 17% on higher programming costs tied to new rights agreements. Any negative revision to FY2027 double-digit adjusted EPS growth guidance would likely overwhelm the headline beat.
Forward Outlook
The company has said it expects fiscal 2027 to deliver double-digit adjusted EPS growth, excluding the impact of lapping the 53rd week. It also lifted its fiscal 2026 share repurchase target to at least $9 billion. Those are the structural props under the stock. Whether Tuesday’s report adds another leg or removes one depends almost entirely on what management says about FY2027 trajectory after the 53rd-week tailwind expires.
Action Checklist
- Confirm position sizing relative to the $7.54 implied move before Tuesday’s open
- Watch Q4 total segment operating income vs. the guided $4.9 billion figure
- Track streaming SVOD margin: does it hold near the Q3 level of about 13%?
- Monitor Sports segment commentary on NBA and college rights cost trajectory into FY2027
- Assess Asia parks language for any demand deterioration guidance
- Note whether FY2027 double-digit adjusted EPS growth is reaffirmed unconditionally or qualified
- Compare realized move at close to the 6.3% implied level to evaluate whether premium sold or bought was well-priced
All options structures described are for analytical illustration. This analysis does not constitute investment advice. Options trading involves significant risk of loss. Defined-risk structures limit maximum loss to premium paid.