September 18, 2026
Bonus Content: Progressive’s August Numbers Land Today. Here’s What the Combined Ratio Trend Is Telling You.
AI’s NEXT Magnificent Seven
Dear Reader,
The Original Magnificent Seven Produced 16,894% Average Returns Over 20 Years.
$1,000 in each turned into $1.18 million!

But the Man Who Called Nvidia at $1.10 Says “AI”s Next Magnificent Seven Could Do It Even Faster.”
He says $1,000 in these seven stocks could turn into $1 million+ in less than six years.
See His Breakdown of the Seven Stocks You Should Own Here.
Sincerely,
Rachel Gearhart
Publisher, The Oxford Club
P.S. The first company on his list just signed a MAJOR deal with Apple.
The company’s tech is going to be included in the iPhone and iMac until 2040!
That’s why Alex says this company might be America’s 7th trillion dollar company.
Progressive’s August Numbers Land Today. Here’s What the Combined Ratio Trend Is Telling You.
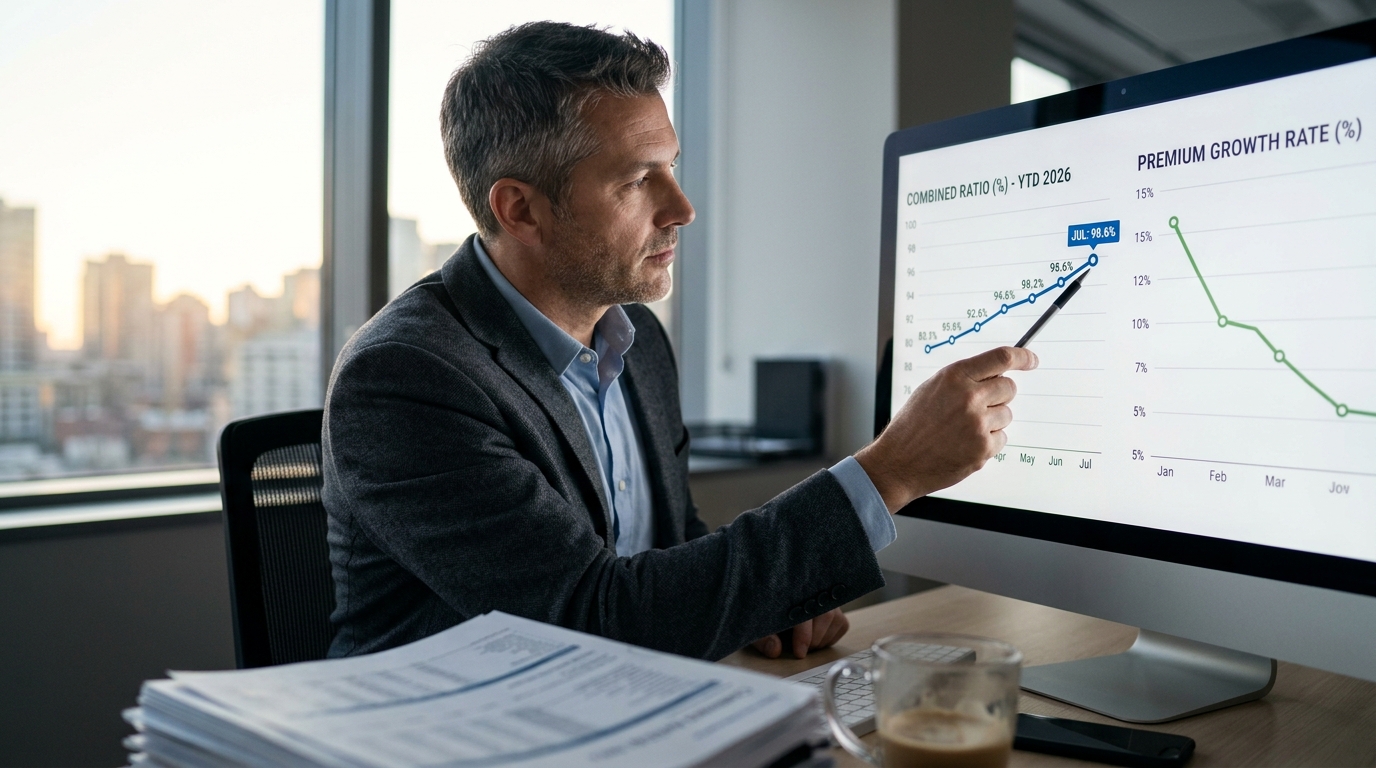
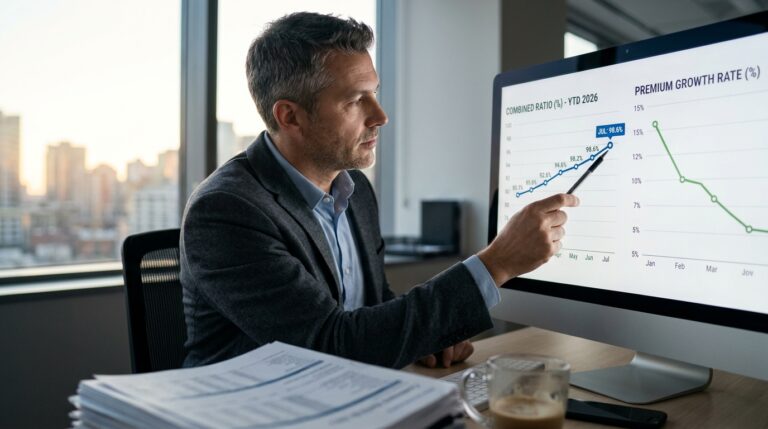
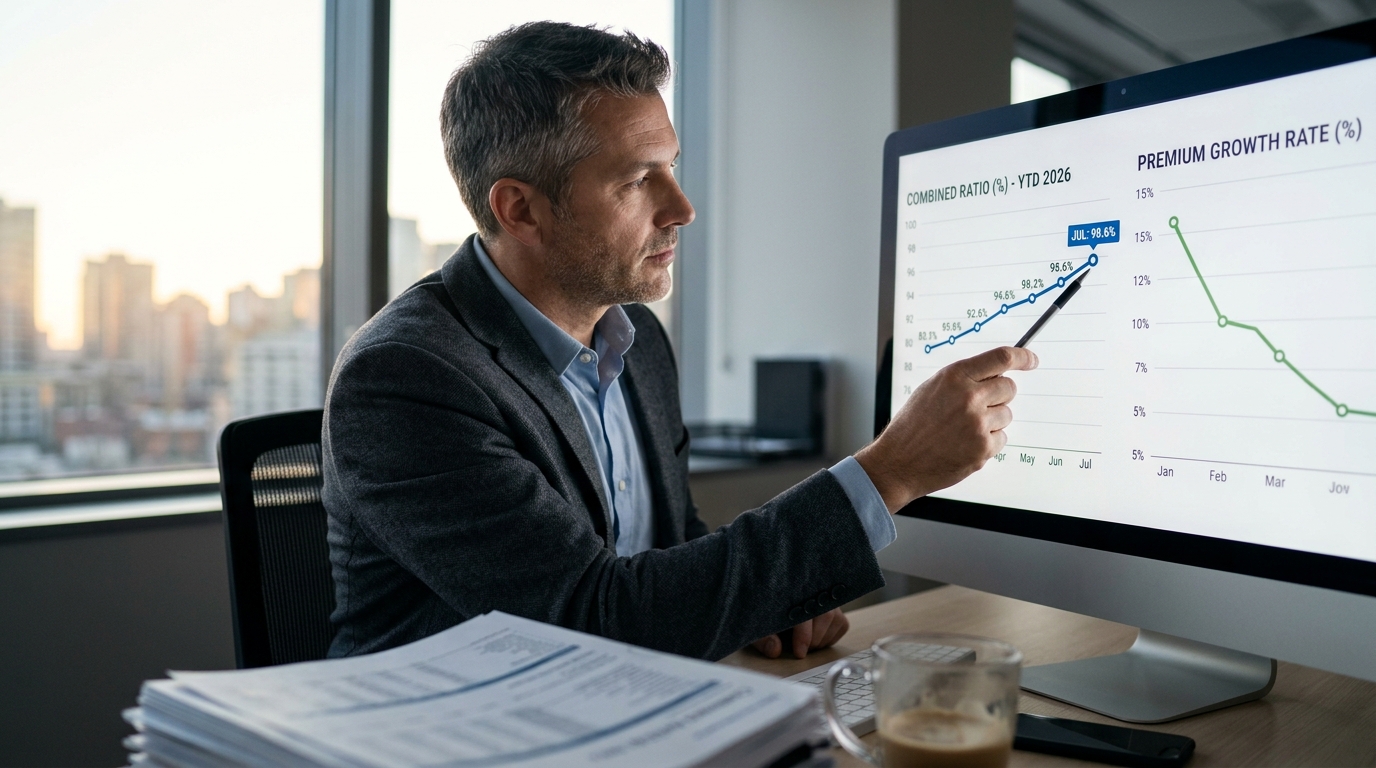
Progressive (PGR) releases its August 2026 monthly results before the open today, and the number that matters most is not net income. It is the combined ratio, and whether the creeping deterioration visible across the first seven months of the year has continued or paused.
This is not a routine disclosure. August is the first month of Q3, and its combined ratio provides the market’s earliest quantitative read on whether Progressive’s underwriting discipline is holding as the company pushes into less familiar corners of the auto insurance market to sustain premium volume.
The Data Trail Into Today
Progressive’s Q2 2026 combined ratio came in at 87.3, compared with 86.2 in Q2 2025, while net premiums written for the quarter were approximately $21.1 billion, up 5% year over year. That growth rate tells its own story: in the first half of 2025, net premiums written increased 15%; in the first half of 2026, growth slowed to 6%.
July extended the same pattern, with net premiums written of $7.441 billion, up 5% from $7.057 billion in July 2025, while net income fell 12% to $961 million. The July combined ratio rose to 86.8 from 85.3, an increase of 1.5 percentage points year over year. Three consecutive months of widening, all while growth decelerates. August is the first chance to break that chain.
Strategic Interpretation
Markets are not pricing in a collapse. Progressive’s market capitalization sat near $126.4 billion as of the latest close (September 17), with the stock trading in a 52-week range of $189.20 to $249.71. PGR closed at $216.19 heading into this release, which implies the consensus view is benign drift, not structural deterioration.
The bear case is not that the combined ratio spikes past 90. Progressive’s long-run underwriting discipline benchmark is a 96 combined ratio, so the stock is nowhere near that threshold. The real concern is what the growth slowdown signals about market saturation. It appears the company may be taking on less attractive business to continue growing, expanding into risk tranches that compress margins over time. If August shows a combined ratio above 87.5 alongside sub-5% premium growth, that interpretation gains traction.
Progressive achieved the milestone of becoming the largest U.S. personal auto writer in the trailing 12-month period as measured by direct premiums written, which means incremental share gains from here require competing in markets where GEICO and Travelers (TRV) have long held pricing discipline. Size makes the next percentage point of growth harder, not easier.
Sector Read
In Q1 statutory data for the top 20 auto carriers, Progressive grew direct written premiums by $1.3 billion while the remaining 19 carriers lost a combined $1.3 billion, which reflects an industry-level pricing environment that remains supportive. Allstate (ALL) and Berkshire’s GEICO unit have been raising rates and shedding unprofitable policies. That dynamic has handed Progressive clean volume. If August shows premium deceleration sharpening toward 3%, it would suggest the competitive tailwind is fading faster than management’s guidance implied.
Options Market Analysis
PGR options into today’s release reflect moderate event pricing. Progressive’s monthly releases historically move the stock 1.5% to 3.5% on the day, depending on how far the combined ratio deviates from consensus. With PGR trading around $217 to $220 heading into the open, the at-the-money expected move prices in roughly a $5 to $7.50 range, or approximately 2.3% to 3.4% in either direction.
Insurance company monthly disclosures compress post-event volatility faster than quarterly earnings calls because there is no guidance update and no management Q&A. Implied volatility often rises ahead of expected price moves and falls after events like earnings announcements, making a volatility contraction after today’s open the base case regardless of direction. For traders holding premium-long positions through today, the IV crush risk is meaningful even if the number surprises.
An IV percentile above 80% suggests options are expensive relative to history, while below 20% suggests they are cheap. PGR’s IV has been trending toward its seasonal floor given the post-Q2 quiet period, suggesting option buyers are not being compensated generously for directional bets today.
Structured Trade Framework
Bull case: August combined ratio prints at or below 86.8, net premiums written grow 6% or better. For traders expecting that outcome, a defined-risk structure such as a long call spread expiring in October captures upside toward $235 while capping premium at risk ahead of the Q3 full earnings cycle.
Bear case: Combined ratio widens above 87.5 and premium growth slips below 5%. A put spread in the $210 to $200 range, expiring late October, defines the risk while targeting the level where institutional holders likely reassess valuation support.
Neutral case: The number lands in line and the stock trades flat to up 1%. An iron condor straddling the $210 to $230 range captures premium decay after the event-vol crush without directional exposure.
Risk Analysis
Catastrophe exposure is the wildcard in any August insurance read. Progressive filed an 8-K in August 2026 covering its catastrophe reinsurance program, signaling active management of the tail risk. A heavy cat month in August, whether from Gulf storms or Midwest convective events, could push the combined ratio well above trend and render pre-release positioning moot.
Analysts cite anticipated slower premium growth and an increase in the core loss ratio as primary headwinds, with policyholder growth rates expected to decline as competitors’ rate increases taper off, further exacerbated by seasonal loss trends.
Forward Outlook
August will be followed by September results in mid-October, simultaneous with the Q3 earnings release. That is where full analyst consensus has teeth. Today’s release matters most as a momentum signal. A stable or improving combined ratio with premium growth holding at 5% or above leaves the bull case intact and the stock range-bound. A second consecutive month of sub-5% growth with widening loss costs changes the framing heading into Q3, and the options market will price that shift quickly.
Analyst consensus is Hold on PGR, with published price targets spanning roughly the high-$100s to the mid-$200s across major aggregators. The spread in those targets reflects genuine disagreement about whether today’s growth deceleration is cyclical or structural. August’s combined ratio number moves that argument one way or the other.
Action Checklist
- Confirm August combined ratio versus the 86.8 July read and the 87.3 Q2 result.
- Check net premiums written growth rate: below 5% is a deterioration signal; above 6% is stabilization.
- Note policies in force growth. Total policies in force were 40.3 million as of July 31, 2026, up 7% year over year. Any deceleration in PIF growth narrows future premium runway.
- Watch the opening move relative to the implied expected move. A gap beyond 3.5% in either direction suggests the market is reassessing the structural growth story, not just the month.
- Size any options position to account for IV crush post-open. Defined-risk spreads are preferable to outright long options in low-IV-rank environments around single-month disclosures.