September 25, 2026
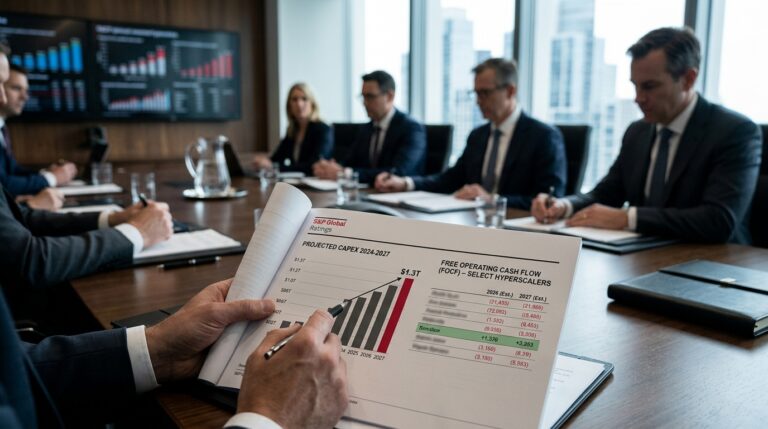
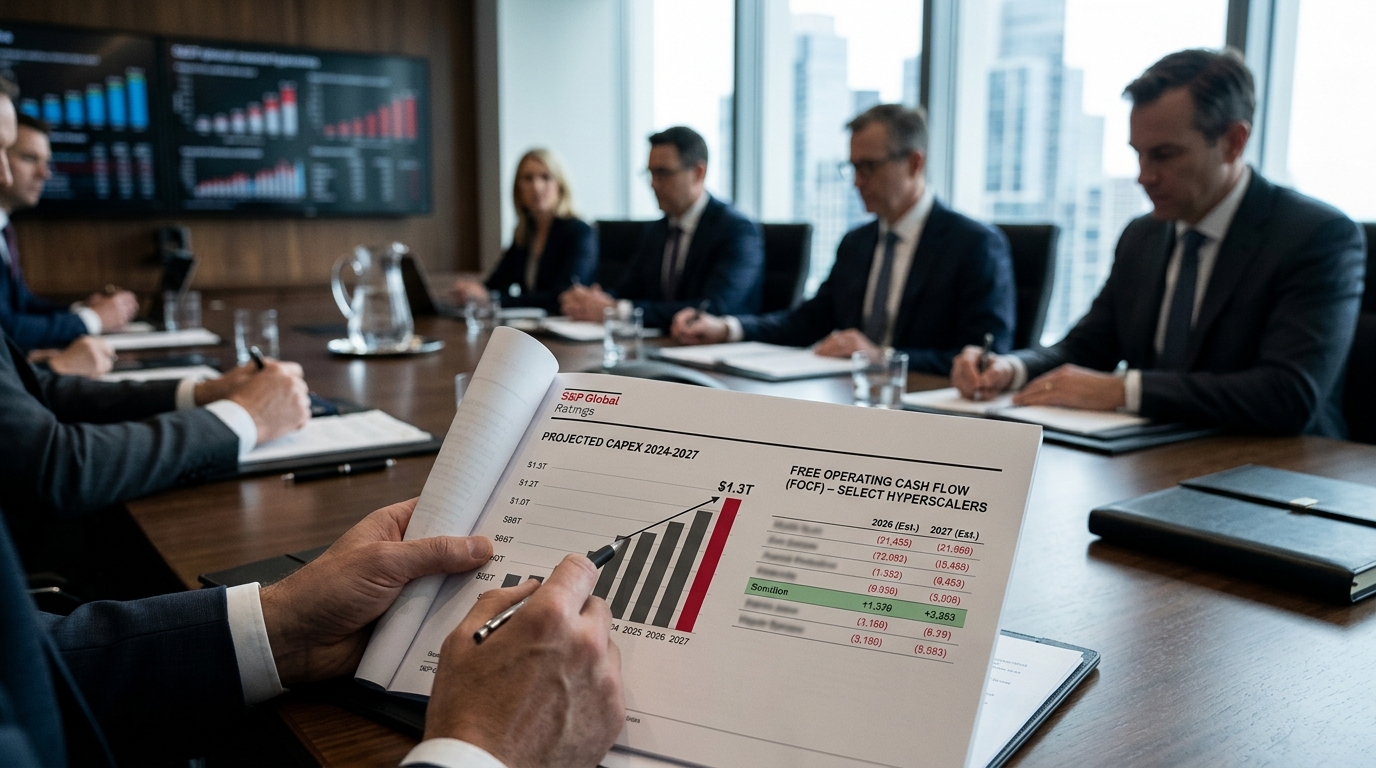
S&P Global projects $1.3T in capex by 2027, with negative free operating cash flow for six hyperscalers in 2026 and 2027.
The math is not complicated. It is just uncomfortable. Combined hyperscaler capital expenditure is projected to exceed $1.3 trillion by 2027, with negative free operating cash flow expected across the six largest hyperscalers in both 2026 and 2027. That single statistic, from S&P Global Ratings in late August, reframes the entire AI infrastructure trade: this is no longer a revenue story. It is a financing story, and the options market has not caught up.
The Playbook Every Options Trader Should Have!
Do you dream of retirement but it seems like an impossibility? Wish you knew the best moves to get you there sooner?
It’s closer than you think and you won’t have to work overtime to get it!
Hi! I’m Dave Aquino, expert options trader and my e-book, “How To Master the Retirement Trade” has helped thousands reach their goals!
Follow the link to get your copy and see what you’ve been missing!
This week made the abstraction concrete. On September 24, Akamai announced a seven-year, $11.6 billion cloud deal with Anthropic and immediately disclosed the cost of winning it: total capital expenditures related to the commitment are estimated at approximately $5.5 billion, with roughly $1.7 billion in additional capex hitting in 2026 alone to pre-purchase critical supply chain components, including memory. On the same day, Oracle issued a force majeure notice to Blue Owl Capital, the developer of its Project Jupiter campus in New Mexico, letting it delay payments if the site is not running by 2028, after a natural gas pipeline tied to the site was delayed following repeated permit denials by the New Mexico State Land Office. Oracle’s fiscal 2026 free cash flow was negative $23.7 billion.
The Crossover Calendar
The crossover date differs by company. On current trends, Oracle has already crossed, Amazon is crossing around now, Alphabet around Q1 2027, Meta around Q3 2027, and Microsoft around Q3 2028. Epoch AI modeled this by fitting exponential growth curves to operating cash flow and capex from Q2 2023 onward, and the trajectory is unambiguous.
Alphabet’s balance sheet captures the scale of the shift. In June, the company launched an $80 billion equity raise, with Berkshire Hathaway committing $10 billion. Alphabet has raised substantial fresh capital over 2026 to fund AI infrastructure, and the company has warned that capex pressure can tighten near-term free cash flow even as revenue grows. The market read the raise as confidence. The more precise read is tolerance for ambiguity, and tolerance has a price.
That ambiguity has a derivatives footprint worth examining on its own terms. The options market began flagging unusual pricing dynamics around Alphabet well before the equity raise closed, and understanding what traders were positioning for then sharpens the read on where implied volatility sits now. what the derivatives market was pricing ahead of Alphabet’s capex inflection offers a baseline for how much the vol surface has — or has not — adjusted to the balance sheet shift.
In 2025, investment-grade bond issuance from hyperscalers totaled $108 billion, roughly 26% of capex. Through the first half of 2026 they had already issued $194 billion. Goldman Sachs expects 2027 IG issuance to reach $400 billion, or roughly 35% of an estimated $1.14 trillion in capex. Debt is not a bridge. It is the foundation.
“Market Wizard” Who Made Hundreds of Millions for Clients Reveals Two-Rule Strategy
Trading legend reveals how any American can go for their first $1,000 using his simple two-rule system.
What Options Are Pricing
This is where the asymmetry lives. Long-dated implied volatility on the hyperscalers remains structurally low relative to the cash flow inflection these companies are approaching. Alphabet implied volatility has historically expanded around earnings, major AI product updates, and antitrust headlines. That range was built in an era when Alphabet generated free cash flow consistently. The capex cycle is testing that assumption.
The options market is still pricing these names as if the capex cycle is a temporary detour rather than a structural regime. S&P Global expects all six hyperscalers to generate negative free operating cash flow in 2026 and 2027, with recovery not projected until 2029, and notes that hyperscalers are increasingly utilizing debt, equity issuance, lease commitments and other financing arrangements. A two-year window of externally funded capex at this scale is not in long-dated put pricing on GOOGL, AMZN, or META.
Structured Trade Framework
Bull case (MSFT): Microsoft is the one hyperscaler commentators keep highlighting as the outlier on cash generation. Microsoft has reported that total AI revenue surpassed $37 billion in annual run rate, up 123%. For traders expecting the AI monetization cycle to accelerate, a defined-risk long call spread in MSFT dated to Q1 2027 earnings captures the FCF-positive divergence at relatively low cost.
The bull case for Microsoft rests on whether Azure’s growth trajectory is already reflected in the share price or still represents a genuine discount to intrinsic value. That question was examined in detail after Azure posted a standout quarter that appeared to settle the debate about whether AI infrastructure spending was translating into cloud revenue. the analysis of whether Azure’s growth quarter was already priced into MSFT is the right companion read before sizing any call spread into Q1 2027.
Bear case (ORCL): Oracle carries the most asymmetric downside. It now carries about $125 billion in long-term debt on the books, and as of August 31, 2026 it disclosed $288 billion of additional lease commitments, substantially all related to data center arrangements, that had not yet started. A defined-risk put spread targeting Q2 2027, when campus financing stress could manifest in credit markets, is structurally warranted.
5 Nasdaq Stocks Under $5 That Aren’t What You Think
Most stocks under $5 come with a reputation. These don’t.
Each company on this list is tied to major trends like AI, cybersecurity, and next-gen infrastructure.
They may not have the spotlight yet, but they are building real businesses in real markets. That combination is not always easy to find at this price level.
Neutral case (GOOGL): S&P Global’s work assumes a later-cycle inflection as capex growth moderates and AI-driven revenue scales. Whether that inflection actually materializes and generates strong returns on invested capital is the central question investors are trying to answer. For traders who want exposure without directional conviction, a long strangle using LEAPS straddles the expected crossover window, buying volatility that is priced for a calmer outcome than the balance sheet warrants.
Risk Analysis and Forward Outlook
The primary risk to the bear case is demand durability. Hyperscalers are leaning more heavily on long-term contracted demand signals, including performance obligations and backlog. The growing use of joint ventures, special purpose vehicles, residual value guarantees and other structures is increasing the complexity of credit analysis, and key areas being monitored include monetization of AI investments, demand durability, overcapacity risk and the treatment of contractual commitments and other debt-like obligations.
Oracle’s force majeure filing is a signal worth watching precisely because it is not unique. Any centralized campus running the same build-first, solve-power-later model faces the same physical constraint. The options market is priced for the revenue upside. It is not priced for the infrastructure delay.
Oracle’s backlog figures complicate the bear case in one important way: contracted demand is real, and a selloff driven purely by capex fear may be conflating timing risk with demand risk. Those two risks carry very different implications for put spread sizing and expiry selection. the case that Oracle’s selloff is misreading the risk behind its backlog lays out the counterargument that any trader structuring bearish exposure on ORCL needs to stress-test before committing capital.
Action Checklist
- Compare long-dated IV (Dec 2027 expiry) across GOOGL, AMZN, META, MSFT, ORCL before the Q3 earnings cycle begins; GOOGL and AMZN show the clearest FCF crossover timelines with the least vol premium attached.
- For defined-risk bearish exposure on ORCL: consider put spreads spanning the Q2 2027 earnings window, after Project Jupiter’s 2028 target date either holds or slips.
- For MSFT long exposure: evaluate call spreads targeting the post-Q2 2027 period when FCF divergence from peers becomes quantifiable in filings.
- Monitor Oracle-related Project Jupiter financing headlines alongside Oracle’s own disclosed debt and lease-commitment trajectory. Stress tends to surface in credit first.
- Watch for any revision to S&P Global’s recovery timing. A pushed-out recovery date changes the cohort’s funding math.