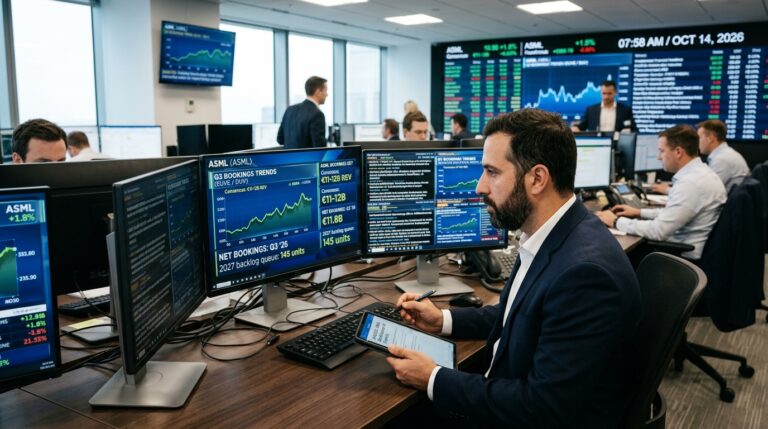
Markets already know ASML can deliver. What they do not know is whether the queue for 2027 is holding. That distinction makes Wednesday’s report one of the most consequential data points in semiconductors this quarter, and it has nothing to do with whether the company beats by a few cents.
ASML will announce Q3 2026 results on Wednesday, October 14, 2026, before the market opens. Consensus estimates vary by source, but the cleanest anchor ahead of this report is the company’s own Q3 revenue guidance of €11.0 billion to €12.0 billion rather than dollar-based figures. For context, Q2 came in at €7.59 per share on €9.3 billion in total net sales, a beat that prompted ASML to raise full-year guidance.
What the Numbers Say
After Q2, ASML guided Q3 revenue between €11.0 billion and €12.0 billion at a gross margin of 55% to 57%, and lifted full-year 2026 revenue guidance to €43 to €45 billion. Consensus has settled near the top of that range. The tension is not whether ASML reaches those figures. It is whether management signals any softening in the order book that feeds 2027 system deliveries.
Earnings estimates for ASML in 2026 and 2027 have drifted lower in parts of the sell-side ecosystem even as the AI outlook strengthened. That drift matters because management has said it is already close to having the orders it needs for 2027, alongside plans to add roughly 30% EUV capacity in 2027 versus 2026. If demand is as tight as that implies, estimate reductions should not be happening. The bookings line on Wednesday will either resolve that contradiction or deepen it.
The macro context around Wednesday’s report is hard to ignore. TSMC reported record third-quarter revenue of NT$1.49 trillion, up about 51% year over year, driven by strong demand tied to AI and leading-edge nodes. Separately, TSMC and ASML disclosed a High-NA EUV collaboration focused on a shift to 12-inch EUV photomasks, which both companies described as a productivity and cost lever for High-NA EUV exposure. TSMC’s own earnings call lands Thursday, one day after ASML. The sequencing matters: ASML’s bookings number will frame how analysts interpret everything TSMC says about capacity spending.
Options Market: What the Move Is Priced At
Options are not cheap here, and the range of implied move estimates reflects genuine disagreement about magnitude. The options market is pricing a mid-single-digit to high-single-digit move into the October 16 expiry depending on the data source and timestamp, with different vendors producing different point estimates.
The stock’s earnings-day history supports why implied volatility is elevated, with post-earnings moves frequently clustering in the mid-single digits but with occasional larger outcomes. Elevated IV before this report reflects the fat-tail history, not just the base case.
Structured Trade Framework
Bull case. If you believe bookings confirm 2027 capacity demand holds and management raises the gross margin floor above 55%, a defined-risk bull call spread targeting a 6 to 8% move captures that outcome without naked exposure to a miss. The Q2 pattern, where a guidance raise drove a sharp reaction, is the template.
Bear case. If you expect a bookings figure below €5 billion, or management commentary that characterizes High-NA EUV adoption as slower than the backlog implies, a defined-risk bear put spread with strikes bracketing current price and a break-even within the implied move would express that view. Management has highlighted visibility into 2027 demand, so the bear case requires a specific deterioration in tone, not just a modest revenue miss.
Neutral case. For traders expecting ASML to land inside consensus with no bookings surprise, the elevated implied volatility can create a short-premium opportunity. An iron condor using the October 16 expiry, with wings set outside the prevailing at-the-money expected-move estimate, profits from that kind of contained reaction. Max risk is defined at entry.
Risk Factors
High-NA EUV execution challenges and export restrictions remain the primary downside risks. Management has signaled China’s share of 2026 net sales around 20%, down from elevated levels previously. A bookings number dominated by memory rather than logic customers could revive questions about demand breadth. On the upside, any indication that capacity constraints are pulling 2027 orders forward would reset estimates sharply higher across the SOXX complex.
Action Checklist
- Bookings figure: watch for anything below €5bn as a negative signal, above €7bn as a positive one
- Gross margin guidance: confirmation of 55-57% range is table stakes; a raise toward 58% is the upside catalyst
- High-NA EUV commentary: volume delivery cadence for 2027 is the key forward read
- Check TSMC’s Thursday call for corroborating or conflicting capacity spend language
- Size any options position to withstand the historical tail risk of outsized post-earnings moves