October 25, 2026
Bonus Content: Applied Materials Builds the Machine Behind Diamond Power
The “buy and hold” crowd is not going to like this…
But I found a way to pinpoint one structured trade during a short morning window. Before most people have finished their second cup of coffee!
I call this simple market move the “Last Retirement Trade.“
Last Retirement Trading is built around…
One ticker retirement traders are quietly using every morning.
One short morning window between 9:30 and 10:45 AM.
One approach with entry and exit plans fully defined before you ever place a trade…
Of course, not every trade will win. (But you already knew that right?)
However, even when you account for the occasional loss, following a structured morning framework can be a far more profitable approach than chasing the next ticker.
Click Here To Get the Free “Last Retirement Trade” Report →
To Your Success,
Drew Day
President, Base Camp Trading
P.S. A “Last Retirement Trade” window is about to open. Click Here To Get the Free “Last Retirement Trade” Report.
Applied Materials Builds the Machine Behind Diamond Power
Markets have spent 2026 obsessing over AMAT’s role in 2nm gate-all-around logic. That story is real. But a second revenue vector is forming in the background, one tied not to AI chip scaling but to the physical infrastructure of the electrical grid, and the material at its center is synthetic diamond.
The physics are not subtle. Diamond carries a bandgap of 5.47 eV, nearly twice that of silicon carbide, and a critical breakdown field of about 10 MV/cm. Its thermal conductivity runs to roughly 2,200 W/m·K at room temperature, about five times copper. Those numbers mean a diamond-based power switch can, in principle, handle voltages above 10 kV without the exotic cooling stacks that SiC and GaN demand at similar power densities. Where silicon melts and SiC strains, diamond operates.
This is not a 2030s theoretical. In June 2026, Element Six and Orbray announced a reproducible process for 3-inch wafer-scale single-crystal diamond, with 4-inch substrates already in development. Diamond power MOSFETs and Schottky diodes targeting multi-kilovolt operation and high-temperature performance are in active development across industry and national labs. The CVD diamond market itself was valued at $583 million in 2026 and is projected to reach $1.22 billion by 2035 at a 7.7% CAGR.
Diamond power electronics do not operate in isolation from the rest of the grid buildout. Large power transformer lead times have already stretched to 30 to 36 months, concentrating pricing power in a short list of suppliers with locked order books.
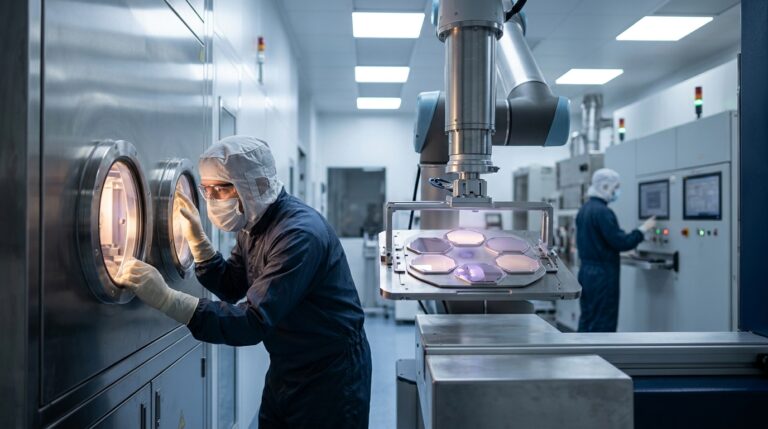
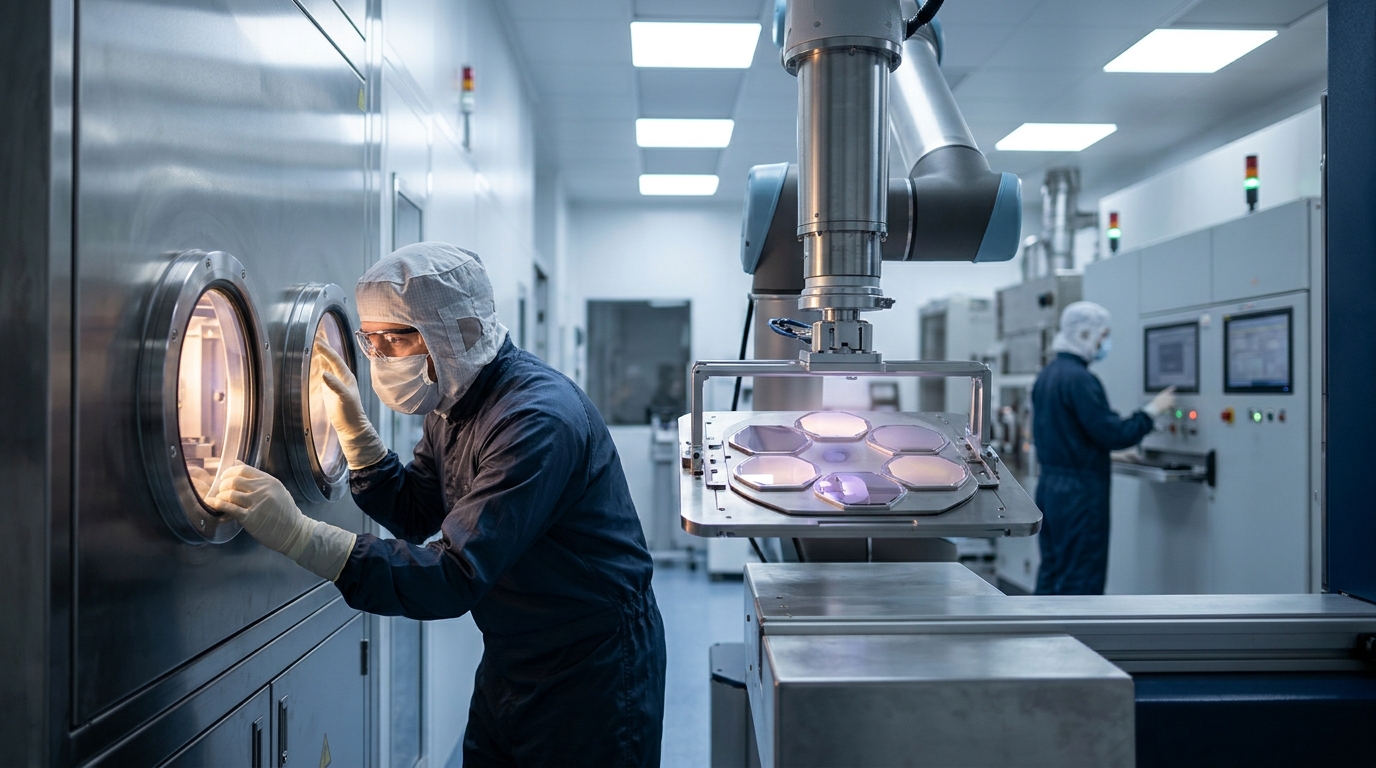
Applied Materials sits at the bottleneck. AMAT commands leading global share in CVD and PVD deposition equipment, the precise process class required to grow synthetic diamond substrates with the crystallographic purity that power electronics demand. Its Centura platform is a widely deployed deposition architecture. The same atomic-level process control it applies to 2nm gate-all-around transistors is what diamond wafer producers need to control nitrogen concentration down into semiconductor-grade territory.
The company’s Q3 FY2026 report, released August 13, posted revenue of $9.12 billion against an $8.99 billion consensus, with non-GAAP EPS of $3.50 versus a $3.40 estimate. Management said it had further raised its calendar 2026 Semiconductor Systems revenue growth expectations beyond the prior greater-than-30% level, after earlier raising expectations from above 20%. Q4 FY2026 reports November 12, with consensus EPS at $4.06. Full-year estimates sit at $12.79 per share on $34.25 billion in revenue.
The options market has priced AMAT’s average earnings move at roughly 6.5% over 40 reports, and the actual move exceeded the implied range in 11 of the last 17 events. The August report saw options price a 7.3% move; the stock closed down 5.1%. IV rank as of early October stood near 25, which is historically low relative to the stock’s realized volatility profile heading into a report of this magnitude.
Structured Trade Framework
Bull case: If you believe AMAT’s November 12 report confirms that Semiconductor Systems growth is holding above 30% and management flags early CVD tool inquiries from wide-bandgap substrate producers, a defined-risk long call spread in the November or December expiry captures upside while the IV rank remains compressed. The $299 billion market cap at current levels prices the AI cycle; it does not yet price the grid.
Bear case: For traders expecting guidance conservatism or a repeat of the post-earnings drift that followed the August report, a defined-risk put spread structures the downside without unlimited exposure to a stock that has beaten estimates in every quarter since November 2024.
Neutral case: With IV rank near 25 and the stock down roughly 26% from its August post-earnings high, an iron condor centered on the current range acknowledges that the near-term catalyst is the November 12 report, not the diamond wafer cycle, which has no hard revenue contribution in this quarter’s numbers.
Risk Analysis
Diamond substrate commercialization remains a longer-dated revenue event for AMAT. The company’s China exposure and wafer fabrication equipment cycle volatility are the near-term risks the market is actually pricing. Needham lowered its price target from $740 to $580 on October 16, 2026. The diamond angle is a structural positioning argument, not a Q4 earnings trade.
Action Checklist
- Watch the November 12 report for any mention of wide-bandgap or advanced substrate CVD tool inquiries in the ICAPS (mature node) or specialty segment commentary.
- Monitor IV expansion into the November 12 close. If implied move prices above 8%, premium selling structures become more attractive relative to directional plays.
- Track Element Six and Diamond Foundry partnership announcements. Equipment supply agreements with CVD diamond producers would be the first concrete signal that AMAT’s substrate deposition portfolio is being pulled into the grid electronics market.
- Compare the Q4 $4.06 EPS consensus against the full-year $12.79 estimate. Any guidance compression on the fiscal 2027 outlook would reset the valuation case independent of the diamond thesis.