October 5, 2026
Bonus Content: Plus500 and CMC Fell With IG. The Problem Is IG’s Alone.
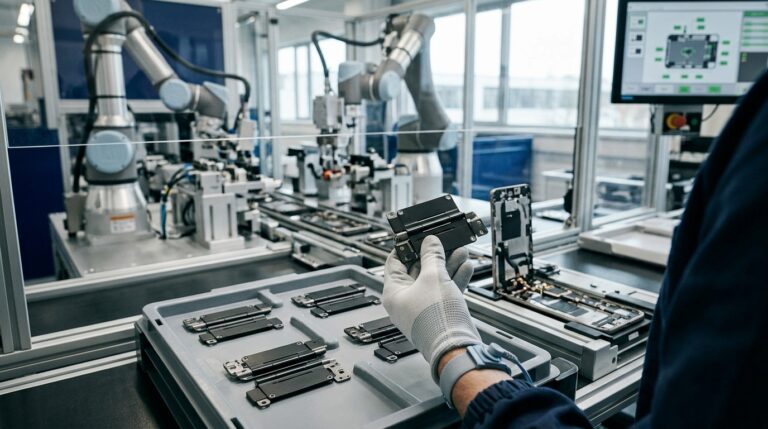
Washington Wants the Next Drone Boom Built in America
America wants to dominate the next great weapons market.
For generations, military strength was measured by the size of a nation’s ships, tanks and aircraft. But the next era may belong to something smaller, faster and more intelligent: Drones.
Drones can gather intelligence, move critical supplies and complete missions without putting pilots at risk.
And Washington is moving to bring that industry home. A new Executive Order calls for expanded domestic production, secure supply chains and greater military adoption of American-made drones.
The global drone market was valued at $83.8 billion in 2025 and is projected to reach $182.4 billion by 2033. A nearly 120% increase!
North America already accounts for more than 40% of that market. Yet one Chinese company still controls roughly 70% of the U.S. civilian drone market.
Washington wants to change that.
And with the Pentagon reportedly seeking around 300,000 drones, investors may want to know which American companies could benefit.
One little-known Nasdaq company has spent more than 25 years developing professional drone technology. It has patents, a broad product lineup and real-world deployments behind it.
If America leads the next drone revolution, this overlooked company may finally get Wall Street’s attention.
Plus500 and CMC Fell With IG. The Problem Is IG’s Alone.
Markets don’t need a sector-wide problem. They only need the fear of one. On Friday, October 2, IG Group delivered a shock that had nothing to do with customer demand and everything to do with how efficiently it converts that demand into revenue. The sector sold off anyway, and that gap between cause and consequence is where the defined-risk question sits today.
IG Group’s Q3 total revenue is expected to be approximately £240 million, a 14% drop from the same period a year earlier. The company now expects total 2026 revenue growth in the mid-single-digit percentage range year-on-year, down from guidance issued in May of 10% to 15%. Prior to the update, company-compiled consensus had forecast 2026 revenue of £1.26 billion, following 2025 revenue of £1.12 billion. The stock closed roughly 23% lower.
The Numbers Behind the Collapse
IG attributed the fall to lower OTC revenue retention, the share of OTC trading flow it keeps as revenue. Retention was about 70% in Q3, against an average of roughly 80% since market-making optimisation measures were introduced in the second half of 2025. OTC net trading revenue came in at approximately £155 million, around 18% lower year-on-year, even as OTC customer income increased by approximately 8%. Customers kept arriving. IG just kept less of what they generated.
Organic first trades rose more than 25% year-on-year and active customers climbed about 17%. That is not a demand story. It is a market-making efficiency story, and it is specific to IG’s internal model.
Strategic Interpretation
CMC Markets was dragged lower despite the warning being related to IG’s profitability, not to overall customer numbers or activity. CMC fell as much as 10% before recovering to close down 4%. Plus500 was down 14% at its worst before recovering to close down 5%. Neither company had reported anything. The market priced them on proximity alone.
This is not about sector fundamentals deteriorating. It is about contagion pricing in the absence of data.
The Signals That Separate IG From Its Rivals
Both CMC and Plus500 moved to contain the damage within hours. Plus500 confirmed it continues to trade in line with current market expectations for FY 2026 and maintains a strong cash position, as previously communicated on 10 August 2026. The company pointed explicitly to its proprietary risk management framework and its track record across various market cycles. A full Q3 trading update is scheduled for later this month. That update is the binary event traders need to anchor positions around.
At CMC, the signal came from the controlling shareholder. Lord Peter Cruddas, CMC’s founder and CEO, bought approximately £139,000 of shares in the open market on Friday and told the board he intends to make further purchases totalling up to £5 million, including Friday’s transaction. Cruddas founded CMC Markets in 1989 and remains its controlling shareholder. In his own words, he has never sold any shares since the 2016 IPO and intends to make further investments in the near term.
Options Market Analysis
CMCX and PLUS are London-listed equities; exchange-traded options are thinly traded relative to US-listed peers. For PLUS specifically, the defined-risk question centres on the full Q3 update arriving later in October, which functions as a known catalyst. Implied volatility on both names spiked sharply last Friday on the IG shock and has not fully unwound. That elevated premium environment rewards defined-risk long structures for traders who believe the sympathy selloff was misapplied. A bull call spread or long call with controlled expiry beyond the Plus500 update captures the rerating scenario without open-ended downside. For CMC, Cruddas’s stated intent to deploy up to £5 million buys some floor support, though CMC Markets has a market capitalisation of more than £1.7 billion, so £5 million is not transformative in absolute terms. The floor it sets is psychological as much as mechanical.
Structured Trade Framework
Bull case: For traders expecting Plus500’s full October update to confirm continued strong performance, a defined-risk long call structure into that catalyst captures the rerating from a 14% sympathy discount. The position benefits if the update reaffirms what management already said on October 2.
Bear case: If you believe IG’s retention deterioration reflects broader OTC market conditions rather than an IG-specific model failure, protective put structures on CMC or Plus500 into the update would hedge against a second-leg selloff. The risk is paying elevated post-shock premium for protection that may already be over-priced.
Neutral case: A short strangle or iron condor on PLUS ahead of the update monetises premium if the stock consolidates in a range between Friday’s recovery close and the pre-shock level. This suits traders who expect the update to confirm guidance but see limited upside beyond fair value.
Risk Analysis
The core risk is that Plus500’s full Q3 update reveals its own version of IG’s retention problem. The October 2 statement gave no revenue figures, no retention rate, and no numeric guidance beyond confirming alignment with August expectations. Plus500 has therefore offered reassurance without a number, and no retention figure. That is exactly the kind of gap that can hurt a long position if the full update disappoints. Size accordingly.
Action Checklist
- Verify Plus500’s full Q3 update date once announced; structure any long position to expire after it, not before.
- Monitor CMC for further Cruddas purchase disclosures, each of which requires a separate regulatory filing.
- Distinguish IG’s OTC retention rate (70% vs. 80% average) from any figure Plus500 or CMC discloses; they are not interchangeable metrics.
- Track whether IG Group’s strategy update on October 22, 2026 reframes the retention issue as temporary or structural. That read-across will move CMC and Plus500 again.
- Use defined-risk structures only. The event risk is real; the sympathy selloff created opportunity, but the binary update removes the right to be wrong cheaply without a cap on losses.