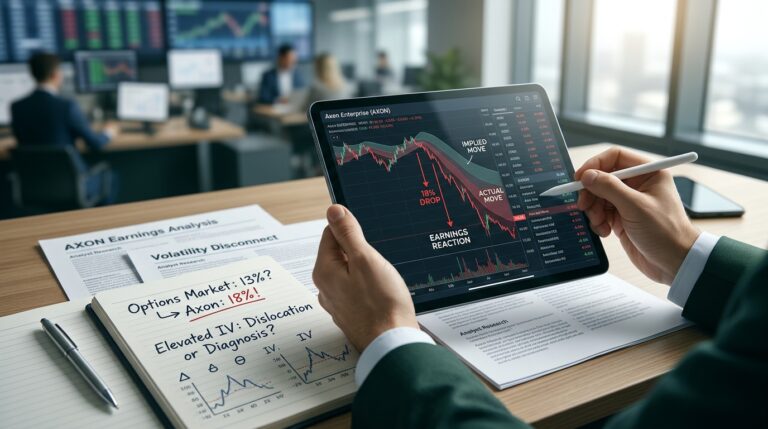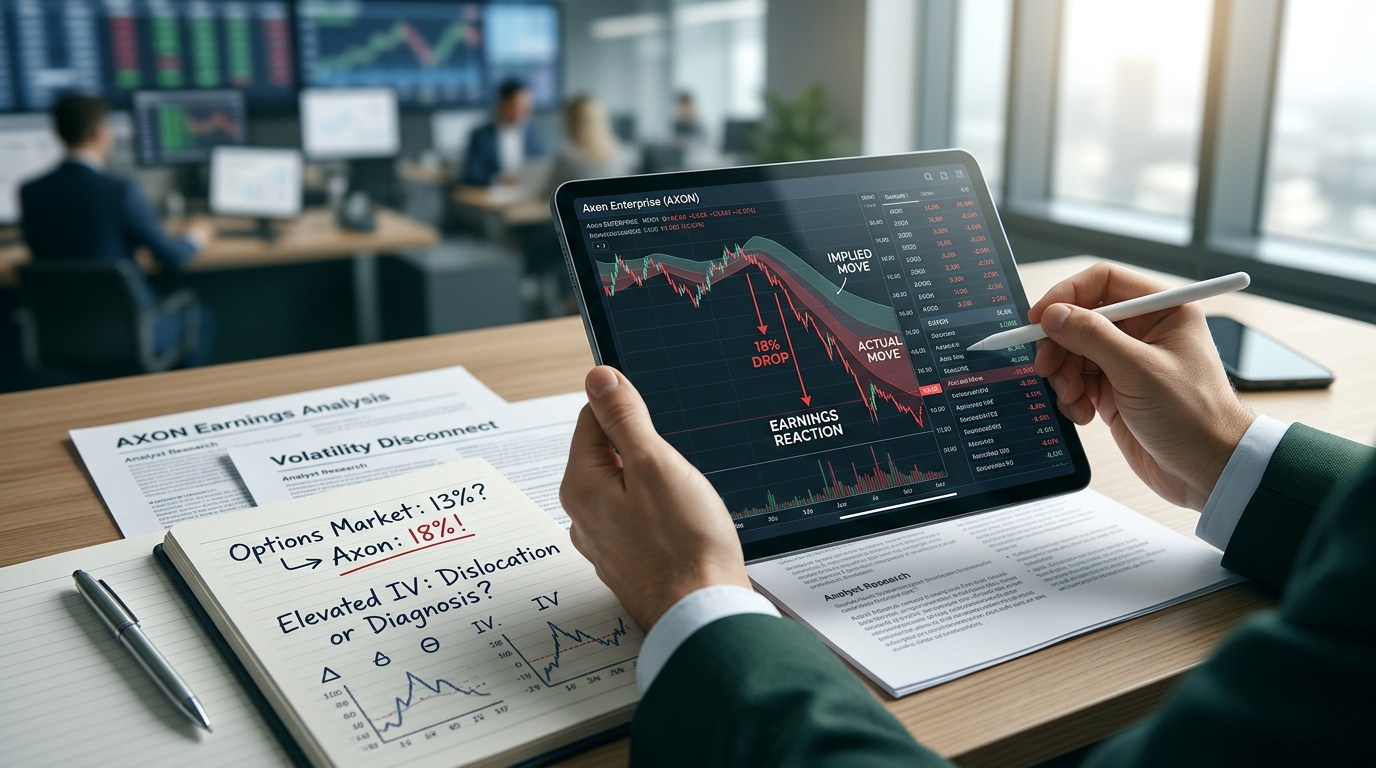
Axon has a habit of moving more than options traders expect. Heading into Thursday’s report, the options market priced roughly a 13% swing, in line with a pattern where the stock has outrun implied moves in six of its past eight earnings announcements. The actual move: Axon tumbled 18.2% on Friday, blowing past what premium buyers and sellers alike had modeled. That gap matters for structuring positions now.
Q3 revenue came in at $908.6 million, representing about 27.9% year-over-year growth. Adjusted EPS was $1.72. Total gross margin declined to 56.7% from 60.1% as newer, hardware-intensive product categories scaled. The EPS gap was not a rounding error; the Connected Devices segment saw adjusted gross margin contract to 44.6% from 52.1% in the year-ago quarter, primarily due to a higher mix of counter-drone equipment and elevated memory costs.
The Dedrone Hole
This is not a demand story. One approximately $30 million Federal Dedrone deployment was expected in Q3, and management said three Federal Dedrone deployments totaling approximately $130 million had been contemplated in prior second-half expectations. Those deployments slipped. The company said the reduction reflects the exclusion of those three Federal Dedrone deployments from its 2026 outlook, and it noted that if they had remained on pace, full-year growth would be nearly 500 basis points higher than current guidance.
Axon lowered its 2026 revenue forecast to $3.61 billion-$3.63 billion from a prior outlook of 32% to 34% annual growth. Fourth-quarter guidance of $990 million-$1.01 billion came in well below where the Street had been modeling. Free cash flow guidance was also cut, from $450 million to $350 million-$400 million, as the company accelerates inventory growth for supply chain resilience. Motorola Solutions, Axon’s closest competitor in public safety technology, faces no comparable federal deployment exposure, which may draw capital away from AXON in the near term.
What Remains Intact
Annual recurring revenue increased 40% to $1.8 billion, and net revenue retention remained at 126%. Software and Services revenues surged 43.2% year-over-year to $437 million, supported by customer additions and higher adoption of premium software solutions. The underlying business is not broken. The quarter is.
Options Market: Elevated and Actionable
Post-earnings, AXON’s implied volatility, IV percentile, IV rank, and the next-seven-days expected move need to be checked against live option chains; this draft’s figures cannot be verified from company filings. That spread between realized and implied volatility is wide when the post-event market keeps pricing uncertainty. Put/call flow was skewed heavily toward protection into the report, and those positions have largely paid. What the market now prices is elevated uncertainty about the federal procurement timeline, not a collapsed business.
At least five brokerages cut price targets after the report. UBS lowered its target to $380 from $470. Other specific firm-by-firm target changes and any claimed median target level should be verified against the firms’ notes or a consolidated analyst feed before publication.
Structured Trade Framework
Bull case: If you believe the Dedrone slippage is a procurement timing issue and ARR growth above 40% is the durable signal, a defined-risk structure such as a bull put spread below current levels, sold at elevated IV, collects premium while capping downside exposure. The $300 level represents a potential structural floor given two-year lows.
Bear case: For traders expecting federal budget uncertainty to extend delays into 2027, with memory costs persisting as a margin headwind, a bear call spread above $350 captures continued compression at high IV without unlimited upside risk.
Neutral case: With IV elevated and realized volatility running below implied, a short strangle or iron condor centered near $313 targets IV compression as the event premium decays. The weekly expected move defines the outer rails.
Risk Factors
Management flagged elevated memory costs as a driver of margin pressure this quarter. Axon also committed up to an additional $1.2 billion to Skydio on November 5, 2026, structured as a mix of cash and Axon stock. That capital allocation adds balance sheet weight at the same moment free cash flow guidance was cut. Any further federal procurement delays would pressure 2027 guidance.
Action Checklist
- Confirm position sizing relative to the weekly expected move before initiating any directional structure
- Elevated IV favors premium sellers; IV crush risk is real for long-premium buyers at current levels
- Monitor Dedrone contract announcements from the federal government as the primary re-rating catalyst
- Watch Q4 revenue print against the $990 million-$1.01 billion guide as the binary event for 2027 guidance credibility
- Track ARR and net revenue retention as the structural health indicators, independent of lumpy hardware deployments