Dear reader,
Most investors wait for the government press conference.
I follow the money before the cameras show up.
And the money trail now leads straight to one tiny nickel stock.
Its U.S. platform has already been selected for $135.4 million in disclosed federal grants: $114.8 million tied to a domestic processing facility and another $20.6 million supporting exploration in Minnesota and Michigan.
That is not a prediction. That’s money already disclosed.
The next step is my forecast: I believe Washington could eventually go further and take an equity stake.
It may never happen. But the U.S. has already shown it is willing to put taxpayer capital directly into strategic mineral companies. And this company now controls the only primary nickel mine operating in America.
Meanwhile, Tesla has locked in a six-year supply agreement, and America remains dangerously exposed to foreign nickel supply.
Russia, China, and Indonesia have leverage because the United States allowed its domestic pipeline to wither.
This little company is one of the few credible ways to fight back.
That’s why I bought 10,000 shares before any equity announcement.
I am not promising Washington will buy in. I am saying the grants, the operating mine, the Tesla agreement, and the strategic pressure form a setup I refuse to ignore.
Click here to learn more about the $5 nickel stock I believe Washington could target next.
Yours for peace, prosperity, and liberty, AEIOU,
Dr. Mark Skousen
Macroeconomic Strategist, The Oxford Club
P.S. Washington has already backed this platform with $135.4 million in disclosed grants.
If an equity stake comes next, I believe a stock this small could move violently.
I refuse to wait for the press conference.
Click here to reveal details on what I bought before Washington makes its next move.
Take-Two Reports Monday. GTA VI Ships Nov. 19. The Price Already Knows.
Markets don’t need a great story. They need a surprise. And on Monday, November 9, Take-Two Interactive reports a quarter where the most important product in the company’s history has not yet shipped, generated not one dollar of revenue, and cannot change a single line of the income statement. The question is not whether GTA VI will sell. The question is whether anything management says after the market close can move a stock that has already climbed about 13% from its October 30 close to its November 6 close.
This is not about earnings. It’s about guidance, tone, and the gap between what traders expect and what Strauss Zelnick actually delivers on that 4:30 PM ET call.
What the Quarter Contains
The quarter being reported covers the three months ending September 30, and it closed before GTA VI ships, so these results will not include a single dollar of post-launch sales. Analysts expect Take-Two to post earnings of $0.97 per share on revenue of about $1.64 billion for Q2 2027. Management’s own guidance called for net bookings of $1.62 to $1.67 billion and GAAP net revenue of $1.42 to $1.47 billion.
At Zynga, mobile titles remain key contributors, but mobile softness and non-cash charges could pressure results, with NBA 2K27 already released and rising GTA VI anticipation positioning Take-Two for its reiterated fiscal 2027 net bookings target of $8.0 to $8.2 billion. Wedbush has projected fiscal 2027 net bookings above management’s existing guidance, reflecting expectations of stronger GTA VI launch sales.
What the Market Is Watching
The quarter itself is a placeholder. The real event is the confirmation, the tone, and any update on pre-launch momentum. GTA VI is tracking toward extraordinary pre-order numbers two weeks before launch, with Sensor Tower estimating about 7.71 million digital pre-orders and roughly $751 million in pre-order revenue. The pricing mix is notable: Sensor Tower has estimated that about 89% of pre-orders are for the $99.99 Ultimate Edition, versus about 11% for the $79.99 Standard Edition.
Following the November 9 report, the primary catalyst is the November 19 launch, with a base price of $79.99. Analysts have projected roughly 37 million GTA VI units sold in the launch window, while more aggressive forecasts have pushed into the 40 million-plus range. According to a widely followed analyst survey, the average rating for TTWO stock is “Strong Buy,” with a 12-month price target of $286.21, about a 33% premium to the November 6 close.
Options Market: What the Premium Says
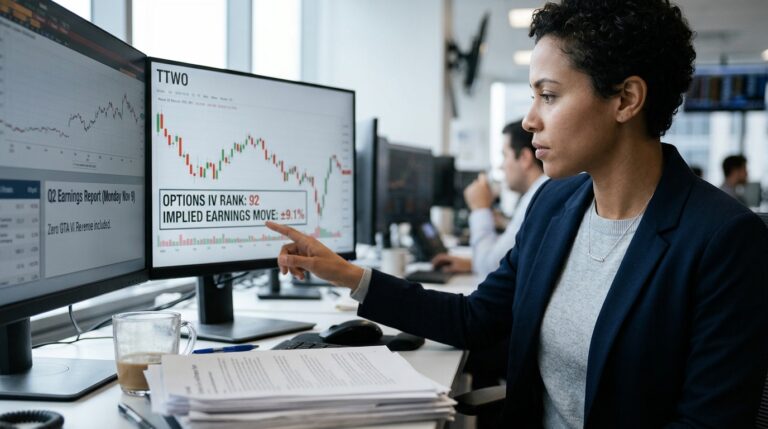
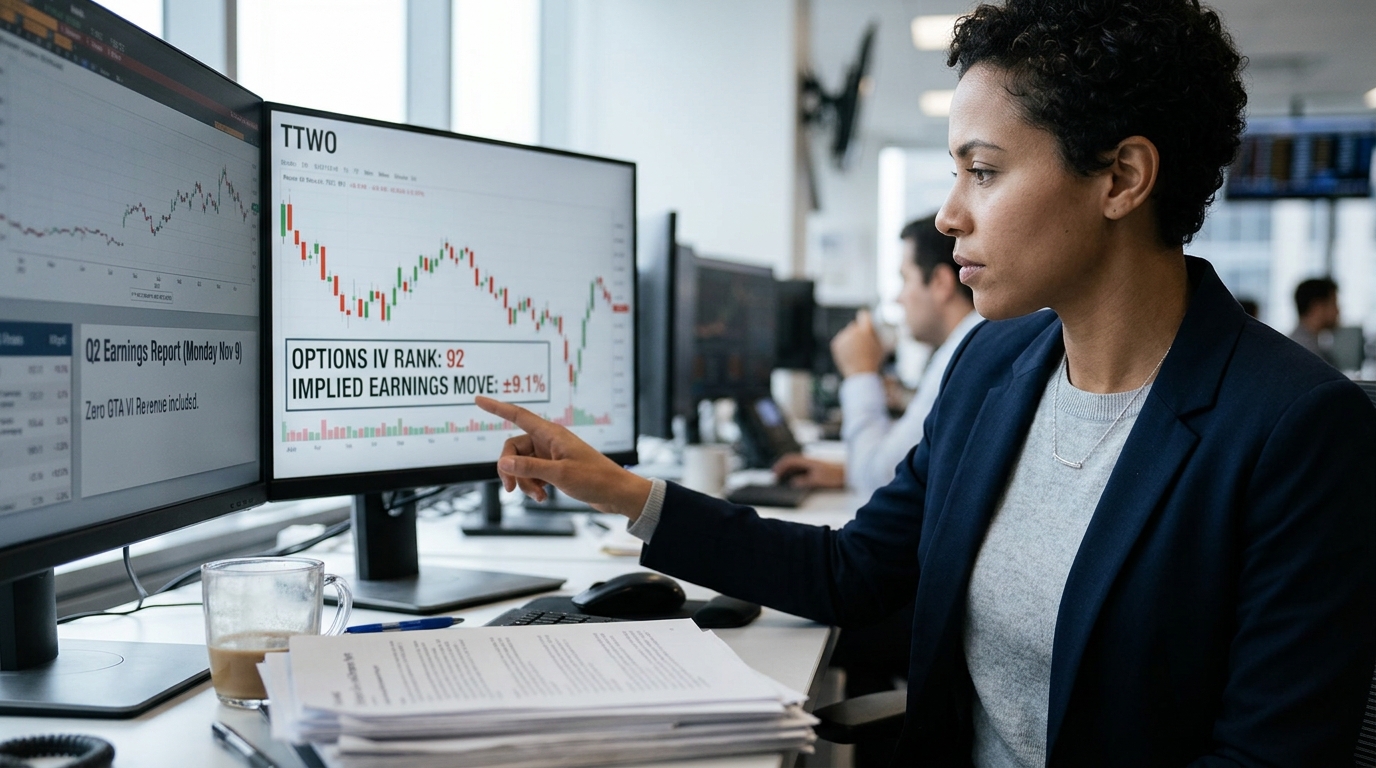
Options markets are pricing an implied move of about ±9.1% into the November 9 report, versus a 10-year average of ±8.6%, based on EarningsWatcher data. The last report produced a +6.5% move.
IV percentile stands at 98%, with IV rank at about 92. The November 13 expiration carries elevated at-the-money implied volatility, and the November 20 expiration remains elevated as well, reflecting the dual catalyst of the earnings call and the November 19 launch.
On the flow side, the picture leans cautious. Puts ran 15,059 contracts against 10,853 calls in one recent session, with a single Nov 20 $165 put block of 7,556 contracts against open interest of only 181, consistent with a new large position. Hedging demand is elevated, but the skew shows no panic. The stock’s 52-week range extends from $183.86 to $265.94, and TTWO traded around $216 on Friday, sitting roughly 19% below its 52-week high.
Structured Trade Framework
Bull case. If you believe management reaffirms the $8.0 to $8.2 billion net bookings guide with constructive commentary on pre-order momentum, a defined-risk structure would be a November 20 or December bull call spread, buying the 220 call and selling the 240 call. Maximum loss is the net debit. IV crush post-earnings will work against long premium, so the spread structure limits that drag.
Bear case. For traders expecting a “sell the news” reaction, particularly if Zelnick hedges his language on launch-week bookings recognition or mobile weakness widens, a put spread expiring November 20 (buying 205, selling 190) captures downside with defined risk. The Nov 20 $165 put activity in the flow data suggests at least one large participant is already positioned for a tail scenario.
Neutral case. With IV rank near 92 and the implied move above historical average, premium sellers have a structural edge if the stock stays inside the ±9% envelope. An iron condor straddling the 190/205 put spread and 230/245 call spread on the November 20 expiration collects elevated premium and profits from IV crush if the actual move disappoints the options market’s expectations. This is not a low-risk posture; a gap beyond either wing produces a full loss on that side.
Risk Factors
The obvious risk is a binary one: GTA VI delays appear unlikely given management’s repeated reaffirmations, but a miss on guidance, weak mobile data, or any softening in launch commentary could accelerate the stock’s slide toward its 52-week low. Conversely, any upside surprise on the guide or pre-order quantification could force a squeeze toward $240 before the launch even begins. Post-earnings IV crush is aggressive at these levels, and any long-only options position carries substantial decay risk over the November 19 launch window.
Action Checklist
- Monitor the November 9 earnings call at 4:30 PM ET for guidance reaffirmation on the $8.0 to $8.2 billion net bookings range
- Watch for any quantification of pre-order volumes from management (none has been officially disclosed to date)
- Assess IV levels immediately after the report: a drop from the mid-60% range toward 40% on the November 13 chain signals normal crush, not a directional move
- Track the November 20 $165 put open interest for any further additions as a real-time sentiment gauge
- Confirm position sizing relative to the ±9.1% implied move before initiating any directional structure