November 5, 2026
Bonus Content: Cloudflare Reports Tonight After Datadog’s Selloff
For a while now, I’ve been showing regular traders like you how to take advantage of a specific 60-minute window…
One that lets us go after 50% returns every morning – whether the market opens higher… or lower.
Here’s what I mean…
If you had spotted this 60-minute opportunity yesterday morning… all you would’ve had to do was place a quick trade before 10 am…
Went ahead with your morning plans and when you return a couple of minutes later, there’s a good chance you’d find $500 in extra income sitting in your account (on a 1k stake)
It wouldn’t have mattered what happened with the overall market… this 60-minute window would have been all you needed to target cash.
Today? Same story.
Place a quick trade, grab your coffee… and let the setup do the heavy lifting.
And just 60 minutes later… come back to what could be a nice $500 in extra income sitting in the brokerage account.
I designed the setup to be that straightforward.
Granted, there will be trades that won’t work out
But if you want in?
Cloudflare Reports Tonight After Datadog’s Selloff
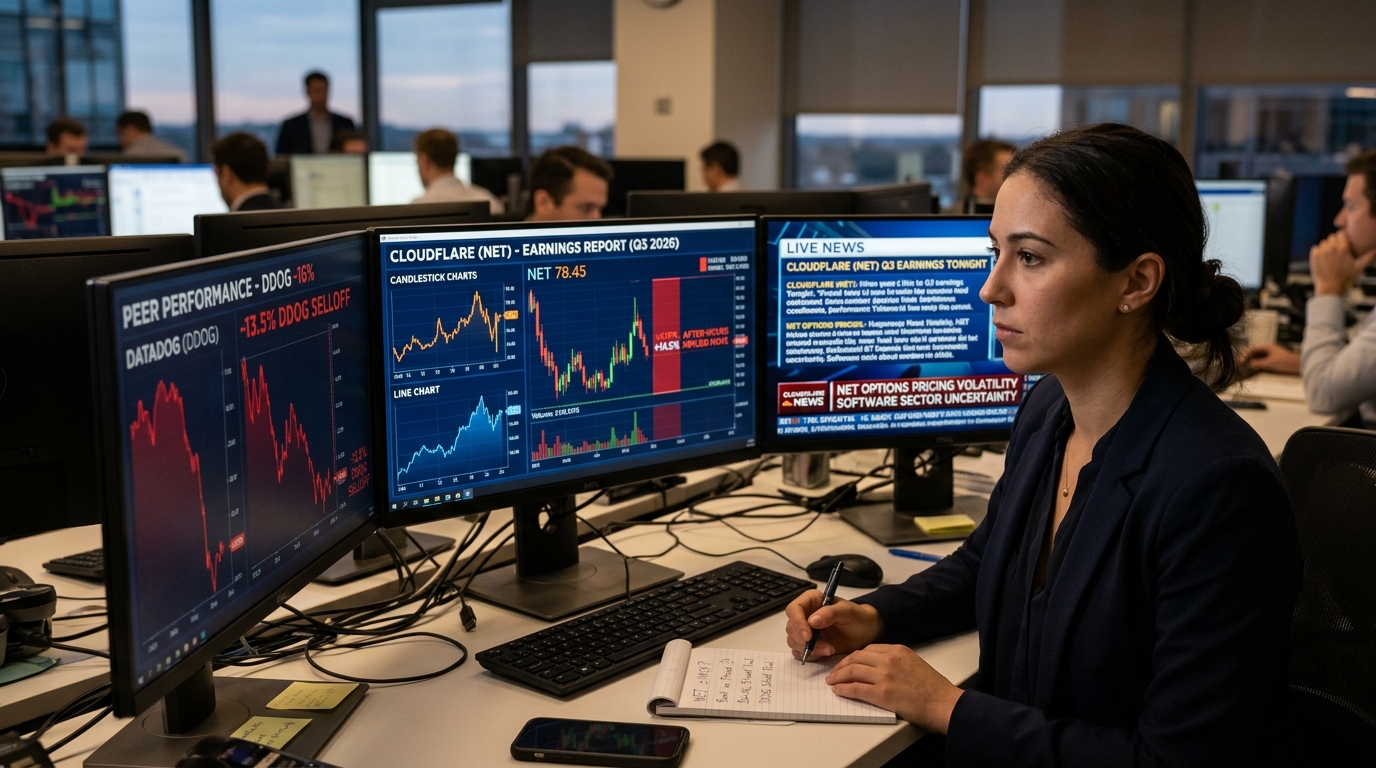
Markets don’t reward beats. They reward beats relative to what was already priced in. That distinction matters more tonight than it has for any infrastructure software event in months.
Cloudflare (NET) reports Q3 2026 results after the close today, with the 5:00 p.m. ET call following immediately. The setup is complicated by two data points that landed in the last 48 hours: Datadog (DDOG) fell roughly 13-16% Wednesday despite reporting Q3 revenue of $1.20 billion, up 35% year over year, with EPS of $0.81 beating the $0.64 consensus by $0.17. Dynatrace (DT) dropped more than 13% the same session after beating its own fiscal Q2 estimates on both revenue and earnings, then cutting full-year non-GAAP net income per diluted share guidance to $1.88-$1.90, primarily due to dilution from a convertible bond transaction, with the Arize acquisition also impacting the outlook. The pattern is clear: software beats are being sold when guidance fails to accelerate the story.
The Numbers Cloudflare Must Clear
Cloudflare guided Q3 revenue to $736-$737 million when it reported Q2 in August, representing roughly 31% year-over-year growth. The street has since centered on essentially the same bar: consensus sits at approximately $736.80 million in revenue and about $0.3426 in EPS, against prior-year figures of $562.03 million and $0.27, implying 31.1% revenue growth and about 26.9% EPS growth year over year. Q2 delivered $696.1 million in revenue, up 36%, with current RPO also growing 35%. Non-GAAP EPS of $0.29 beat by roughly two cents.
The full-year guide of $2.864-$2.870 billion has not been revised since August. Any raise there will carry more weight than the Q3 beat itself. Watch also for net dollar retention, which management has previously anchored near 120%, and large customer count after Q2’s record additions.
Why the Reaction Could Look Nothing Like the Results
This is not about whether Cloudflare grows 31%. It is about whether the guide implies 33% or 34% for Q4 and whether full-year guidance gets raised meaningfully above the $2.870 billion ceiling. Datadog’s problem was sequential flatness: Q4 revenue guidance of $1.19-$1.20 billion implied essentially no growth from Q3’s $1.20 billion level, and the stock lost more than a tenth of its value despite beating consensus. Dynatrace’s problem was a profit guide-down driven largely by increased diluted share count, not a revenue miss. In both cases, the actual quarter was not the issue.
Cloudflare carries a price-to-sales ratio near 37 times. NET has fallen roughly 22% over the last month going into tonight’s report, which provides some air cover, but the stock traded above $300 as recently as early August. At current levels near $265-$273, a 14.9% implied move puts the upside scenario near $306 and the downside scenario near $226.
Sector Read-Through
The DDOG and DT outcomes compress the tolerance for guidance ambiguity across the entire infrastructure software peer group, including Fastly (FSLY) and Akamai (AKAM). Any sequential softening in Cloudflare’s consumption-based revenue lines, or guidance that merely matches the current full-year consensus, risks similar price action regardless of Q3 results. The market is currently paying a premium for visible acceleration, not steady growth.
Options Market Analysis
Going into tonight’s call, NET’s implied volatility stands near 73-75% with an IV rank around 70-88 on most measures, elevated relative to NET’s own trailing year. The expected move priced by the options market is approximately ±14.9% for the November 5 expiration. Historically, NET’s actual earnings move has exceeded the options-implied move in 11 of its last 17 reports, a 65% hit rate. That asymmetry matters for straddle buyers and spread sellers alike. The put-call volume ratio reached approximately 1.67 in recent sessions, suggesting hedging pressure. Open interest is concentrated at the $242 put strike on the downside.
Structured Trade Framework
Bull case: For traders expecting a beat combined with a full-year revenue raise above $2.875 billion and Q4 guidance implying reacceleration toward 34%+ growth, a defined-risk long call spread targeting the $295-$315 range captures upside while limiting premium exposure to IV crush post-report.
Bear case: If you believe Cloudflare guides Q4 conservatively, as it has signaled given consumption-based contracts that are harder to forecast, a put spread structure long the $242 put and short a lower strike near $220 targets the downside concentration in open interest while capping loss to the net debit paid.
Neutral/defined-risk: Given that actual moves have exceeded the implied move 65% of the time historically, naked short straddles carry meaningful gap risk. An iron condor spanning roughly $230-$245 on the downside and $300-$315 on the upside captures the implied move range while defining maximum loss. Expect significant IV crush after the call regardless of direction.
Key Risks
The primary risk on the long side is a beat paired with cautious consumption guidance, the exact template that hit DDOG Wednesday. The primary risk on the short side is a genuine guide-up: Cloudflare’s full-year guidance has historically been conservative, and management said in Q2 that AI-driven non-human traffic exceeded 50% of its network for the first time. A consumption acceleration from AI agents would justify revised numbers and compress downside sharply.
Forward Outlook
Whatever the Q3 result, the Q4 implied growth rate and any update to the $2.864-$2.870 billion full-year revenue range will define where NET trades Friday morning. The DDOG precedent confirms that 35% growth is not sufficient if the forward growth rate decelerates. Cloudflare needs to show that 31% is a floor, not a ceiling.
Action Checklist
- Confirm Q3 revenue vs. the $736.80 million consensus and direction of full-year guidance vs. current $2.864-$2.870 billion range
- Track Q4 revenue guidance implied growth rate; below 30% year over year increases selloff probability
- Monitor net dollar retention rate vs. 120% benchmark and large customer additions
- Size positions against the ±14.9% expected move; avoid undefined-risk short volatility given the 65% historical beat rate on actual move vs. implied move
- Watch for AI consumption data points from management; acceleration there is the bull case catalyst DDOG lacked