The CIA Accidentally Discovered the Rare Earth MOTHERLODE
…And One $5 Stock Sits at the Center of it ALL
Dear Reader,
Inside the CIA’s private museum at Langley sits a strange black rock, sealed in a block of clear plastic.
It looks like a lump of coal… but it’s NOT.
It’s a tiny piece of the biggest discovery of critical resources ever made… a $16 trillion treasure trove that 60 Minutes calls “staggering.”
And one small company you can buy today for about $5 holds the rights to harvest the richest stretch.
Click here for the jaw-dropping TRUE story.
As you’ll see…
The CIA stumbled onto it during one of the boldest secret missions of the Cold War.
To hide what they were really doing, they teamed up with billionaire Howard Hughes and invented a fake mining company.
The whole world bought the story.
But when the mission was over, the CIA came back with something nobody expected… rocks as heavy as gold bricks, packed with rare earths, cobalt, nickel and lithium.
These are the same materials that are driving the 21st-century economy.
America can’t build a fighter jet, an electric car or an AI data center without them.
A $16 Trillion Chess Move that practically nobody sees coming…
At the center of it all is the only company with the technology and track record to harvest this rare earth motherlode.
A publicly traded stock you can buy right now for $5.
The last time Trump backed a mining company like this, its stock shot up 407% in a single week. This time, I believe this stock could hit $50 by the time Trump’s second term is over.
Click here for the details before Trump makes his move.
Regards,
Matt McCall, Head Innovations Strategist
Monument Traders Alliance
P.S. A former CIA insider just sent me Trump’s executive order by OVERNIGHT FedEx, with one section highlighted in yellow. Click here to see why it could be the key to 1,000% gains before Trump leaves the White House.
Zeta Global Reports Tonight. The 2027 Guide May Matter More Than the Q3 Beat.
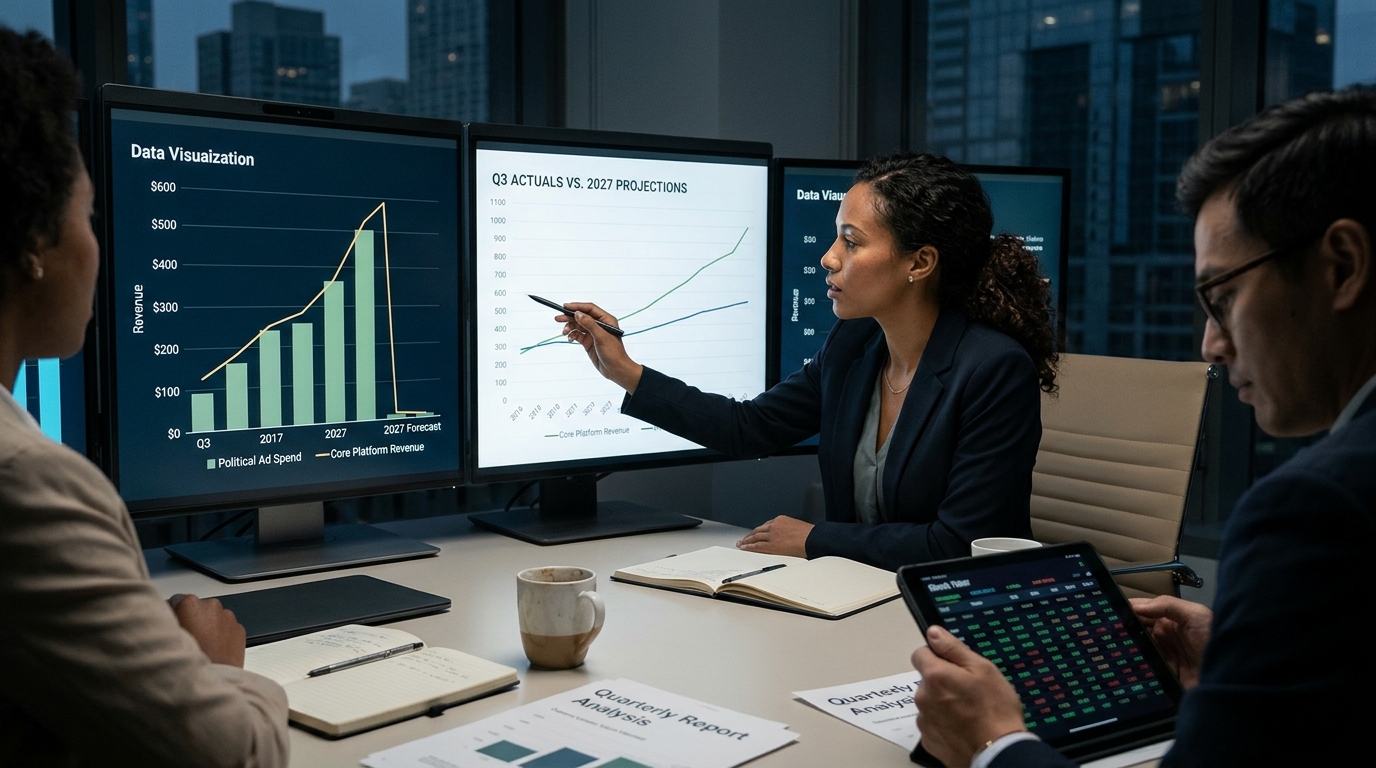
Zeta Global walks into tonight’s Q3 report with 20 consecutive beat-and-raise quarters behind it and the most expensive midterm political ad cycle ever banked into the numbers. That combination makes the EPS reading almost secondary. The question the market will price within minutes of the call ending is simpler and harder: what does 2027 look like when political revenue goes to zero?
The stock entered the session near $31.74, up roughly 56% year to date, but pulling back about 9% over the prior week. Options traders are pricing a ±15.4% move on the report, against the stock’s historical average earnings swing of ±14.4%. The range that implies is roughly $26.80 on the downside and $36.70 to the upside. The 52-week range runs $14.36 to $35.75, which puts the upper bound of the implied move just above the annual high.
The Numbers in Front of Management
Consensus for Q3 stands at $0.28 non-GAAP EPS on revenue of approximately $470 million, representing year-over-year growth of roughly 40%. That revenue figure matches the Q3 guidance midpoint Zeta issued in August. Management raised Q3 revenue guidance to a range of $469 million to $472 million, up $10 million at the midpoint, and adjusted EBITDA guidance to $115.0 million to $116.0 million. Full-year 2026 revenue guidance was lifted by $33 million to $1,818 million at the midpoint, reflecting year-over-year growth of 39%.
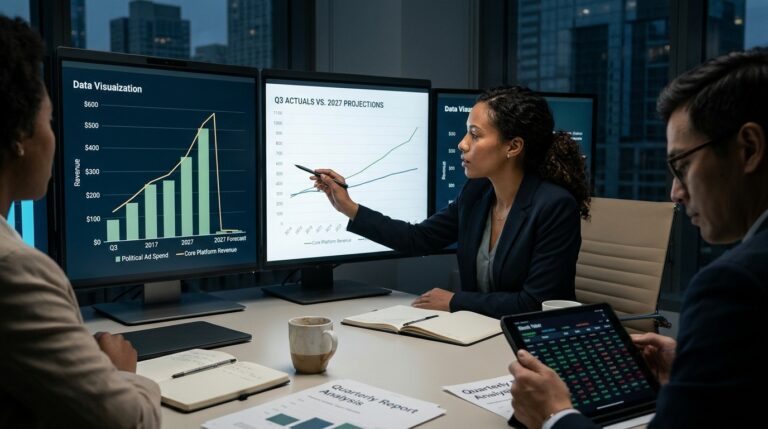
The political revenue tailwind for this quarter is real. The 2026 midterm cycle is projected to be a record political ad cycle, with about $11.6 billion in total political advertising spend, according to AdImpact’s June projection as reported by Reuters. Zeta’s AI-driven data platform sits at the intersection of both programmatic channels. Super-scaled customer count reached 197, up 17% year over year, with super-scaled customer ARPU growing to $1.8 million, also up 17%.
Why a Beat May Not Be Enough
Twenty consecutive quarters of above-guidance delivery has compressed the surprise premium. The market has already absorbed the pattern. What it has not priced is the guidance gap. Zeta will offer its first formal look at 2027 on tonight’s call, and that year carries no presidential or midterm cycle revenue. Management has previously said guidance is not built on political advertising, and the $33 million lift to full-year revenue guidance referenced in its 2Q’26 release was framed as core-business driven. But 2027 is different: political dollars don’t just shrink, they reset. Q3 2026 revenue guidance of $471 million at the midpoint represented roughly 40% growth, but materially lower growth when excluding acquisitions and political candidate revenue. That organic rate is the number 2027 will actually be measured against.
The adtech group has been re-rated hard this year as investors separate cyclical from structural growth. Omnicom’s most recent results underscored how much political dollars inflated 2026 industry revenue. Analysts note that valuation ultimately depends on whether Athena and recent acquisitions produce durable revenue and margin gains. That question becomes acute the moment the political cycle stops subsidizing the top line.
Options Market Analysis
Implied volatility sits at 67.17% against historical volatility of 64.69%. IV Rank is 40.09% and IV Percentile is 38%. Both readings place current options pricing in the lower half of the past year’s range. The IV high over the past year hit 96.62% on August 4, the Q2 earnings date. That compression matters: premium sellers are not being richly compensated for binary event risk relative to recent history, and premium buyers are not paying an elevated entry cost.
The consensus earnings estimate is $0.28 per share, and the stock has had a post-earnings announcement drift of +28.9% since its last earnings release on August 4. That realized move ran well outside the implied range at the time, a pattern that argues for defined-risk structures over naked premium sales ahead of this report.
Structured Trade Framework
Bull case: For traders expecting a revenue beat alongside a 2027 guide that holds organic growth above 20% with expanding EBITDA margins, a defined-risk call spread expiring in December captures the upside range without full binary exposure. A $33/$38 call spread leverages the consensus analyst price target of $37.06 as a natural ceiling.
Bear case: If you believe the 2027 guide disappoints or management signals material political revenue normalization without an organic offset, a December put spread in the $29/$25 range defines risk on the downside and targets the ±15.4% implied move floor. The adtech group’s pattern of selling the guide rather than the beat is well documented.
Neutral case: With IV Rank below 50, an iron condor is not richly priced here. A defined-risk structure at the $27/$30 put spread and $35/$38 call spread captures the straddle’s implied range, but the stock’s history of outside moves on earnings reduces the probability of full profit capture at expiration.
Risk Analysis
The primary risk on the long side is a 2027 guide that strips out political revenue without replacing it with equivalent organic growth visibility. On the short side, Zeta highlighted in its 2Q’26 materials that it had delivered 20 consecutive beat-and-raise quarters, and a quarter containing peak weeks of a record political ad cycle is a structurally poor candidate for a first miss. Goldman Sachs upgraded ZETA to Buy and raised its price target to $45 on October 16, adding institutional sponsorship entering the report. Short interest sits at 7.17%, which introduces squeeze potential if the guide is stronger than feared.
Forward Outlook
Earnings for Zeta Global are expected to grow 119% in the coming year, from $0.21 to $0.46 per share. The core tension tonight is not whether Q3 was strong. Given the political ad cycle, it almost certainly was. The tension is whether management’s 2027 framework gives the market a reason to hold a stock that has already returned 56% in 2026 as it enters a year where the tailwind reverses and analysts begin the work of separating durable enterprise AI revenue from campaign-cycle economics.
Action Checklist
- Q3 revenue vs. ~$471M consensus; Q3 adjusted EBITDA vs. $115.5M midpoint
- Super-scaled customer count vs. 197 Q2 baseline; ARPU trajectory
- 2027 initial revenue guide: isolate organic growth rate excluding M&A and political revenue
- Management commentary on Athena AI platform monetization as the post-political growth driver
- Implied move: ±15.4% sets the straddle range at approximately $26.80 to $36.70
- Post-report IV behavior: rapid IV collapse favors defined-risk structures over naked positions