From the man who tabbed NVIDIA before it soared 6,271%
over 7 years at its peak
Wall Street’s Hottest Stock Has a Waiting List. Here’s How to Skip It.
Wealthy investors are lining up for Anthropic shares and coming up empty. Tech Visionary, Matt McCall, says you can get into a backdoor opportunity today for less than $100 a share.
Anthropic, the company behind Claude, is set to go public at a record $2 trillion valuation.
It could top SpaceX as the biggest IPO in history.
And right now, almost nobody can buy a single share.
One Wall Street broker, whose firm trades about 1,000 private stocks, told TechCrunch:
“The hardest stock to source in our marketplace is Anthropic. There’s just no sellers.”
Even Goldman Sachs is charging clients 15% to 20% of their profits just for a way in.
The Line Is Out the Door
Meanwhile, people who already own a piece of Anthropic are holding on tight.
While everyone else is stuck in line. Even wealthy investors are struggling to get shares.
And it’s all leading to the most anticipated IPO in history.
When Anthropic finally goes public, millions of regular folks will rush to buy whatever they can get.
But tech legend Matt McCall isn’t getting in line.
“Most people are going to wait for Anthropic to go public and then buy as many shares as possible,” he says. “But I think that’s a huge mistake.”
Who Is Matt McCall?
There is a short list of analysts in America who were early on the AI boom.
Matt McCall is one of them.
He’s the Head Innovation Strategist at Monument Traders Alliance and editor of The McCall Innovation Report.
Over the past two decades, McCall has written about 50 stocks that went on to peak gains of 1,000% or more. Including:
- Tesla, before it climbed as high as 3,129%
- NVIDIA, before it soared a peak 6,271% in 7 years
- AMD, which he singled out in 2009
That’s why people call him “Mr. 1,000%.”
On March 6, 2009, McCall went on FOX Business and gave away nine stocks. One was AMD, trading around two dollars. By 2026 it rose 25,000%, enough to turn a $5,000 stake into more than $1.28 million.
No Waiting List Required
McCall’s play isn’t Anthropic. It’s a stock linked to Anthropic that you can buy right now in a regular brokerage account.
No waiting list. No special broker. No fighting Wall Street for scraps.
He calls it a “Second IPO.”
It may sound too good to be true. But it has happened before.
When Rivian went public in 2021, Ford owned a 12% stake. In the six months around Rivian’s IPO, Ford shares roughly doubled.
Yahoo quietly built a huge stake in Alibaba. In the two years around Alibaba’s IPO, Yahoo shares could have tripled your money.
It happened again shortly after EchoStar acquired $8.5 billion in SpaceX shares. In the months leading up to the SpaceX IPO, its shares soared 600%.
Now it’s happening again!
Anthropic’s “Silent Partner”
Years before the IPO frenzy, a much smaller firm took a $100 million stake in Anthropic. It beat Apple, NVIDIA, Amazon and Google to the punch.
Today, the entire company is valued at less than $15 billion. That’s 100x smaller than Anthropic.
McCall believes its early stake could cause it to double or triple in the years ahead.
And you can buy it for less than $100 a share.
We sat McCall down in front of our cameras to get the whole story. He even gave away the name and ticker.
For the time being, you can watch it free.
|
“If history repeats… investors could double or triple their money in the years ahead.” – Matt McCall
Skydance Beat EPS by 150% and Dropped 7.6% Next Day
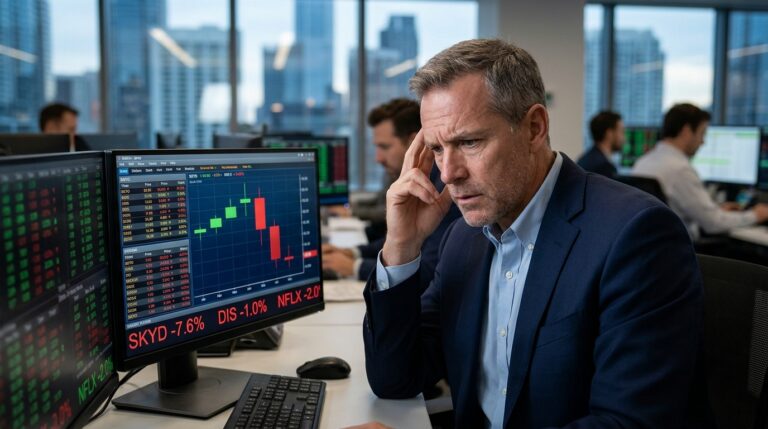
Markets don’t need a miss to sell a stock. They only need a reason to doubt the future. Skydance (SKYD) delivered exactly that on November 9, reporting a quarter that crushed estimates by any conventional measure, then watching its shares fall about 7.6% the following session. The stock closed November 10 at $8.06. Netflix slipped 2%. Disney fell 1%. This selloff was not about the sector. It was entirely about Skydance.
The disconnect between the earnings number and the price reaction is where the real analysis lives.
What the Numbers Said
Skydance reported Q3 2026 adjusted earnings of $0.45 per share on November 9, 2026, beating the $0.18 consensus estimate. That is a 150% beat. Revenue of $7.03 billion came in slightly below estimates. Adjusted EBITDA was $1.0 billion, a 14% margin on revenue that grew 5% year-over-year. Paramount+ revenue grew 21%, its fastest quarterly growth this year, with ARPU up approximately 14%. On its own, that is a strong quarter.
The problem arrived in the Q4 guidance. Management warned that film-slate performance and transition costs would weigh on near-term results and cash flow as the Warner Bros. Discovery integration ramps, with one-time cash costs to achieve synergies expected to total roughly $4 billion over the transformation, with 60% to 70% of that impacting 2027 and 2028.
Why the Reaction Happened
The company has roughly $87 billion in gross debt and about $10 billion of cash. Against that backdrop, any early-quarter hole in EBITDA is not a small data point. It frames execution risk precisely when investors need to see execution certainty.
Bernstein analyst Laurent Yoon described the quarter as “more of a prologue than Chapter 1 of Skydance’s journey following the WBD acquisition.” TD Cowen’s Doug Creutz remains skeptical that management will be able to create value from the merger when “so many other major media deals have failed,” citing the “high” integration and leverage risks. Citizens JMP lowered its price target from $14.00 to $13.00, while keeping a Market Outperform rating.
How the Options Market Mispriced the Earnings
The November 13 weekly $8 straddle was priced for a move of 13% into the earnings release, with a call/put ratio of 1 call to 1.3 puts. That implied move looks right in direction but entirely wrong in mechanics. The straddle priced for a binary outcome, a large move on the number itself. What actually drove the decline was forward guidance and the balance sheet, which options pricing rarely models with precision. Traders positioned for volatility around the EPS number; the EPS number was irrelevant. The integration timeline and the debt stack did the work.
Pre-event implied volatility in SKYD was running above 50% across near-dated contracts, consistent with the name’s history of large single-day moves. At that level, premium sellers who faded the event had a narrow window to exit profitably before the November 10 open, and those who held overnight into the gap were caught wrong-sided on a catalyst the straddle did not fully capture.
Sector Read-Through
The muted moves in Netflix and Disney confirm this was idiosyncratic. SKYD’s selloff was not a signal about streaming economics broadly; it was a signal about leverage, integration timelines, and film-slate execution in year one of a highly complex merger. BofA Global Research kept an Underperform rating and a $9 price objective, warning of a long integration. Bernstein has an Underperform rating with a $6 price target.
Options Market Framework
With SKYD trading near $8.06 and the nearest analyst floor at $6, the risk/reward map is asymmetric. Implied volatility in the December chain is elevated post-event, historically offering a window for defined-risk structures rather than directional speculation.
- Bull case: If you believe management can deliver on its at least $6 billion run-rate synergy commitment and the near-term headwinds prove isolated, a defined-risk structure such as a bull call spread in the January 2027 expiry, buying the $8 strike and selling the $12 strike, frames upside toward the Citizens JMP $13 price objective with capped downside. Management has guided to achieving at least $6 billion of run-rate synergies within three years.
- Bear case: For traders expecting leverage and integration costs to compound, a defined-risk bear put spread below $7.75 (November 10’s intraday low) expresses the structural concern without unlimited downside. Integration risks include roughly $4 billion in cash costs to achieve synergies, with 60% to 70% incurred in 2027 and 2028.
- Neutral case: With elevated IV post-earnings, a short strangle between $7 and $10 collects premium against a range-bound outcome as the market waits for full 2027 guidance, which management indicated will come at the Q4 call. For 2027, the company expects continued strong D2C revenue growth, studio revenue growth, higher total company adjusted EBITDA, and cash flow breakeven or better including cost-to-achieve synergies.
Risk Analysis
Gross debt near $87 billion against approximately $10 billion of cash, with a net leverage target of 3.0x by end of 2029, means this is a long runway with limited margin for operational error. The company plans to launch a bundle of Paramount+ and HBO Max in early 2027 as the first visible integration milestone. If that bundle underperforms or launches late, the multiple compression story accelerates. Dune: Part Three arrives December 18, 2026 and represents the next data point on content execution.
Forward Outlook and Action Checklist
The gap between a 150% EPS beat and a sharp next-day loss is not a paradox. It is a capital structure story wearing an earnings mask. The earnings rewarded the near-term; the guidance punished the long-term. Until leverage direction is confirmed through 2027 guidance and the HBO Max-Paramount+ bundle is live, SKYD will likely trade as a show-me situation.
- Monitor Q4 studio performance when announced; what pressures EBITDA is likely to have a name, and tracking it matters
- Watch the December 18, 2026 Dune: Part Three opening weekend as a leading signal on combined studio execution
- Track IV levels into the Q4 earnings call; elevated volatility into early 2027 guidance could reset the options framework entirely
- Any defined-risk structures should account for the $7.40 and $7.27 technical support levels before sizing
- Citizens JMP’s $13 target implies roughly 61% upside from current levels; the spread between that and BofA’s $9 objective frames a wide range of analyst conviction