September 16, 2026
The note drop is an options story first
The business is fine. The stock fell 10% anyway. That is the convertible note market doing exactly what it is designed to do, and understanding the mechanics matters more right now than relitigating whether Axon’s growth deserves a premium multiple.
Your Free Options Book Is About to Vanish
In case you missed it… make sure you get your free “Simple Options Trading For Beginners” book before your link expires.
I eventually plan to charge money for this training, so do yourself a favor and download it now…
That way, no matter what it costs in the future, you’ll have a free copy.
Sound good?
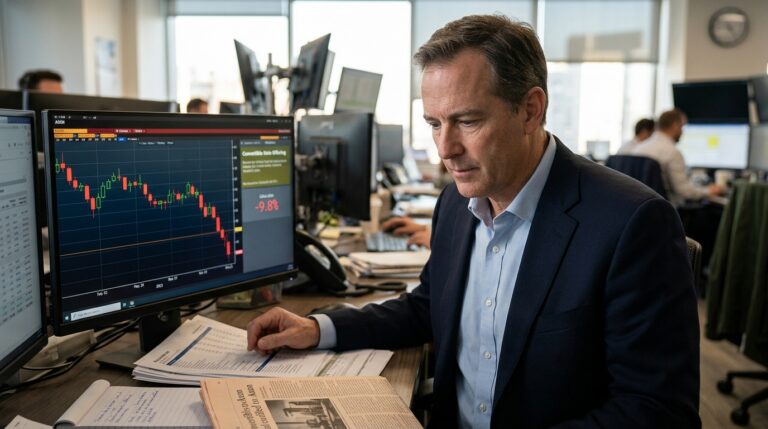
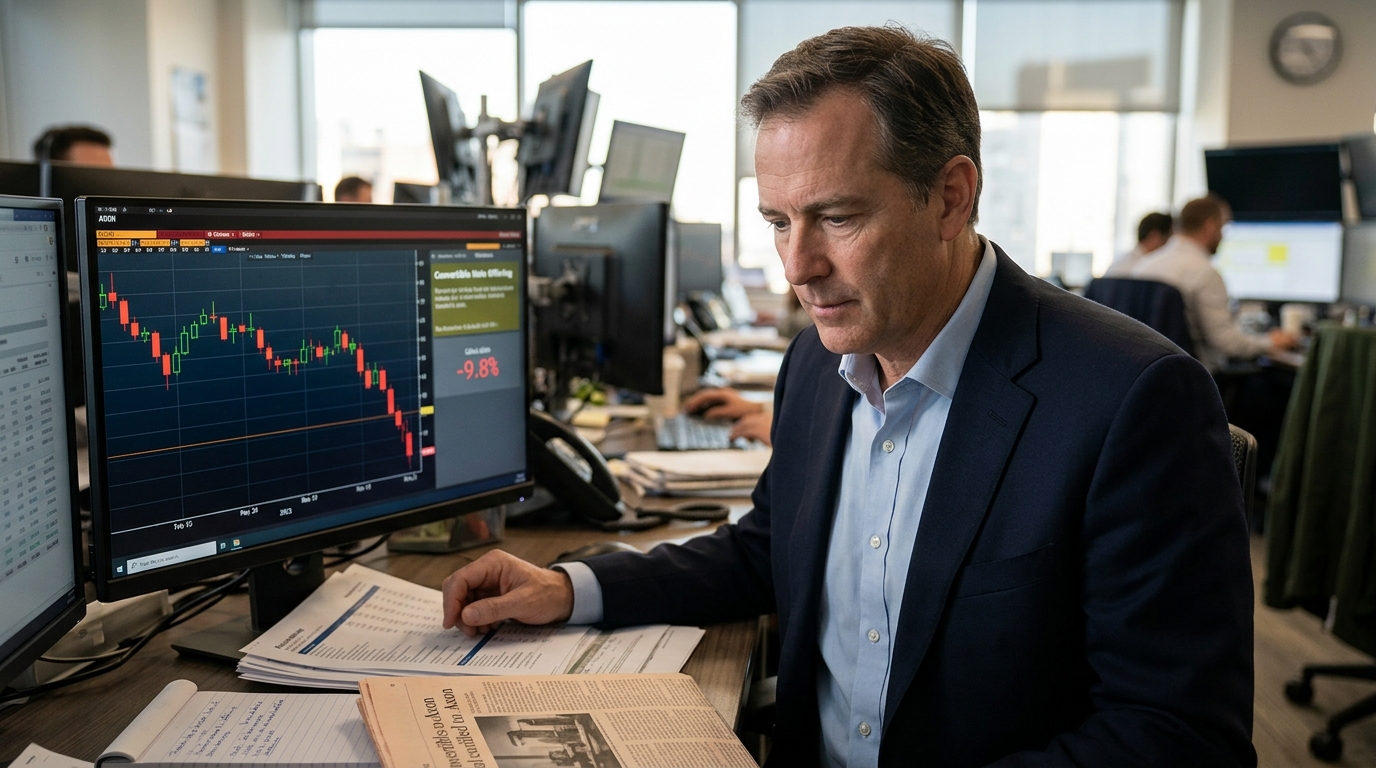
At the close on September 15, Axon Enterprise fell 9.8% to $442.08 on Nasdaq after announcing a $1.0 billion offering of 0% convertible senior notes. The move left shares well below recent levels and came on unusually strong trading volume versus recent sessions. For context on what was lost: prior to the drop, Axon’s market capitalization was roughly $39 billion based on recent closes. The offering-day selloff wiped out roughly $3.8 billion of equity value in a single session.
The Capital Structure Move
Axon said on September 15 that it intends to offer $1.0 billion of convertible senior notes carrying a 0% coupon, due 2031, in a public offering registered with U.S. regulators. Axon also granted underwriters an option to purchase up to an additional $150 million in notes to cover over-allotments, bringing the potential total offering to $1.15 billion. The notes carry no regular interest and no accretion of principal.
As of June 30, Axon reported about $673 million in cash, cash equivalents and short-term investments. It also disclosed about $1.75 billion of senior notes outstanding, leaving the company with a net debt position a little over $1.0 billion at that time. Adding up to $1.15 billion in new equity-linked paper deepens that debt load, even at 0% coupon. The company trades at a P/E ratio around 200, a premium growth valuation that offers minimal margin for disappointment.
The underlying business remains strong. Future contracted bookings grew 41% year over year to $15.1 billion, with Axon expecting to fulfill 20% to 25% of that balance over the next 12 months and the remainder over the following ten years. Full-year 2026 revenue growth guidance stands at 32% to 34%, raised from a prior range of 30% to 32%. Q2 revenue came in at $904 million, up 35% year over year. None of that changed Tuesday.
Inside the Nuclear Revival Reshaping Energy Markets
Governments worldwide are investing billions to revive a proven energy source. Supply chains are tightening, demand is rising, and select companies stand to benefit. The Nuclear’s Second Act report explains what’s happening next.
What Actually Drove the Drop
This is not a story about Axon losing faith in its own business. It is an options market story by construction.
When a company sells convertible notes, the banks and investors involved often hedge the embedded equity exposure by shorting the underlying stock or using derivatives. That hedge flow can hit quickly on announcement, before discretionary investors have time to react. A $1 billion convertible on a stock that was trading in the high $400s implies meaningful hedging demand that can overwhelm near-term liquidity. The 9.8% drop reflects that mechanical pressure compounding with sentiment.
Axon disclosed that option counterparties or their affiliates expect to enter into cash-settled over-the-counter derivative transactions with respect to Axon’s common stock concurrently with, or shortly after, the pricing of the notes, and may unwind those transactions and purchase shares in open market transactions following pricing. That unwind is a potential tailwind once dealers cover. Axon said it will spend approximately $99.9 million on capped call transactions, with an initial cap price of $1,049.94, which is 137.5% above the September 15 closing price of $442.08.
Options Market Conditions
Implied volatility spiked sharply on the announcement. The key point is directionally simple: when a stock gaps down nearly 10% on a structural catalyst, near-term implied volatility typically rises, and the options market tends to price a wider 30-day expected move. Put/call flow also often skews bearish on the day of a sharp selloff. That is the regime where defined-risk premium-selling structures can look optically attractive, but the trade-off is that the underlying can stay unstable while hedges are still being built, adjusted, and unwound.
A Forgotten Energy Source Is Powering Back Up
While investors chase the next tech story, one long-ignored sector is quietly heating up. A mix of global policy, rising demand, and tightening supply could reignite this market before 2026. See what the latest research reveals.
Structured Trade Framework
Bull case: For traders expecting dealer unwind buying to support the stock toward $460 to $475, a defined-risk bull put spread below current spot, say the $410/$390 spread expiring in 30 to 45 days, collects elevated premium while keeping max loss contained. The short put benefits from IV contraction as the hedging pressure fades.
Bear case: If you believe the dilution concern and balance sheet expansion reset the multiple lower, a bear call spread above $480 with 30-day expiry captures premium at elevated IV without requiring a precise downside target. Wall Street coverage includes Buy ratings with targets that have run as high as $825, so the bear case bets against a well-resourced consensus.
Neutral case: Elevated IV can make a short iron condor structurally attractive. With the stock near $442 and IV rich, selling the $390/$370 put spread and the $490/$510 call spread in October captures premium from both sides while the dealer unwind plays out.
Risk Analysis
Option counterparties and their affiliates may engage in hedging activity, including purchasing or selling shares in secondary market transactions, which could increase or reduce the market price of Axon’s common stock during the life of the notes. That two-directional risk means volatility around $442 is not necessarily over. Additionally, beginning September 20, 2029, Axon gains the right to redeem notes for cash, provided the stock price reaches 130% of the conversion price for at least 20 trading sessions within any consecutive 30-day window. That embedded call creates a gamma overhang years out.
Action Checklist
- Confirm IV rank and 30-day IV level before entering any structure. Elevated premium favors short-volatility trades, not long premium.
- Size defined-risk spreads to a maximum of 2% to 3% of portfolio value given residual dealer hedging uncertainty.
- Monitor open interest shifts at the $440 and $460 strikes for evidence of dealer unwind buying.
- Watch the $442 close as a reference. Settlement on the notes is expected September 18, 2026, which is the nearest structural catalyst for hedging flow to shift.
- Re-evaluate IV rank after settlement closes. If IV collapses back toward the 28% to 35% range, the premium-selling edge disappears and long premium structures become more competitive.