October 5, 2026
Bonus Content: UK Banks Face a Tax Risk Shares Have Not Priced In
Patriots’ Most Trusted Gold Company
Since 2000, Gold Is Up 1,395%. The S&P Is Up 425%.
For U.S. savers age 55+ with $50,000 or more in an IRA, 401(k) or savings. Free of charge, no obligation to buy anything.
Same twenty-six years. Same two dot-com and 2008 collapses. Two very different lines on the chart.1,2 Most Americans have never seen them put side by side – and almost nobody was told they are allowed to hold the better-performing one inside a retirement account.
Two lines on the same chart
In December 1999 gold traded near $290 an ounce and the S&P 500 closed the year at 1,469. Since then gold has multiplied roughly fifteen times over. The S&P has multiplied about five.1,2
Be fair about the comparison: that S&P figure is the price index and does not include reinvested dividends, which would lift it meaningfully.2 Even allowing for that, the gap over a quarter century is not a rounding error.
The reason has less to do with gold than with the dollar. Over those same twenty-six years the money supply expanded, two crises were met with emergency printing, and the national debt crossed $40 trillion. Gold did not get more valuable so much as dollars got less so – and gold is the one asset that cannot be issued by anybody.
Right now gold sits below its January 2026 peak while the world’s central banks keep adding more than a thousand tons a year, and published bank targets still run from roughly $4,900 to $6,300.3,4 Those are opinions, not promises. But a quiet stretch is a better time to read up than a panic. Get the free 2026 Gold IRA Guide.
The free 2026 Gold IRA Guide walks through exactly how a rollover from an IRA, 401(k) or TSP works, which metals the IRS allows, how insured depository storage works, and the mistakes that cost retirees the most. It is free and it takes about thirty seconds to request.
Claim Your Free 2026 Gold IRA Guide →
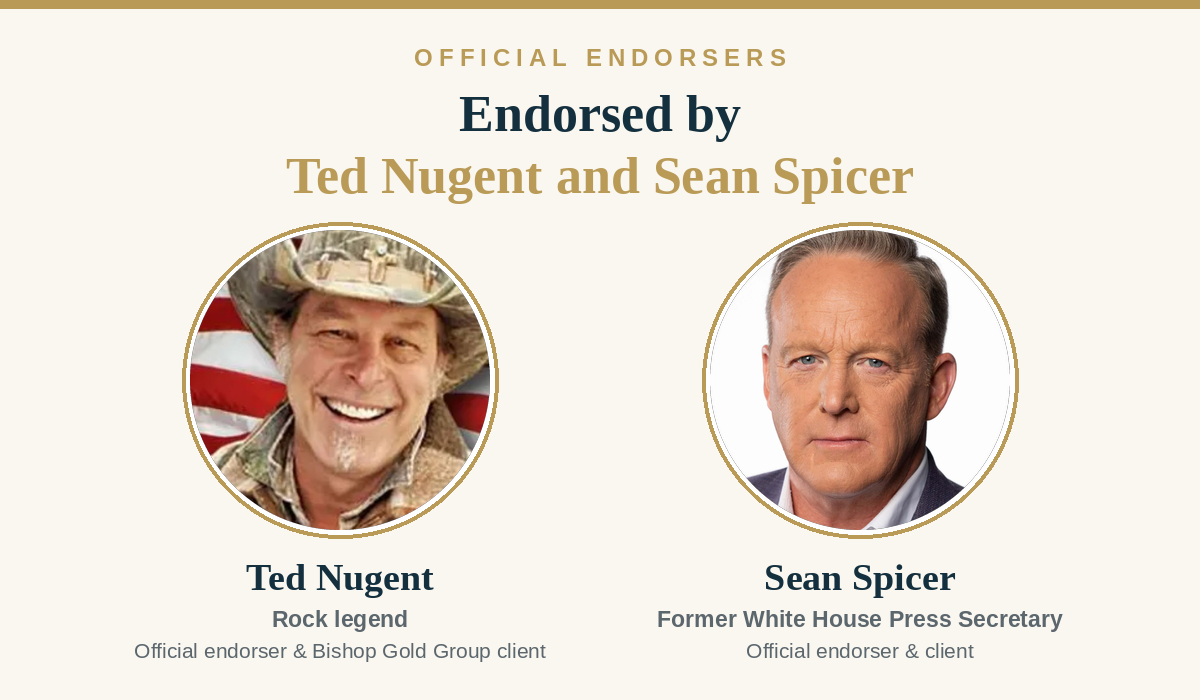
Rock legend Ted Nugent and former White House Press Secretary Sean Spicer are official endorsers and clients of Bishop Gold Group. 10 years in business ⢠5-star rated on Trustpilot and Google ⢠Mint Authorized Dealer
Prefer to speak to someone? U.S.–based specialists, no pressure, no jargon.
Mon-Fri ⢠7am-5pm PT
Sources
1 LBMA gold price, 31 December 1999 ($290.25/oz) to September 2026. Past performance is not a guarantee of future results.
2 S&P 500 price index, 1,469.25 close on 31 December 1999 to 7,707 in September 2026 – a price-only comparison that excludes reinvested dividends, which would raise the S&P figure materially.
3 Published year-end gold price forecasts as reported 2026: Goldman Sachs, J.P. Morgan, UBS and Bank of America, spanning roughly $4,900–$6,300/oz. Analyst forecasts are opinions, not guarantees.
4 World Gold Council, Gold Demand Trends, annual central bank net purchases 2022-2024.
Past performance is not a guarantee of future results. Precious metals are volatile and can decline in value. This comparison is historical and is not a prediction or a recommendation to buy or sell any asset.
UK Banks Face a Tax Risk Shares Have Not Priced In
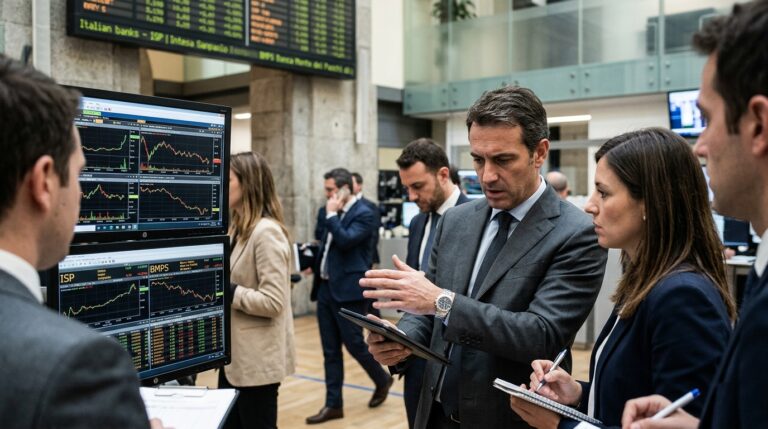
Markets do not need a law. They only need a credible threat. This morning, Bloomberg reported that City of London executives are actively concerned the October 28 Autumn Budget could include a windfall tax on UK domestic bank profits. No document exists. No Treasury source has confirmed a rate or a structure. That ambiguity is precisely the problem for anyone holding LLOY, NWG, or BARC outright.
The macro backdrop makes the rumour harder to dismiss than usual. UK 30-year gilt yields hit 6% on October 1, their highest level since 1998, while 10-year yields reached about 5.51%, the highest since 2007. Chancellor John Healey has said fiscal discipline will anchor the October 28 Budget, and the Guardian has reported he has refused to rule out increasing levies on bank profits. A sector generating conspicuous profits is a logical target when the fiscal arithmetic is under pressure.
The profit numbers give the political case real weight. Britain’s four largest lenders posted combined pre-tax profits of about £29.2bn for H1 2026. HSBC led the group with profit before tax of $19.5bn for the first half. Barclays posted £6.1bn, while Lloyds reported £4.3bn and NatWest reported operating profit before tax of about £4.3bn. Campaign group Positive Money has published estimates that a 38% levy on domestic profits, mirroring the Energy Profits Levy applied to oil and gas, could raise about £19bn from the big four alone. UK Finance has warned Chancellor Healey that further bank tax rises would damage Britain’s international competitiveness. Neither side is bluffing.
What the Market Has Priced, and What It Has Not
The most likely legislative mechanism, according to market commentary cited in UK press coverage of the debate, is a surcharge increase rather than a brand new tax: raising the existing banking surcharge from 3% to 5% would use established infrastructure and precedent. A harder route would be removing interest paid on reserves held at the Bank of England. Either path would compress net income.
Lloyds has already declined roughly 10% over the past month despite H1 statutory profit after tax rising 23% year-on-year to £3.1bn. Management reiterated full-year guidance targeting underlying net interest income greater than £14.9bn. The stock’s decline reflects budget anxiety, not a deteriorating business. Barclays has slid from the high-400s in July to around the mid- to high-400s in early October. NatWest has also pulled back from its 2026 high. The shares have already absorbed some fear. They have not absorbed a confirmed levy.
This is the gap options traders care about. Implied volatility on FTSE-listed banks is elevated relative to recent history but has not fully priced the binary event risk of an October 28 announcement. With about three to four weeks to expiry around the Budget date, traders are buying time as much as direction.
Options Market Structure
IV rank on LLOY and BARC is running elevated, consistent with pre-event positioning, but not at crisis-level readings. The put/call skew in November expiry favors puts, reflecting the asymmetry of a negative announcement: a tax confirmation is binary and sharp to the downside; a ruling-out produces a rally that has historically been contained. When the IPPR windfall tax proposal circulated in late August 2025, NatWest fell about 5%, Lloyds fell about 4%, and Barclays fell about 3% in a single session. A confirmed Budget measure would likely produce a larger, sustained move.
Structured Trade Framework
Bear case: For traders expecting a windfall levy to be confirmed on October 28, a defined-risk structure on LLOY using November expiry put spreads captures the downside without the unlimited loss exposure of a short equity position. A put spread below current levels, funded by selling a further out-of-the-money put, keeps maximum loss defined and aligns with a 5-10% drawdown scenario consistent with prior tax-scare reactions.
Bull case: If you believe Healey rules out a windfall levy, a short-duration call spread on NWG or BARC captures a relief bounce. The risk is asymmetry: relief rallies in this sector following tax rulings-out have historically been shallower and shorter-lived than the sell-offs.
Neutral / volatility case: A long strangle on LLOY capturing the October 28 event window treats the outcome as binary and direction-agnostic. The cost is the primary risk: elevated IV makes premium expensive, and a non-event Budget that neither confirms nor rules out a levy could leave the position worthless.
Risk Analysis
The UK sovereign rating calendars vary by agency, and investors may also be reacting to scheduled rating updates from other firms. Either way, a negative outlook change would pressure gilts further, tighten the fiscal environment, and raise the probability of a revenue-seeking Budget. The reverse is also true. Two macro catalysts in the same week amplify realized volatility regardless of direction.
Forward Outlook
The earnings calendar compounds the positioning challenge. Lloyds publishes its Q3 interim management statement on October 29, one day after the Budget. Traders who hold through both events face overlapping binary risks. A defined-risk structure is not optional here; it is the only rational frame.
Action Checklist
- Monitor pre-Budget Treasury signals and Bloomberg City sourcing for any surcharge language through October 27.
- Check IV rank daily on LLOY.L, BARC.L, NWG.L: if IV compresses ahead of October 28, premium becomes cheaper and risk/reward on long-volatility structures improves.
- Size positions to withstand a 10-15% single-session move in either direction.
- Treat October 28 and October 29 as a single combined event window: the Budget and Lloyds’ October 29 update land in consecutive sessions.
- Review any scheduled sovereign rating decisions this Friday for additional macro framing before committing to directional trades.