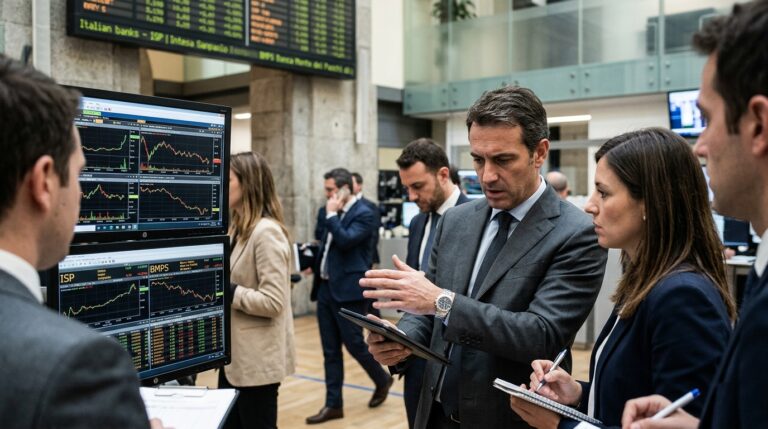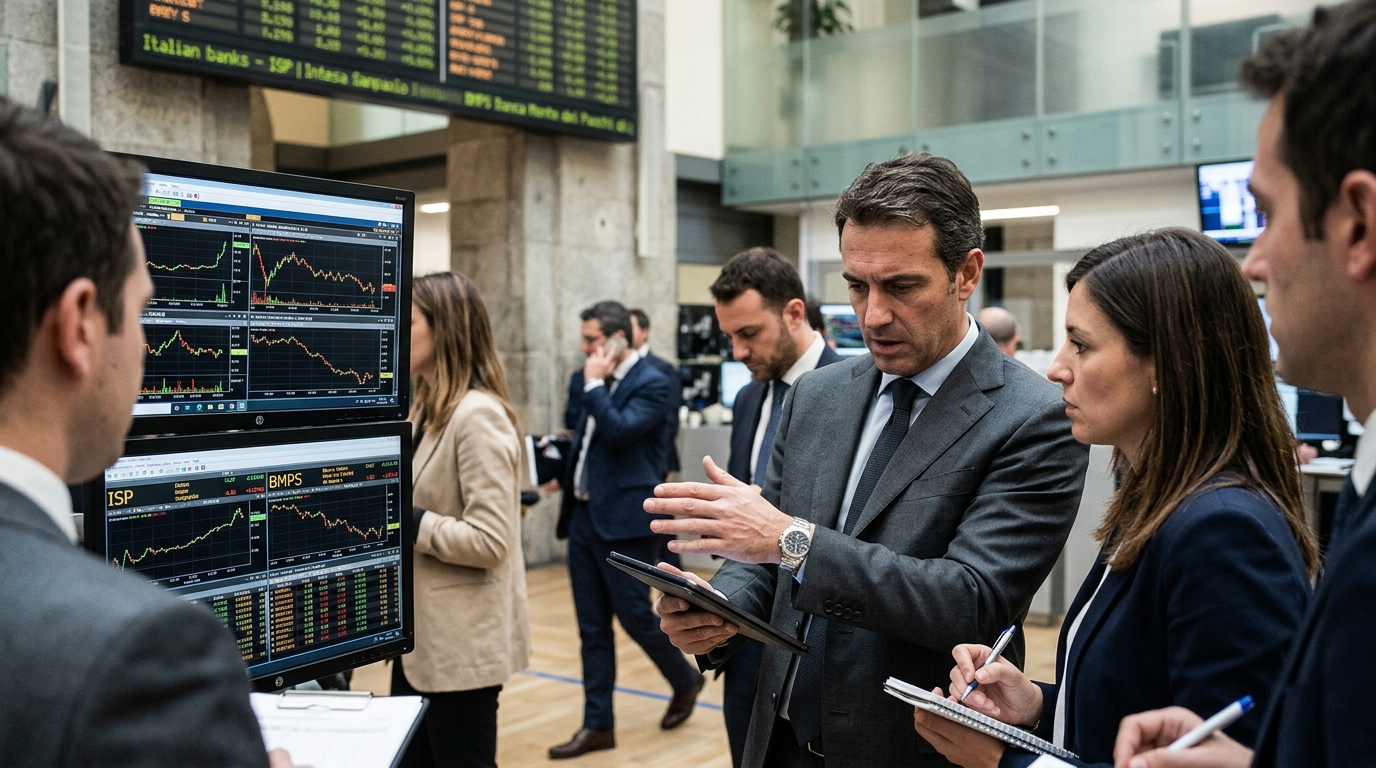
The contest for Monte dei Paschi di Siena has reached its terminal phase. Over 48 hours this weekend, Intesa Sanpaolo did two things that compress the remaining uncertainty into a single, dated event: it added €800 million in cash to the bid, conditional on shareholders rejecting CEO Luigi Lovaglio’s counter-plan, and then announced it had secured the commitment of Delfin, MPS’s largest shareholder.
Intesa raised its takeover offer for Monte dei Paschi di Siena on Saturday, saying it would pay shareholders a further €800 million in cash if they reject MPS’s counter plan. The revised offer pays MPS shareholders €1.25 per share in cash, increasing an earlier €1.00 cash component, on top of 1.6 newly issued Intesa shares offered for each MPS share. That sweetener raises the bid’s cash component by 25%, but represents an overall improvement of only 2.3% based on Friday’s closing price.
The board of Delfin, the holding company for Italy’s Del Vecchio family, will support Intesa’s tender offer with its 17.6% stake in Paschi, according to a statement from Intesa late Sunday. Delfin holds 534.68 million MPS shares, all of which are covered by the undertaking. Delfin has also committed to attend MPS’s shareholder meeting and vote in line with the terms of Intesa’s offer.
The Structure of the Vote
Lovaglio’s counter-plan calls for MPS to make two separate all-share takeover offers for wealth manager Banca Generali and rival lender Banco BPM, positioning MPS as an active consolidator rather than a takeover target. The vote has become central to the contest because Italian takeover rules require Lovaglio to obtain shareholder approval before advancing the counter-plan.
The green light for Lovaglio’s plan would need a two-thirds majority, 66.7% of votes cast. With Delfin now siding with Intesa, Lovaglio must rally a wide base of investors to reach that threshold. Among the other major shareholders is the Caltagirone group at approximately 10.26%. Rome still owns about 4.86% of Monte dei Paschi and has indicated it does not plan to step in. Italian press reports say Francesco Gaetano Caltagirone opposes combining the Siena lender with Banco BPM.
The arithmetic matters here. Delfin’s 17.6% pledged against the counter-plan, Rome’s 4.86% sitting on the sidelines, and a Caltagirone group hostile to the Banco BPM element of Lovaglio’s plan leaves the CEO with a structurally improbable path to 66.7%. MPS CEO Lovaglio had expressed confidence, counting on support from foreign investors and hoping the October 29 meeting would not turn into a referendum between Intesa’s offer and MPS’s plan. But following Intesa’s latest move, a referendum now seems inevitable.
Options Market Framework
Because part of the payment is Intesa stock, the value MPS investors would receive will swing with Intesa’s share price right up until the vote. By tying the extra €0.25 to a rejection of Lovaglio’s Banco BPM and Banca Generali plans, Intesa is pushing uncertainty into a single binary event, which makes BMPS trade more like a merger arbitrage than a regular bank stock.
Shares of Intesa Sanpaolo rose 0.8% to €6.373, while Monte dei Paschi gained 1.1% to €11.398 on Monday’s open. With BMPS around €11.40 and the implied offer value above €12 at current ISP levels, the spread is the market pricing in two residual risks: that Intesa executes its walk-away warning, and that some unexpected shareholder bloc hands Lovaglio a majority.
For traders structuring a position around the October 29 binary, the relevant framework is a defined-risk approach rather than outright directional exposure, given the event-date clarity.
- Bull case (deal closes): For traders expecting shareholders to reject Lovaglio’s plan, a long BMPS position targeting the offer spread, or a bull call spread above current price with an expiry beyond October 29, captures the closing gap. The conditional €1.25 cash floor provides a cushion on the downside leg.
- Bear case (bid lapses): If you believe Intesa’s walk-away is credible and Lovaglio finds a blocking minority, a defined-risk put structure below €10.00 targets the gap back to pre-bid levels. Intesa’s original June offer represented a premium of approximately 12.5% to MPS’s official closing price as at June 5. A failed deal almost entirely unwinds that premium.
- Neutral case: An iron condor bracketing the current €11.00-€12.50 range into October expiry captures premium from an event that, with Delfin committed, is now more likely to resolve cleanly than not. The risk is a surprise blocking bloc widening the range in either direction.
Risk Factors
The offer is subject to Intesa Sanpaolo acquiring at least 66.67% of MPS’s share capital, a condition that may be waived at its own discretion. That minimum acceptance threshold remains the secondary tripwire: even if Lovaglio loses the October 29 vote, Intesa still needs two-thirds of all MPS shares to tender. Regulatory scrutiny from the ECB and Italian competition authorities is ongoing but has not produced a blocking ruling.
Action Checklist
- Monitor Caltagirone group’s formal voting disclosure ahead of October 29. His 10%+ stake is the most mobile remaining block.
- Track ISP.MI daily. The stock leg of the offer means every 1% move in Intesa shares shifts the implied BMPS offer value.
- Confirm whether the Italian Antitrust investigation alters any offer condition before the vote date.
- Set defined-risk structures with expiries no earlier than November 7 to allow for post-vote settlement mechanics.
- October 29 is the event date. All positions should be sized to the scenario where Intesa walks and BMPS retraces 15-20%.