The ticker is only the beginning. Here is what comes next.
You finally find a stock you like.
Then you open the options chain.
Which expiration? Which strikes? What entry price? How much is at risk?
Suddenly, finding the stock feels like the easy part.
Matt, the trader behind Income Blueprint, knows that bottleneck.
He describes going through 40 or 50 stocks, sometimes finding one he liked only to discover the options didn’t fit.
That’s the problem he built the tool to help solve.
Income Blueprint ranks stocks with a five-part scorecard, then evaluates the options for pricing, liquidity, and potential return.
It surfaces three top-ranked stock signals, with the available approaches for each.
Open a setup and you can review the proposed options, entry price, expiration, and estimated risk and reward together.
Now you have something concrete to evaluate before deciding whether to trade.
Matt walks through the process in a free presentation.
He also explains how to get 30 days of tool access and options training at no cost, with no credit card required.
Corteva’s First Report as a Crop-Protection Company Missed. The Options Market Called It.
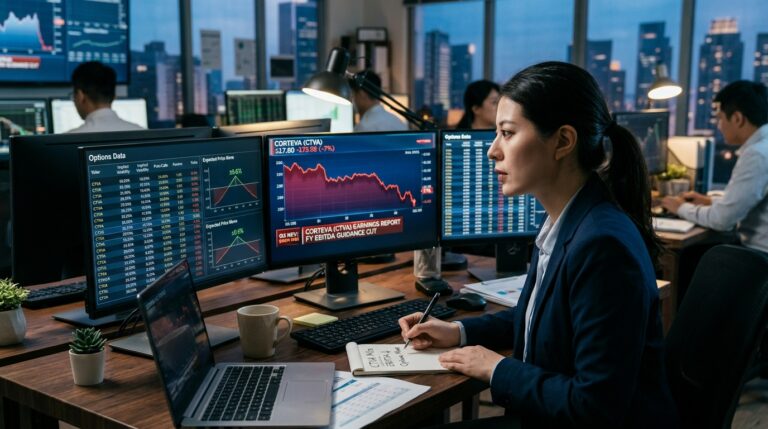
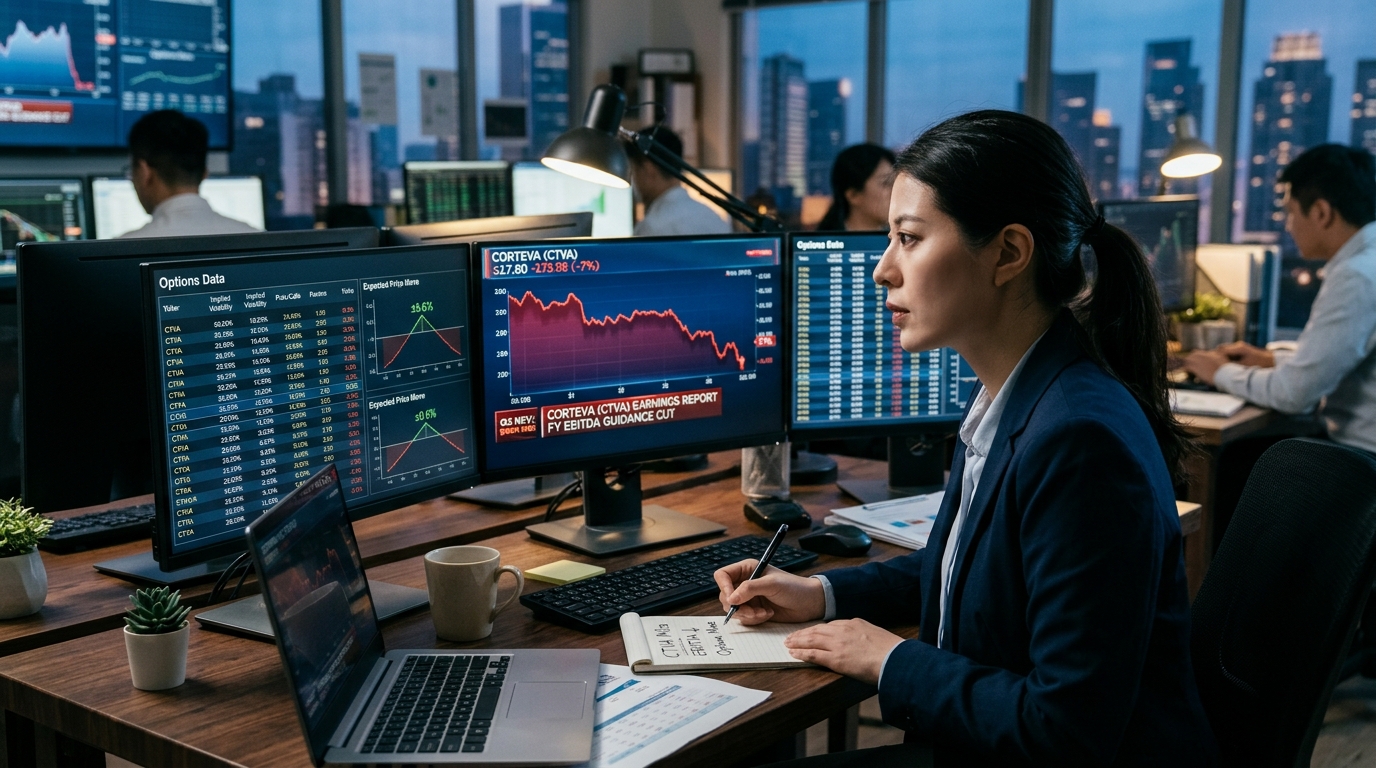
The options market had an answer before Corteva reported. Ahead of the November 11 close, implied volatility on CTVA priced an expected earnings move of plus or minus 9.6%. The actual overnight move landed at roughly minus 7.25%, inside that range but directionally unambiguous. Corteva stock slid 6.4% in after-hours trading to reach $11.36 after the company reported its first set of quarterly results as a pure-play crop protection company, delivering figures that fell short of Wall Street’s expectations on both the top and bottom lines.
This was not a close miss. Non-GAAP earnings per share came in at $0.06, missing estimates by $0.04, while revenues declined 9% year-over-year to $1.59 billion, also below projections by roughly $180 million. The quarter that the market was handed is the first clean read on what Corteva actually is now: a standalone crop-protection business with no seed earnings to soften the blow.
What the Numbers Say
Corteva reported a 9% year-on-year decline in net sales to approximately $1.59 billion, reflecting weaker market conditions particularly in Brazil. Organic sales also declined 9%, with overall volumes falling 2% and pricing decreasing 7% due to competitive pressure on mature crop protection molecules in Brazil and acetochlor in the United States.
Adjusted Pro Forma Operating EBITDA for Q3 declined 17% to $222 million, while the company reported a $54 million loss from continuing operations after tax, compared with $60 million in profit a year earlier. The EBITDA shortfall is the more important figure. It tells you the margin profile of the stripped-down entity is thinner than analysts modeled and that Brazil is not a one-quarter aberration.
On guidance: Corteva revised its full-year 2026 financial guidance, citing subdued market conditions in Brazil’s crop protection segment. The company now expects Adjusted Pro Forma Operating EBITDA between $1.1 billion and $1.125 billion, and Adjusted Pro Forma Operating EPS of $0.76 to $0.80 per share. The EPS range technically beats the FactSet consensus of $0.60, but the EBITDA band is what tells the structural story, and it is well below what the combined Corteva had been targeting when it walked investors through the separation math.
Why the Reaction Was Earned
On October 1, 2026, Corteva completed the spin-off of its seed operating segment into Vylor Inc. through a pro rata distribution to holders of record. Seeds generated around 66% of profits in 2025, with the remaining 34% coming from crop protection. That math defines the problem. What is left after the spinoff is the lower-margin, more cyclically exposed half of the old company, now asked to stand on its own in the first quarter where crop protection seasonally bleeds cash.
Corteva’s guidance revision highlights the challenges facing the agriculture sector, particularly in Brazil’s crop protection market. Farmers there are grappling with limited liquidity, elevated financing costs, and strategic purchasing delays, which have collectively dampened demand and intensified pricing pressures. Those are not conditions that resolve in a single quarter. Generic competition is intensifying on older molecules, and Corteva’s Brazil exposure proved to be a more significant drag than the market had priced in.
Comparables offer little comfort. With CTVA’s EBITDA guidance now cut, those forward multiples will need to be recalculated from a lower base. Bayer Crop Science, which does not trade as a standalone, adds further context: its scale advantages in Brazil put smaller pure-plays at a structural pricing disadvantage on mature molecules.
Options Analysis
Going into the report, the implied expected move of 9.6% proved reasonably calibrated. The actual realized move of approximately 7.25% fell inside the straddle’s range, meaning premium sellers who legged into defined-risk structures before the close collected a modest edge. Ahead of the report, analysts had already trimmed their EPS consensus estimate by roughly 7% over the prior 30 days, and UBS had lowered its price target on the stock, reflecting cautious sentiment around the newly independent crop protection entity. That pre-earnings IV expansion was the signal worth watching.
Post-event, with the catalyst resolved and the stock sitting near its 52-week low, the dynamics shift. Twelve of 14 analysts rate Corteva a buy, with a consensus price target of $17.05, implying 40% upside from recent levels. The stock has been under pressure since the spinoff, trading near its 52-week low. Wide analyst-to-market divergence at a 52-week low with elevated realized volatility is a scenario that rewards precision over conviction.
Structured Trade Framework
Bull case: If you believe Brazil conditions stabilize by Q1 2027 and new active ingredient launches support volume recovery, a defined-risk long through a January call spread (buy the $12 strike, sell the $15 strike) limits downside to the premium paid while targeting the analyst consensus range. The 40% gap between current price and consensus target provides the fundamental anchor.
Bear case: For traders expecting Brazil farmer liquidity constraints to persist through the Southern Hemisphere season, a put debit spread (buy the $11 put, sell the $9 put) captures continued downside with defined risk. The 52-week low is thin support after a guidance cut of this magnitude.
Neutral case: With realized volatility elevated and IV likely to compress now that the earnings event has passed, a short strangle sized small collects decay if CTVA consolidates between $10 and $13. Undefined-risk structures are not appropriate here given the fundamental uncertainty; use a condor to cap exposure.
Risk Factors
A revenue miss, a swing to a GAAP operating loss, a guidance cut tied to Brazil, and the added uncertainty of operating as a newly independent business for the first time all converged to push Corteva shares toward their 52-week low. Any further deterioration in Brazilian agricultural credit conditions or renewed acetochlor pricing pressure in the U.S. would reopen the downside. Conversely, an early-season rebound in Latin American demand or a competitor stumble (FMC’s ongoing restructuring, for instance) could accelerate volume share capture faster than the current guide assumes.
Action Checklist
- Mark CTVA’s 52-week low as the near-term line in the sand; a close below that level on volume above the 20-session average changes the technical picture materially.
- Monitor Brazil agricultural credit conditions and Southern Hemisphere planting-season reports through December for signs the volume drag is temporary or structural.
- Recalculate forward EBITDA multiples using the revised $1.1-$1.125 billion guidance midpoint before comparing CTVA to FMC or applying JPMorgan’s 10x target.
- For defined-risk structures, wait for IV to compress post-event before buying premium; the straddle has already paid out its expected move.
- Track Bayer Crop Science and Syngenta pricing actions in Brazil as a leading indicator for whether the competitive pricing environment has found a floor.