October 27, 2026
Bonus Content: Brazil’s Lula Win Cost 20 Cents on the Dollar Overnight
The Dollar You Saved in 2000 Buys About 51 Cents Today.
For U.S. savers age 55+ with $50,000 or more in an IRA, 401(k) or savings. Free of charge, no obligation to buy anything.
| SEND ME THE FREE GUIDE → |
Pull out a statement from 2000 and the number on it looks healthy. It is the wrong number to look at. The question is not how many dollars you have – it is what those dollars still buy.
The same dollar, twenty-six years later
It now takes about $1.95 to buy what one dollar bought in 2000.1 Run that backwards and the dollar you set aside in 2000 has the purchasing power of roughly 51 cents today. Prices across the economy have risen about 95% over the period.1
That is not a conspiracy and nobody took anything out of your account. It is arithmetic. Dollars were added to the system faster than goods were, and every saver holding dollars paid the difference. A retirement account invested entirely in dollar-denominated assets carries that cost whether or not the balance goes up.
Over the same twenty-six years the national debt crossed $40 trillion.2 Washington has three ways to deal with a debt that size: tax more, cut spending, or let inflation shrink what it owes in real terms. Many economists consider the third the path of least political resistance. That is an opinion about the future, not a forecast – but it is the reason a lot of savers want part of their retirement in something that cannot be issued by decree.
Gold is not an income asset and it does not pay a dividend. What it does is sit outside the printing press. There is no central bank that can create more of it, no issuer that can default on it, and no board that can dilute it. Over that same stretch it went from about $290 an ounce to where it trades today.3
The free 2026 Gold IRA Guide walks through exactly how a rollover from an IRA, 401(k) or TSP works, which metals the IRS allows, how insured depository storage works, and the mistakes that cost retirees the most. It is free and it takes about thirty seconds to request.
Claim Your Free 2026 Gold IRA Guide →
| SEND ME THE FREE GUIDE → |
Rock legend Ted Nugent and former White House Press Secretary Sean Spicer are official endorsers and clients of Bishop Gold Group. 10 years in business – 5-star rated on Trustpilot and Google – Mint Authorized Dealer
Prefer to speak to someone? U.S. – based specialists, no pressure, no jargon.
Mon-Fri – 7am-5pm PT
Sources
1 U.S. Bureau of Labor Statistics Consumer Price Index (CPI-U), 2000 to 2026. $1.00 in 2000 equates to approximately $1.95 in 2026 – cumulative inflation of roughly 95%; the inverse gives purchasing power of about 51 cents.
2 U.S. Treasury total public debt outstanding, which passed $40 trillion in August 2026 as widely reported.
3 LBMA gold price, 31 December 1999 ($290.25/oz) to September 2026. Past performance is not a guarantee of future results.
Past performance is not a guarantee of future results. Precious metals are volatile and can decline in value. Figures here are historical and are not a prediction or a recommendation to buy or sell any asset.
Brazil’s Lula Win Cost 20 Cents on the Dollar Overnight
Markets do not need certainty. They only need a range of outcomes to price. What they cannot handle is a contested result with no visible resolution date, and that is exactly what Brazil handed them Sunday night.
Brazilian Senator Flávio Bolsonaro announced late Sunday that his legal team will formally petition to annul the country’s presidential runoff election following his narrow defeat to incumbent President Luiz Inácio Lula da Silva. The specific grievance: Bolsonaro focused his criticism on STF Justice Cristiano Zanin, who issued a last-minute ruling extending polling hours across Brazil until 7 pm Brasília time following emergency petitions regarding transport blockades and severe weather. The defeated senator condemned the decision, pointing out that Justice Zanin previously served as Lula’s personal defense lawyer before his appointment to the high court.
The scale of Flávio Bolsonaro’s loss to Lula, by more than 4.4 million votes, and the fact both campaigns asked for more time due to logistics and weather make any annulment unlikely, analysts said. Paulo Sotero, of the Brazil Institute at the Wilson Center, told CNN that Bolsonaro’s chances of winning a recount or having a new election are very slim. The legal probability is low. The market probability of sustained uncertainty is not.
The Numbers Behind the Shock
Lula secured 51.79% of the votes against the 48.21% obtained by Bolsonaro. This is a reversal of first-round positioning: in the first round earlier this month, Bolsonaro finished ahead, and markets leaned into a market-friendly outcome. Polymarket and Kalshi had priced a Bolsonaro win at roughly 80% the morning of the vote, meaning the options and prediction markets were both caught severely offside.
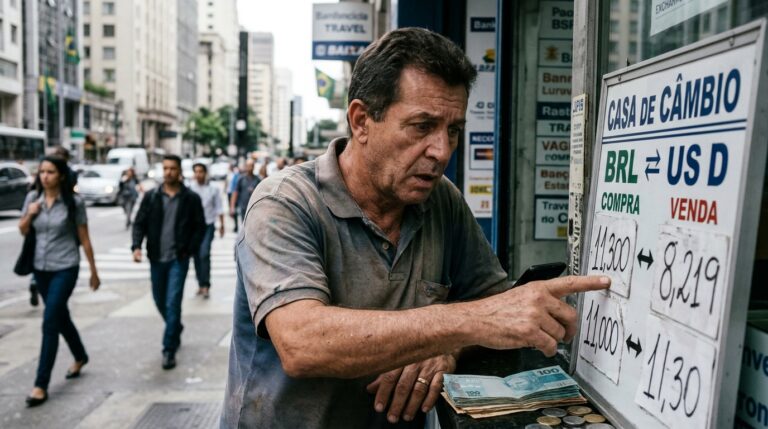
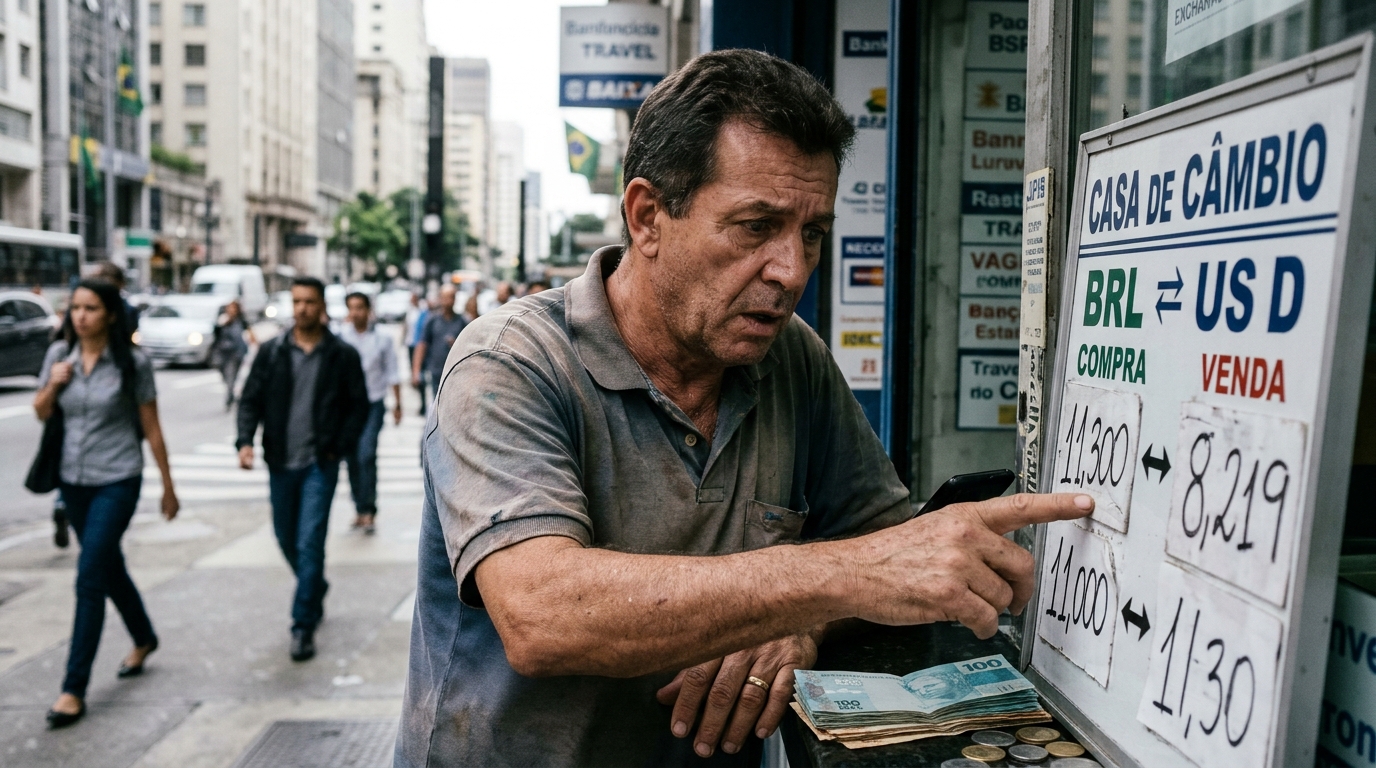
By late Sunday, currency derivatives were implying roughly R$5.56 per dollar. The spot rate had been trading around the R$5.00 area into the vote, which is now the single most-watched level in Brazilian finance. On the equity side, the Tokyo-traded Ibovespa-linked ETF fell roughly 13% in early trading following the unexpected election result.
Goldman Sachs outlined an extreme scenario with a 10% weakening of the real and a 200 basis point surge in debt yields. “We expect a sharp market reaction on Monday, with aggressive repricing, a selloff in assets and interest rate futures likely to hit their upper limit shortly after the open,” said Luis Felipe Vital, head of macro strategy at Warren Investimentos.
Strategic Interpretation
This is not about Lula’s policy platform. It is about the unwind of three weeks of positioning that crowded into a Bolsonaro trade after he finished first in the first round. After the first round, markets rose, assuming a Bolsonaro victory. The annulment push adds a second layer: not just a policy regime change, but a constitutional standoff that keeps the risk premium elevated even after the initial gap lower stabilizes.
Lula faces a Congress where Bolsonaro’s Liberal Party holds the largest bloc, and a substantial public debt that he would need to stabilize. The fiscal arithmetic was already difficult before the election result landed. A protracted legal dispute delays any policy signal and keeps the cost of Brazilian sovereign risk elevated.
Options Market Analysis
EWZ implied volatility was elevated into the vote, consistent with markets pricing a large election-related move. Pre-election, EWZ put-to-call volume skewed heavily toward calls, implying the crowd was positioned for a melt-up on a Bolsonaro win, not a collapse. That positioning mismatch amplifies the move in both directions. The market is not done resetting.
Structured Trade Framework
Bear case: For traders expecting the real to retest the R$5.56 implied by overnight futures and the annulment fight to drag for weeks, a defined-risk structure in EWZ, such as a put spread buying the November 28 put and selling the November 22 put, limits premium outlay while capturing a continued move lower. IV at elevated levels makes premium selling the cleaner edge on the other side of expiry.
Bull case: If you believe the TSE dismisses Bolsonaro’s petition quickly, clearing the legal cloud, and Lula moves to reassure markets on fiscal continuity, a defined-risk structure would be a call spread in EWZ with November expiration, targeting a partial mean reversion. PBR is the single-name alternative, given that oil at current levels provides a fundamental floor regardless of who governs Brasília.
Neutral case: With IV elevated, premium selling via an iron condor on EWZ in November captures the elevated vol surface without requiring a directional call. The risk is that the annulment dispute generates a fresh gap, so position sizing is critical.
Risk Analysis
The primary risk is not Lula’s presidency. It is duration uncertainty. A legal contest that runs into December keeps the risk premium embedded in BRL and Ibovespa names without providing a catalyst to compress it. A secondary risk is external: the result blocks a rightward shift in Latin America that U.S. President Donald Trump has backed, raising the prospect of trade and diplomatic friction that compounds the domestic fiscal story.
Brazil’s political uncertainty compounds an already fragile Latin American risk backdrop. Global oil supply disruptions through critical maritime chokepoints add an external commodity shock that directly pressures emerging-market fiscal positions.
Forward Outlook and Action Checklist
B3’s open this morning is the first unambiguous price signal. Watch whether the Ibovespa gap holds or fills intraday, and whether the real stabilizes above or below R$5.00. The TSE timeline on Bolsonaro’s petition is the second variable: a rapid dismissal removes the tail risk; a prolonged review keeps it on the table.
- Monitor USD/BRL: R$5.00 is support/resistance; a close above signals sustained pressure
- Track EWZ IV: if it compresses materially, premium-selling structures become more favorable
- Watch PBR separately from the index: oil price provides a partial offset to political discount
- Size positions for a contested-result scenario lasting 2 to 4 weeks, not days
- Any TSE ruling on the annulment petition is an immediate catalyst in either direction