October 26, 2026
Bonus Content: Honeywell’s Armor Legacy Is Now a Separate Stock
Tim Plaehn here.
Most dividend stocks only pay you once every three months.
But with this little-known $15 gold investment, you could get paid every Friday.
In one month, those weekly payments could add up to $1,127.
I call them Friday Golden Payments.
See here how to collect gold income every Friday.
To your income,
Tim Plaehn
Chief Income Strategist, Investors Alley
Honeywell’s Armor Legacy Is Now a Separate Stock
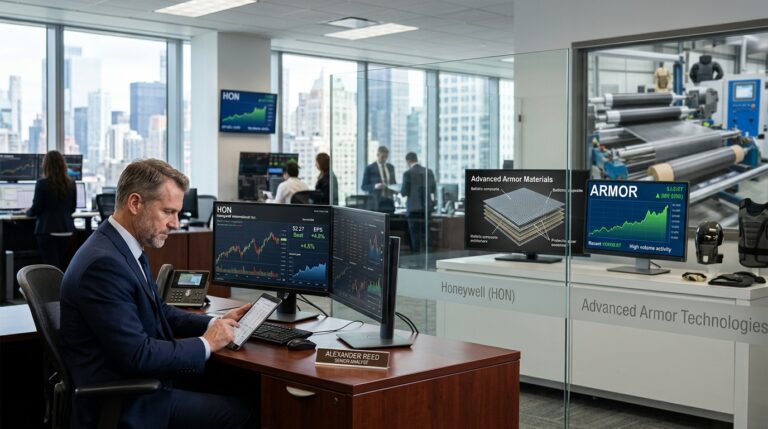
Markets rarely punish a beat. They also rarely reward one that arrives without a growth story attached. Honeywell’s Q3 result on October 22, 2026 was textbook: adjusted EPS of $2.27 beat the $2.17 consensus by 4.6%, organic sales grew 7%, segment margin expanded 370 basis points to 21.3%, and full-year adjusted EPS guidance was raised to $8.40 to $8.45. The stock moved roughly 1% to 2% higher. Options had priced a 5.35% swing in either direction. The market collected its data and moved on.
That reaction is not a slight against HON. It reflects something structural: the company that investors are now buying is a pure-play automation business, not a defense materials platform. The ballistic protection lineage, including Spectra fiber technology used across ballistic and composite applications, was spun out as Solstice Advanced Materials (SOLS) on October 30, 2025. If you are looking for the specialty materials angle tied to that legacy, it now sits at SOLS, not at HON.
This is where the materials science matters. Graphene, a single-atom-thick carbon lattice, is often cited in academic literature for exceptionally high intrinsic tensile strength under ideal conditions. But translating that into scalable, repeatable armor manufacturing is the hard part. As of 2026, the most advanced tactical armor is still centered on multi-material stacks, commonly pairing ceramics with polymer backers and UHMWPE laminates, with ongoing experimentation around lighter-weight designs and sensor integration. Solstice’s Spectra fiber, the UHMWPE product at the center of that stack, is 15 times stronger than steel by weight. In January 2026, SOLS said it would invest more than $220 million to expand production at its Colonial Heights, Virginia ballistic fiber facility, with multiple projects expected to create 100 new full-time jobs by 2029.
Could $50 Become $500? This Options Strategy Aims For It
Most rookie option traders make the same costly mistake, and it keeps them from bigger gains. This simple, repeatable strategy shows you the fix, then hands you step-by-step trade blueprints you can copy tonight. Learn how to ignore the market noise and go after 10x bigger potential gains.
The materials transition from prototype to fielded product is already underway, but the marketing claims are ahead of the procurement cycle. Broad assertions like “three times as many hits before failure” or “15% to 20% lighter” vary dramatically by threat level, plate design, and test standard, and are not consistently supported by public, apples-to-apples data. The defense supply chain is paying attention, though: Honeywell Aerospace said in March 2026 that it signed a supplier framework agreement with the U.S. Department of War that includes a $500 million multi-year investment to upgrade production capacity, a signal that Tier 1 suppliers with defense exposure are gaining structured government backing.
Structured government backing for Tier 1 suppliers is not unique to Honeywell’s supply chain. Lockheed Martin’s PAC-3 and THAAD framework agreements show how defense primes absorb large procurement commitments without an immediate stock reaction.
Options Framework
HON itself is now a lower-volatility automation compounder. Its post-earnings IV compression was sharp, and with backlog at nearly $19 billion and free cash flow conversion at 95%, the setup favors covered call overlays rather than directional bets. For traders expecting continued margin expansion through Q4, a defined-risk bull call spread in the $215 to $230 range captures the raised guidance path without outsized premium outlay at current volatility levels.
SOLS presents a different profile: a newly independent specialty materials company with a concentrated defense exposure, active capital deployment, and a shorter public track record as a standalone entity. IV is less liquid but the event calendar, including facility expansion progress and any government contract flow, creates discrete catalysts. If you believe next-generation armor materials meaningfully expand beyond pilot programs, SOLS is the more direct expression. A defined-risk long call structure timed to publicly visible facility milestones can express that optionality without unlimited downside.
The defense procurement calendar that governs SOLS’s event risk extends well beyond any single facility milestone. The missile restock cycle driving Pentagon spending shows how multi-year restocking programs create discrete, trackable catalysts for defense materials suppliers.
Risk and Forward Outlook
Scalable graphene production remains the chokepoint. High-quality production at volume is still a manufacturing challenge, and composite coating integration with UHMWPE systems adds process complexity. SOLS carries the execution risk of a $220 million buildout against a shifting defense procurement calendar. HON carries none of that, which explains both its stability and its ceiling.
- HON: EPS $2.27, +4.6% beat; organic growth 7%; FY2026 adjusted EPS guide $8.40 to $8.45
- SOLS: $220M Virginia expansion, Spectra fiber 15x stronger than steel by weight
- Options priced HON at +/- 5.35% into Q3; actual move was roughly +1% to +2%
- Graphene armor fielding window: timelines remain uncertain and program-dependent
- Bull case HON: call spread $215 to $230; Bull case SOLS: defined-risk long call tied to facility progress