Thursday’s pre-dawn earnings call from Taiwan Semiconductor Manufacturing (TSM) is the most important chip-sector event of the quarter. Not because the revenue number is in doubt, TSMC already reported September monthly sales that put Q3 revenue at approximately $46.7 billion, above the top of the company’s own guidance of $44.6 billion to $45.8 billion. What remains open is everything else: the margin picture, the 2nm ramp commentary, the Q4 guide, and how management characterizes AI demand heading into 2027.
The revenue number is already impressive on its own terms. TSMC booked $40.2 billion in Q2 2026 revenue, up 33.7% year over year, and analysts expect Q3 to push that pace further. Wall Street consensus sits at roughly $4.41 in earnings per share versus $2.85 in the same quarter a year ago, a 55% jump in profit driven almost entirely by the AI hardware buildout.
High-performance computing now accounts for about two-thirds of TSMC’s wafer revenue. When one customer category drives that share of the business, every signal from that category matters disproportionately. Investors will focus on whether HPC revenue holds near or above the 66% seen in Q2, and whether gross margins land inside the guided range of 65% to 67%.
The Business
TSMC is widely viewed as the dominant manufacturer of leading-edge chips. Every Nvidia GPU destined for a data center, every Apple silicon chip, and most AMD processors start life on a TSMC wafer. That concentration gives the company pricing power that few manufacturers in any industry have ever held: 2nm wafer prices are widely reported to exceed $30,000, roughly double the cost of 4nm production.
The Arizona expansion makes that position even more durable. In July, TSMC committed an additional $100 billion to its Arizona operations, bringing total planned U.S. investment to $265 billion across up to 10 fabs and two advanced packaging facilities. Around 30% of TSMC’s 2nm and more advanced capacity will eventually sit in Arizona, giving its U.S. customers a more geographically diverse supply footprint. The company also raised its 2026 capital expenditure guidance to $60 to $64 billion, with 70% to 80% earmarked for advanced-process technologies.
Why Wall Street Is Paying Attention
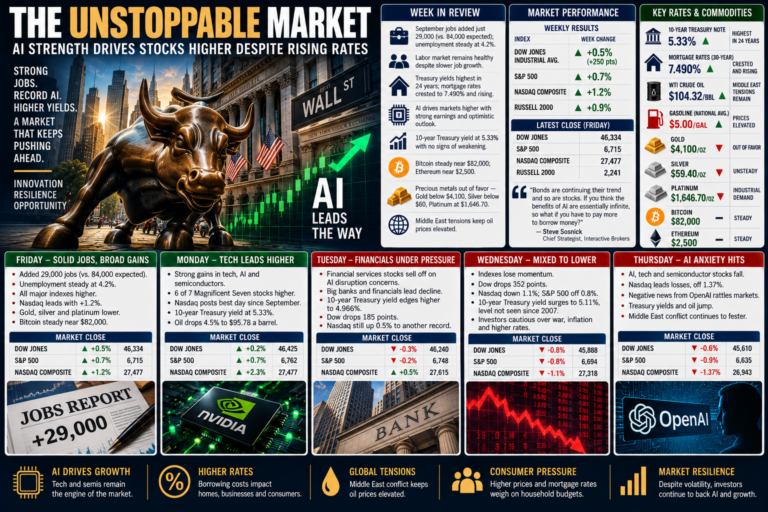
The PHLX Semiconductor Index ran 73% year to date through late September before retreating after the Financial Times reported that OpenAI told investors its annualized revenue was nearing $50 billion at the end of September, below earlier figures that had circulated publicly. That pullback created a reset point. Wall Street carries a Strong Buy consensus on TSM, with an average price target of roughly $543, implying about 20% upside from recent levels. Options traders are pricing in a 5% move after earnings, suggesting a contained reaction rather than a blowup.
TSMC’s 2nm process, designated N2, entered high volume manufacturing in late 2025, with volume production expected to ramp in the second half of 2026. Every N2 wafer that ships is another data point confirming that the next generation of AI chips can actually be manufactured at scale. Management has flagged that new-node ramps and overseas expansion can pressure margins, so margin guidance on Thursday deserves as much attention as the revenue beat.
What Could Go Wrong
The risks cluster around two themes. First, the cost of building fabs on three continents simultaneously. TSMC has warned that overseas expansion would widen margin pressure by several percentage points as its geographic footprint scales, and the Arizona workforce challenge, building a 2nm-capable team from scratch, remains the least predictable input. Second, geopolitical concentration. Most of TSMC’s most advanced capacity still sits in Taiwan, a fact no quarterly result can change. The stock trades at a forward P/E of roughly 22 times, below the semiconductor sector average, and that discount is almost entirely explained by Taiwan risk. Any escalation beyond routine tension would compress the multiple immediately and independently of the operating results.
There is also a subtler risk: the OpenAI revenue revision that rattled semiconductor stocks last week served as a reminder that AI infrastructure spending ultimately depends on AI revenue. If model monetization continues to underperform the estimates that drove chip orders, capital spending could slow before TSMC’s newest fabs reach full utilization.
The Bottom Line
TSMC arrives at Thursday’s call with momentum, a verified revenue beat already baked in, and the clearest view of AI chip demand available in any public earnings report. The number that will actually move the stock is Q4 guidance. If management holds a firm outlook for advanced-node demand heading into 2027, the geopolitical discount compresses modestly and the stock works higher. If guidance disappoints, the multiple has room to fall further. For investors who accept the Taiwan tail risk and want exposure to AI infrastructure without paying Nvidia’s valuation, TSMC at 22 times forward earnings remains the most defensible entry in the sector.