October 28, 2026
Bonus Content: Vertiv’s 35% Growth Guide Has to Clear a 10.4% Options Bar Today
Dear Income Seeker,
If you’re struggling to find high-probability income trades…
Or think you’ve found them…
Only to be frustrated – and disappointed – with the money you’re bringing in…
You owe it to yourself to check out this website.
Because it will give you the opportunity to get your hands on a little-known 1-hour trading secret… 100% free of charge.
Do your future self a big favor and claim a copy now.
Because at some point soon, it won’t be free.
To better trading,
– Drew Day
Partner
Base Camp Trading
Vertiv’s 35% Growth Guide Has to Clear a 10.4% Options Bar Today
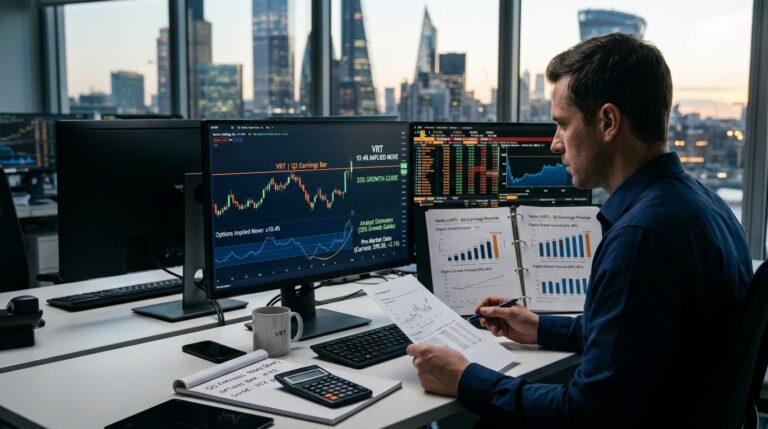
Markets don’t care about a good growth rate. They care about whether the number delivered clears the bar that was already priced. For Vertiv (VRT), reporting before the open this morning, that bar is about a ±10.4% move baked into the options market as of October 26’s close, against a company that guided organic net sales growth of 34–36% and is still carrying active securities litigation tied to allegations around its 2022 disclosures.
Those two facts live in the same sentence for a reason. One is about momentum. The other is about trust.
What the Desk Is Expecting
For Q3, Vertiv guided net sales of $3.65–3.85 billion, organic net sales growth of 34–36%, and adjusted EPS of $1.77–$1.83, representing 43–48% year-over-year growth. The Street’s consensus landed at $1.82 EPS on revenues of $3.76 billion, up about 40.6%.
Adjusted operating profit is projected at $898–938 million, with an adjusted operating margin of 24–25%. That would mark continued expansion from Q2’s 22.6% adjusted operating margin, itself up 410 basis points year-over-year. Adjusted diluted EPS in Q2 came in at $1.52, a 60% increase versus the prior year.
Q2 was not a clean quarter, though. Revenue of $3.27 billion missed the roughly $3.39 billion consensus by about $115 million, or roughly 3%. Management attributed the shortfall to minor timing shifts, and shares fell 17.3% on the day. That drop happened even as EPS beat and management raised full-year guidance. This is the precedent Q3 must now answer.
The Strategic Interpretation
The reframe that matters here: this is not about whether Vertiv grows fast. It clearly does. The company has beaten the Zacks consensus estimate in all four trailing quarters, delivering an average earnings surprise of 12.61%. The question is whether execution on revenue timing is clean enough to prevent another reaction like July 29, 2026.
Supply-chain congestion and execution complexities tied to large-scale infrastructure projects, along with tariffs and manufacturing investments, have been flagged as potential headwinds. The July miss was also blamed on project timing. If that language reappears today, the market’s memory is sharp.
Valuation adds friction. Vertiv’s trailing P/E stands at roughly 47x. The shares were up 4.39% in Tuesday’s regular session heading into today’s release, meaning some positioning was already underway.
Vertiv is not the only data-center infrastructure name where valuation and execution credibility are being tested simultaneously. Supermicro’s margin expansion rewrote its investment thesis even as revenue disappointed, a reminder that the market can reprice infrastructure suppliers quickly when the right line moves.
Litigation Overhang
A putative securities class action, In re Vertiv Holdings Co Securities Litigation, has been pending since May 2022, alleging certain public statements were materially false regarding inflationary and supply chain pressures. Multiple law firms launched additional investigations following the Q2 earnings-day drop, citing disappointing results and unexpected execution challenges. The case remains active. Every quarter that surfaces a top-line miss reopens the credibility question the litigation is built on.
Options Market Analysis
Options priced about a ±10.4% move for today’s report as of October 26. In July, options priced ±10.5% and the stock closed down 17.3%, decisively breaking through the implied range to the downside.
Implied volatility will typically collapse once the numbers are out, punishing directional long premium positions that don’t capture a move exceeding the implied range.
Structured Trade Framework
Bull case: If you believe Q3 revenues come in at or above $3.76 billion with no timing-shift language and Q4 guidance holds the 34–36% organic trajectory, a defined-risk call spread in the November expiration captures upside participation with capped premium exposure to IV crush. The $188–232 strike range reflects the roughly ±10.4% expected move corridor off the reference price used by the options market.
Bear case: For traders expecting a repeat of July’s revenue miss, a defined-risk put spread below current levels exploits elevated pre-event IV. The position benefits if VRT re-tests the post-Q2 range, and the defined structure contains the risk of a sharp upside gap if the quarter clears cleanly.
Neutral case: A short iron condor structured around the implied wings collects premium if VRT stays inside its expected move. The risk is a repeat of July, where the actual move at peak reached about -18%. Size accordingly.
Risk Analysis and Forward Outlook
The core risk is asymmetric: a clean beat likely produces a measured rally, given 4%-plus pre-event drift already in the shares. A miss on revenues, however minor, could trigger outsized selling given the litigation backdrop and the July precedent. Coverage focuses specifically on whether growth converts into timely orders and reliable cash generation, which means any management commentary hedging on backlog conversion timing will be scrutinized.
- Verify Q3 organic revenue versus the 34–36% guide before adding directional exposure.
- Monitor Q4 guidance language for any reduction in organic growth expectations from Q2’s raised full-year outlook.
- Check for any litigation update or settlement disclosure on the earnings call or in the 10-Q filing.
- IV crush begins after the event. Any options structure should be established before the numbers or sized to account for the post-event collapse in premium.
- VRT’s 5-year monthly beta of 2.05 amplifies broad market moves; account for index-level risk on the day.