October 28, 2026
Bonus Content: Robinhood Hit a Revenue Record. Its Stock Still Fell 7%.
Hey Trader,
New to options and wondering, “Where on earth do I even start?”
You’re not alone. And you’re also in luck.
Inside Dave Aquino’s latest guide, 11-Hour Options for Beginners, you’ll get the plain English blueprint behind his simple income trading strategy…
Plus the exact “rinse and repeat” ticker he’s used nearly 900 times with a 95.3% success rate over 5 years of wild market conditions.
So you’re not guessing where to begin with this…
You get a real starting point.
An actionable strategy.
And a “battle-tested” ticker that you can start using as early as tomorrow… all FREE
Click below to claim your free copy of 11-Hour Options for Beginners – NOW.
To better trading,
Drew Day
Robinhood Hit a Revenue Record. Its Stock Still Fell 7%.
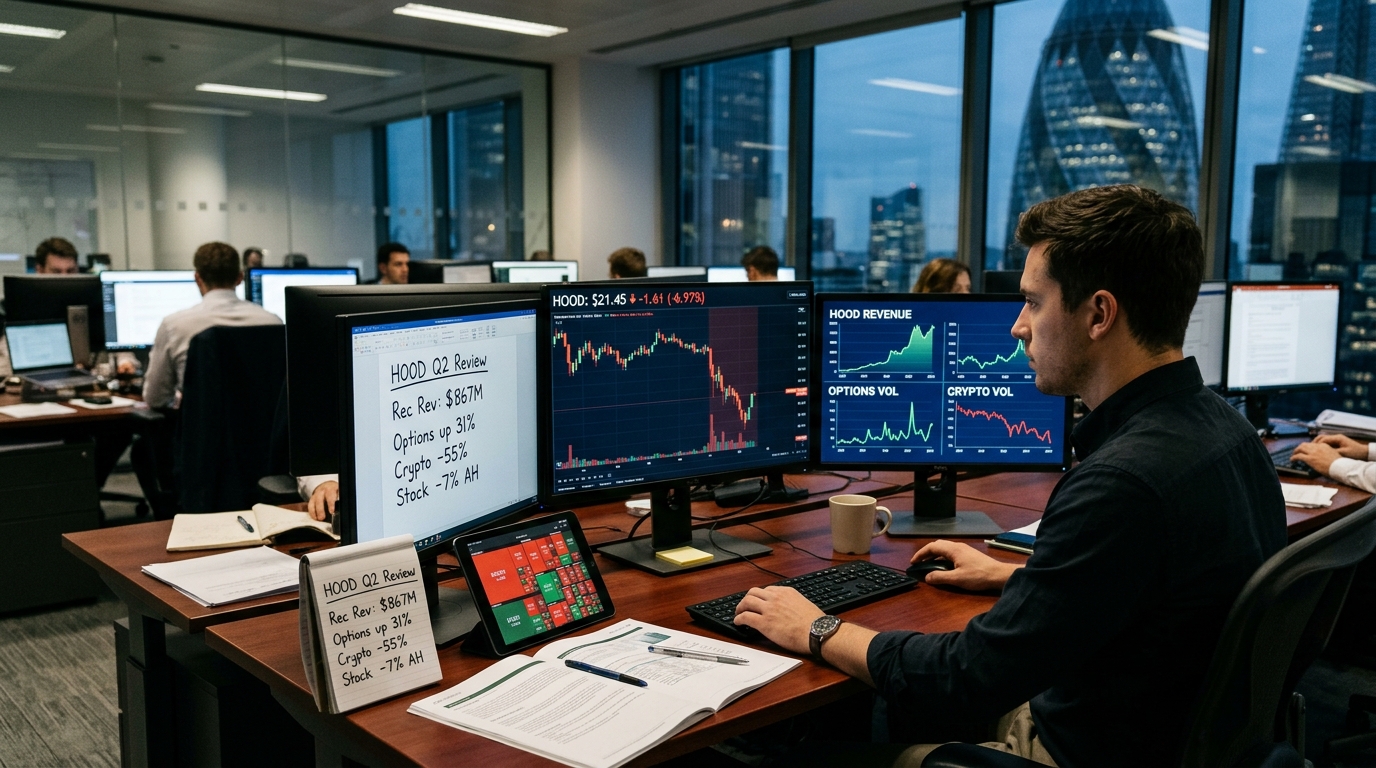
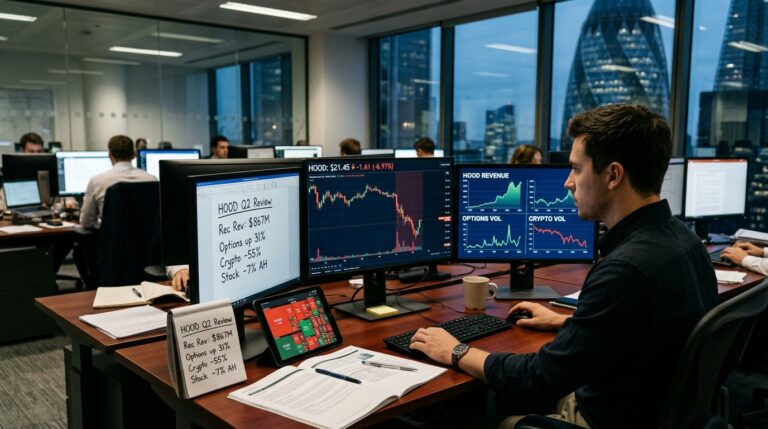
Record revenue does not guarantee a rally. Robinhood proved that Tuesday night, posting its highest quarterly revenue ever while the stock shed roughly 7% in after-hours trading. The math behind the move is not complicated once you pull the line items apart.
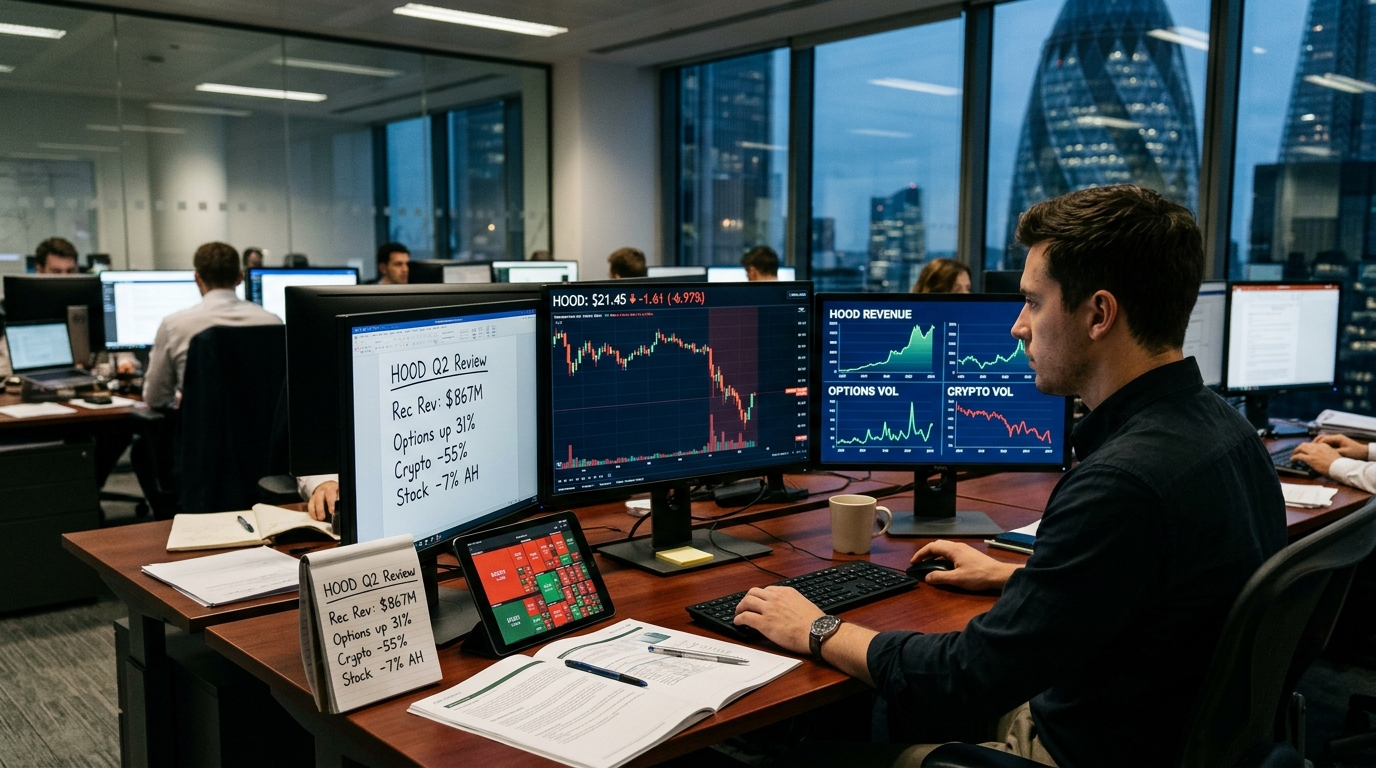
Transaction-based revenues rose 19% year over year to $867 million, driven by event contracts at $173 million (up more than six times), options at $399 million (up 31%), and equities at $121 million (up 41%), partially offset by crypto at $120 million, down 55%. Diluted EPS dropped 16% to $0.51. Total net revenue of $1.424 billion landed just below the $1.43 billion expected. The result: a beat on the adjusted operating line, a miss on the profit line that traders actually price.
What the Numbers Say
Net income included $67 million, or about $0.07 of diluted EPS, of unrealized losses primarily related to the mark-to-market of Robinhood Ventures funds. Strip that out and the adjusted picture is less alarming. Adjusted net income fell just 3% year over year to $550 million, and adjusted EBITDA rose 9% to $808 million. But GAAP is what consensus tracks, and the $0.51 result came in below Wall Street expectations reported by Bloomberg and others.
Equity notional trading volumes jumped 53% year over year to a record $992 billion, and options contracts traded rose 48% to a record 905 million. Funded customers reached 28.7 million, platform assets rose 19% to $396 billion, and Gold subscribers increased 34% to 5.2 million. These are not weak numbers. The problem is that crypto, which once anchored the transaction revenue line, has become a drag.
The Crypto Collapse in Context
This is not about crypto’s performance versus forecasts. Crypto was 37% of transaction-based revenue a year earlier and just 14% in Q3 2026. That compression is structural, not seasonal. Crypto notional trading volume fell 38% to $50 billion for the quarter. Robinhood’s own app volume dropped 48% to $21 billion, while Bitstamp fell a milder 28% to $29 billion.
Take crypto out of both years and Robinhood’s revenue rose about 30%, against 12% with it. That is the platform a post-crypto Robinhood actually is: an options-led retail brokerage with a fast-growing prediction-market overlay. Management said October average daily volumes for equities, options, and crypto were very similar to, or just a touch lighter than, the record Q3 level, while event contract activity was about 10% higher than in Q3.
How Options Priced This Event
The October 30 options expiration implied a 10.26%, or $9.75, move in either direction, priced with the nearest strike at $95. Over the last eight quarters, Robinhood’s average absolute one-day post-earnings move was 9.42%. The market priced modestly elevated uncertainty, and the realized move stayed inside the implied band.
Pre-earnings put/call ratio sat at 0.43, with calls dominant into the report, a sign of bullish positioning that left call holders offside. Post-earnings volatility has compressed after the event. Elevated pre-earnings premium has now largely decayed.
Structured Trade Framework
Bull case: If you believe the options and equities volumes disclosed for Q3, combined with Q4 event-contract momentum running 10% above Q3 levels, represent durable growth, a defined-risk structure would be a bull call spread in the November or December expiration, buying a strike near current levels and selling a higher strike to cap cost. The thesis requires crypto stabilization and no sequential slowdown in options contracts.
Bear case: For traders expecting the revenue miss and EPS shortfall to weigh on momentum-driven holders, a defined-risk put spread below the post-earnings low captures continued selling without the unlimited risk of a naked short. The stock has fallen after each of its last four earnings reports, with declines ranging from 3.61% to 13.24%.
Neutral case: With implied volatility now lower than it was ahead of results, premium selling is less compelling than it was into the report. A calendar spread or a wait for IV to rebuild into the Q4 report cycle is the lower-noise approach.
Risk Analysis and Forward Outlook
Operating expenses grew 16% to $739 million, outpacing revenue growth at 12%. Cost leverage will be a watch item into Q4. On the positive side, management said October net deposits had already topped $13 billion month-to-date entering Q4. Wall Street consensus remains positive, but the mix and the exact totals vary by data vendor.
Action Checklist
- Confirm options revenue held above the $399 million reported for Q3.
- Monitor Q4 options and equities volume cadence; management said October activity was very similar to, or just a touch lighter than, Q3.
- Assess implied volatility levels before sizing any premium-selling structure.
- Track crypto notional volume for sequential stabilization, given the 38% year-over-year decline in Q3.
- Watch operating expense trajectory: 16% growth versus 12% revenue growth is a compression risk if it persists.